
3 British Growth Stocks With Earnings Growth Up To 47%
European interest rates are on hold and the European Central Bank is flagging higher inflation risk as energy costs bite, which keeps pressure on returns from cash and bonds. That pushes more attention toward United Kingdom businesses that are growing quickly and where insiders own a meaningful stake. This article walks through three such high growth, high ownership stocks from the United Kingdom market that some investors are watching closely.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where leaders are heavily invested alongside you. However, if you want the absolute best, these 6 high growth high conviction stocks are the cream of the crop.
Playtech (LSE:PTEC)
Playtech is a gambling technology group that powers online casino, live dealer tables and sportsbook platforms, a model that fits tightly with the screener’s focus on recurring platform growth supported by engaged management and an optimistic outlook for regulated digital betting.
Playtech generates most of its income from B2B activities, with about €736 million from business customers alongside €65 million from Sun Bingo and other B2C operations, and a smaller HAPPYBET contribution, and the stock is valued at roughly £1 billion.
For investors tracking high growth gaming platforms, Playtech offers a way to tap into the shift toward regulated online betting where software and content can scale across multiple operators and regions.
"Playtech’s shift toward higher growth regulated markets in the Americas, with recent figures showing 176% revenue growth in the U.S. and Canada and 29% underlying growth in Latin America, gives the company scope to layer additional contracts and products onto platforms that are already live. If the planned Brazil agreement with CAIXA faces further delays beyond the current target around the beginning of 2027 or is agreed on less favorable terms, the anticipated revenue contribution and operating leverage from Brazil could arrive later or at a smaller scale than implied in the bullish case, which would weigh on Playtech's B2B revenue growth and longer term earnings."
What happens to Playtech’s earnings power ultimately hinges on how one unresolved piece of its Americas expansion shapes margins and long term growth.
If that Brazil hinge point matters to you, read the full narrative for Playtech to see how Playtech’s Americas ambitions could accelerate or stall from here.

Greencore Group (LSE:GNC)
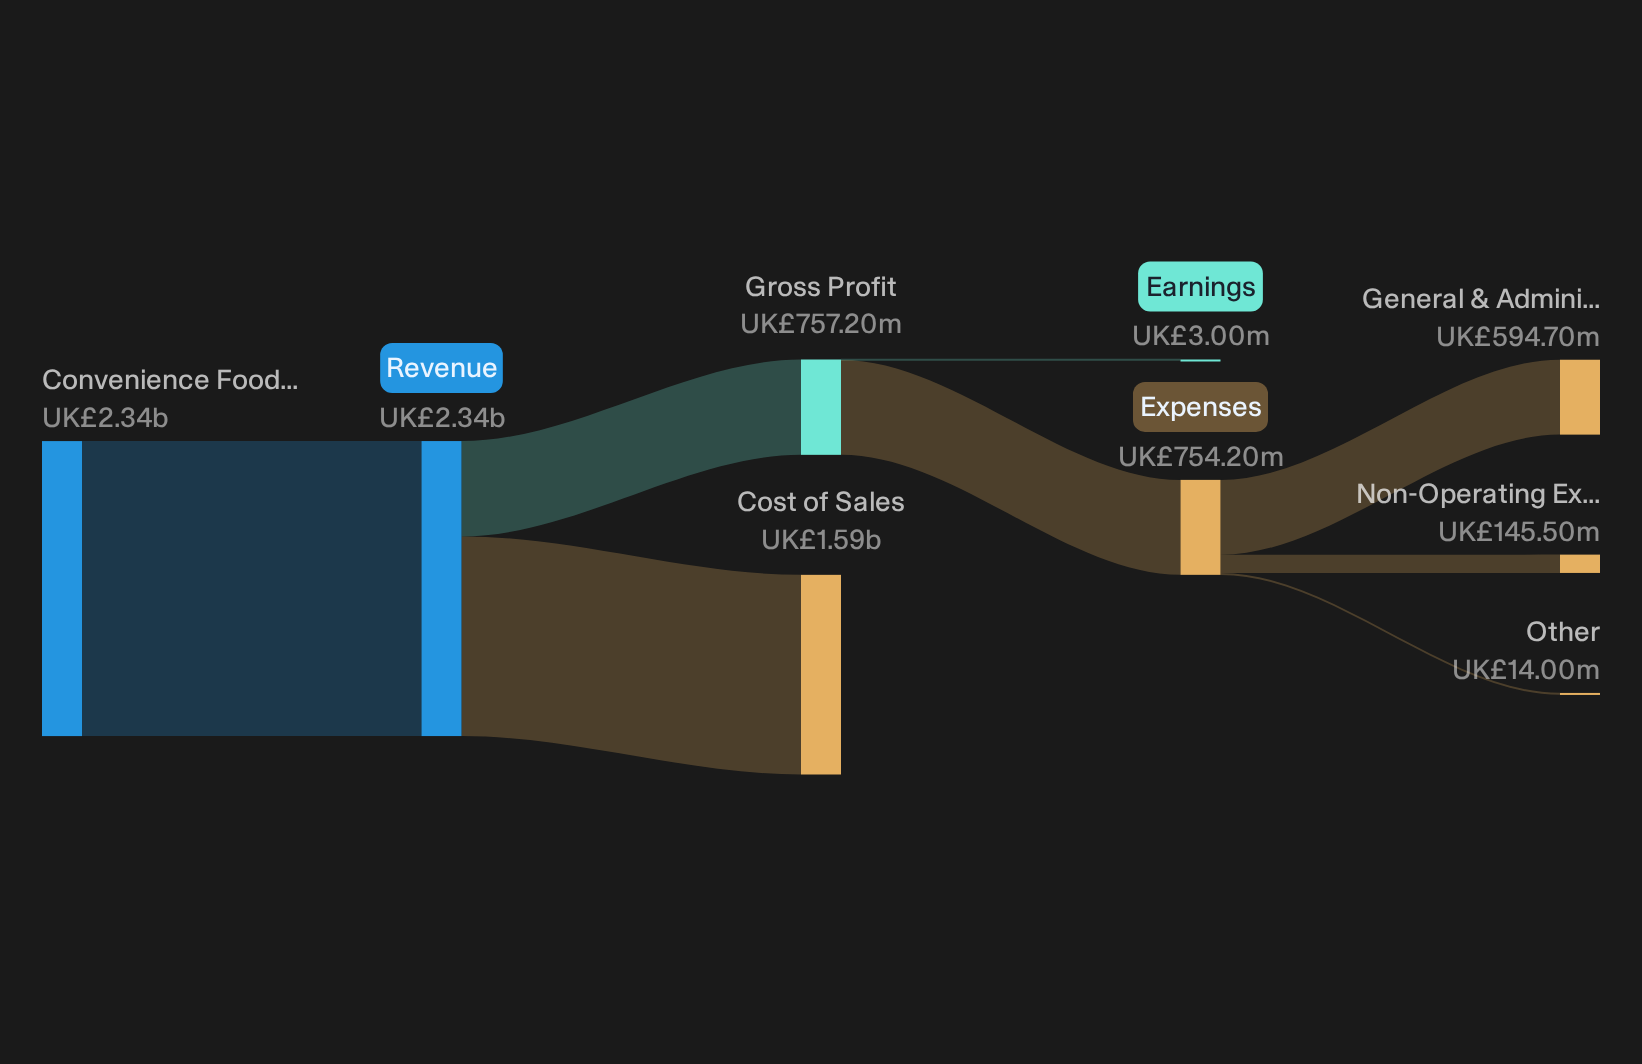
Greencore Group is a chilled convenience food specialist supplying sandwiches, salads, ready meals and snacks, where the growth potential in out of home and retail convenience channels directly ties it to this screener’s theme. Its Convenience Foods UK & Ireland unit generated about £2.3b of revenue, and the group’s market cap sits near £2.3b.
Greencore Group matters here because chilled food on the go is exactly where analysts and management see the strongest runway. Recent execution efforts are aimed at turning that demand into more durable earnings power.
"Operational excellence programs and a five year automation roadmap, which have already lifted units per labour hour and target at least 10% direct labour savings over time, can continue to support higher operating margins and earnings as more projects are rolled out across Greencore Group sites."
What happens to that promise depends heavily on how one less visible pressure on cash generation and reinvestment plans ultimately resolves.
That pressure point on cash is only part of the story, and the full narrative for Greencore Group explains how Greencore Group could turn automation into higher free cash generation and greater reinvestment capacity.
Softcat (LSE:SCT)
Softcat is a United Kingdom based IT reseller and infrastructure specialist, with a fast growing cloud and managed services practice that fits the screener’s growth focus, generating about £2.0b of revenue and supported by a market value of roughly £3.7b.
Softcat taps directly into the screener theme because its cloud heavy infrastructure and services work gives customers a way to modernise IT while locking in recurring contracts that align management and analyst expectations around continued expansion.
"Expansion into the US through the planned GDT acquisition, with GDT forecast to contribute about US$240m gross profit and US$80m adjusted EBITDA in calendar 2026, could broaden Softcat’s revenue base and support earnings growth as the combined group gains more exposure to multinational customers."
What happens to that upbeat outlook depends on how one less visible shift in profitability and cash conversion unfolds once new systems and acquisitions bed in.
That turning point is exactly what the full narrative for Softcat unpacks, including how Softcat’s US push and cash conversion could accelerate or stall from here.

Seeking Fresh Alternatives Beyond These Picks
Fresh ideas move quickly. By the time the crowd notices a breakout, early momentum can be gone or prices already flying. Scan these under the radar lists now and consider acting before they become widely followed.
- Target resilient cash generators while they are still being overlooked by the market by running your filters through the list of solid balance sheet and fundamentals (10 results).
- Hunt for recurring-income opportunities by scanning the carefully curated 4 dividend fortresses before attention concentrates on the same few tickers.
- Zero in on fast moving automation and hardware beneficiaries by tracking the hand picked 93 robotics and automation stocks while these stories are still building momentum.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com