
Fortescue (ASX:FMG) Has A Fresh Development, What Are Investors Looking At?
Fortescue (ASX:FMG) has expanded from iron ore exporting into clean power supply by signing a 20 year renewable electricity agreement with Pilbara Minerals’ Pilgangoora lithium operation through its subsidiary FMG Clean Energy.
Recent moves into clean energy come after a tough year in the market for Fortescue, with the share price down 34.10% year to date and 21.18% over 90 days. However, the 5 year total shareholder return of 55.40% still points to a much stronger longer term record.
Scan the market for other miners leaning into electrification and renewables by checking the hand picked 33 best rare earth metal stocks alongside Fortescue's clean energy pivot.
Fortescue’s clean energy push now sits against a share price that has retreated sharply in the short term, yet still shows a solid 5 year return record. How does that mix feed into what you are paying today?
Most Popular Narrative: 10% Undervalued
On the most followed view, Fortescue’s fair value sits at A$16.20, compared with a last close of A$14.59. This puts the share price at a discount while its clean energy and green metals spending reshapes the business mix.
Accelerating rollout of Fortescue’s Real Zero by 2030 program, including large scale renewables, storage and electric mobile equipment, is already cutting power costs at Eliwana and Iron Bridge and can further support net margins as diesel use is reduced and fuel savings accumulate.
See why 150 investors see Fortescue as 10% undervalued.
Result: Fair Value of A$16.20 (UNDERVALUED)
Still, if higher Hematite C1 unit costs stick or if China tightens conditions on lower grade ore, the bullish Fortescue narrative could be tested quickly.
Find out about the key risks to this Fortescue narrative.
Another View: Fortescue Through A Cash Flow Lens
The SWS DCF model paints a very different picture for Fortescue. On this approach, the fair value comes out at A$8.68 per share, well below the recent A$14.59 price, which points to the stock trading at a premium rather than a discount. Which story do you trust more: the cash flows or the crowd narrative?
For a closer look at how this cash flow based view has been built, including the key assumptions that drive it, Look into how the SWS DCF model arrives at its fair value.
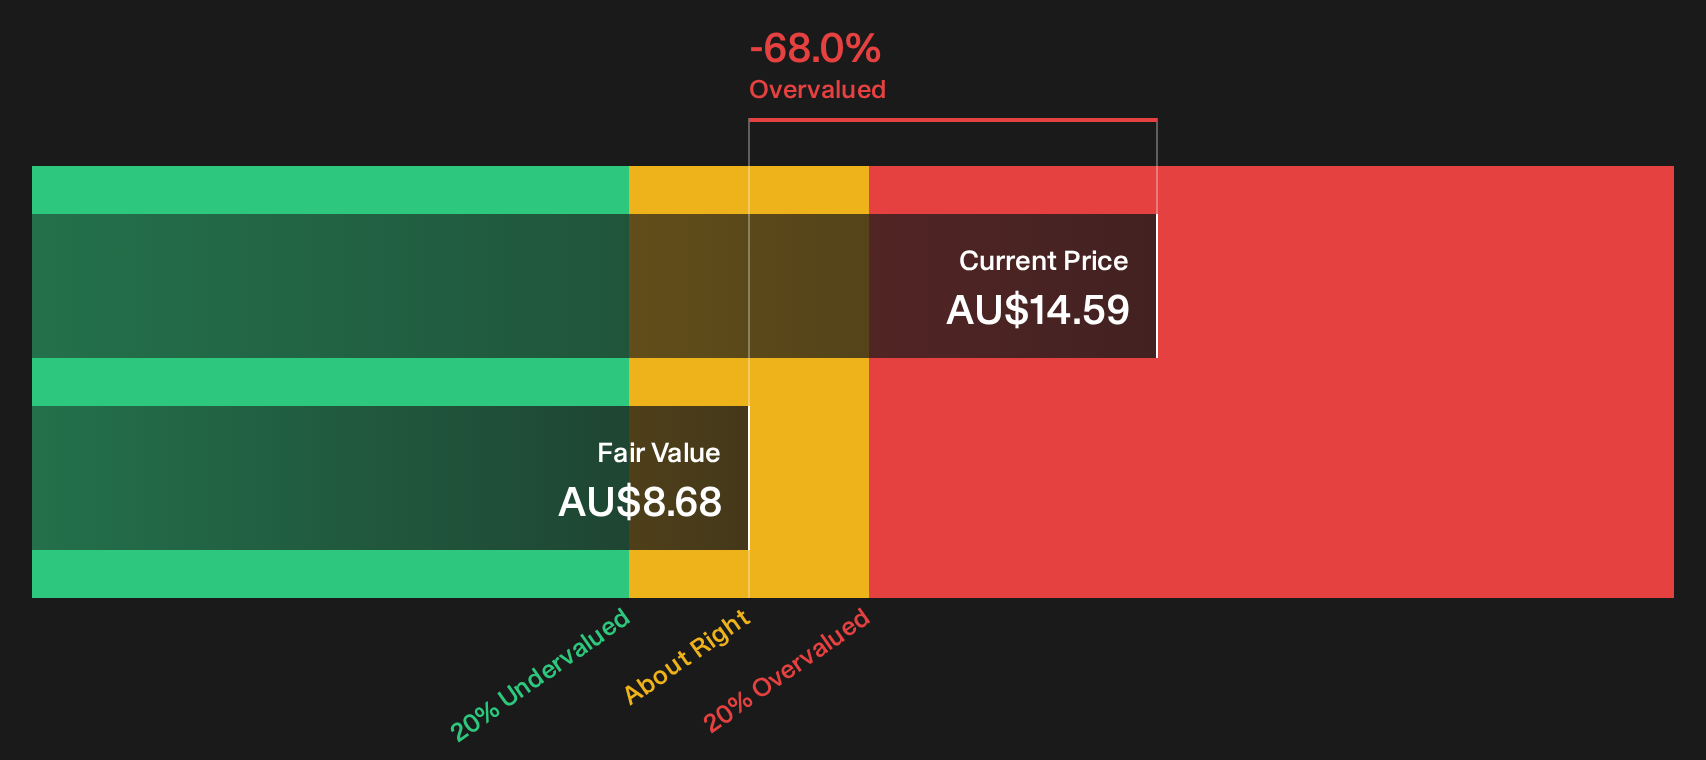
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fortescue for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 2 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views on Fortescue’s value and future direction can feel energising or unsettling, so move fast, review the underlying drivers and weigh both the 2 key rewards and 2 important warning signs
Looking for more Fortescue sized investment ideas?
Do not stop with Fortescue. Broaden your watchlist with ready made sets of stocks so you are not relying on a single narrative or sector.
- Target potential mispricing by scanning a curated group of companies that screen as undervalued on quality and price using the 2 high quality undervalued stocks.
- Build a steadier income stream by reviewing businesses that combine higher yields with staying power across sectors through the 4 dividend fortresses.
- Dial down portfolio stress by focusing on companies that clear strict risk filters and balance sheet checks via the 6 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com