
Is Progyny (PGNY) Priced At A Premium For Its Earnings?
Progyny has delivered a mixed experience for shareholders over the past few years, and the recent share price level puts a sharper spotlight on what investors are really paying for its earnings. With the stock closing at US$27.87, the key issue is how that price lines up with the fertility benefits specialist's ability to generate profit today.
- Progyny's share price has fallen 53.8% over the past 5 years, which puts long term holders squarely focused on whether current earnings now justify staying invested.
- The new menopause outcomes study, showing symptom improvement for members using Progyny's connected care model, may support arguments that the business can sustain demand and potentially reinforce its earnings base over time.
- There is a second opinion on Progyny worth weighing. See what analysts think Progyny's shares could be worth.
The stock's next move may depend on whether Progyny's current earnings are strong enough to support the price investors are being asked to pay today.
If you are weighing Progyny against other profit focused opportunities, it can help to see how a wider group of companies with earnings support are priced through the 26 high quality undervalued stocks
Does Progyny Look Fairly Valued on Earnings?
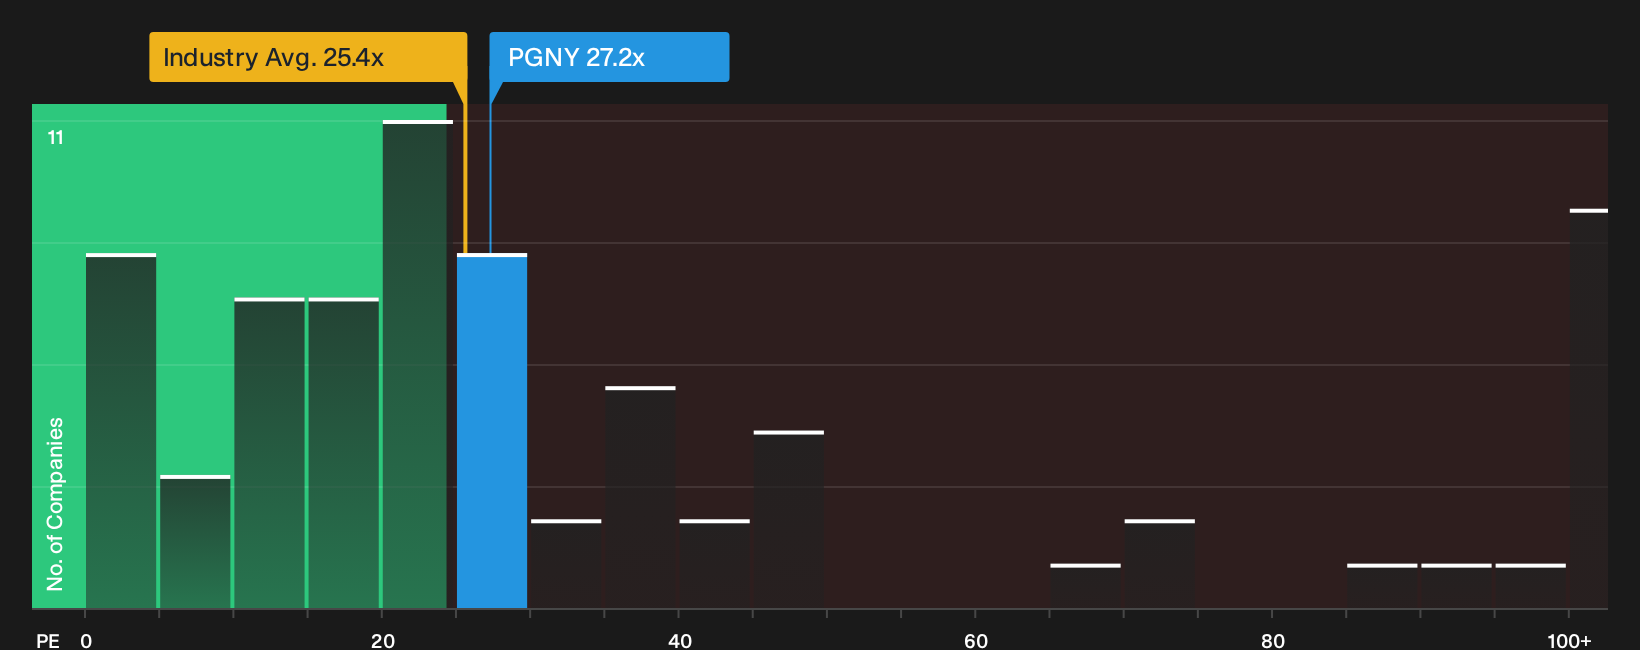
The P/E ratio suits Progyny because the business already reports profits that give a concrete earnings base. At a P/E of about 27.2x, the stock trades slightly above the broader healthcare industry average of roughly 25.4x, yet below the peer group near 34.3x. That combination suggests investors are paying a premium to the sector overall but are not assigning the same valuation as they are to some closer comparables.
Because the new menopause outcomes study highlights a defined service offering with measurable health results, the market may be giving Progyny credit for an established earnings engine rather than a purely speculative story. The current P/E also sits close to what the tailored fair multiple model would imply for a business with Progyny's mix of margins, growth expectations and risk profile, so the listed valuation does not screen as either clearly overvalued or clearly cheap on this measure. Explore the numbers behind Progyny's P/E valuation.
The Progyny Narrative: What Would Justify Today's Price?
Narratives pick up where Progyny's valuation puzzle leaves off by explaining which assumptions about future growth, profitability and earnings power would need to occur for the current share price to appear high or low. Each narrative presents Progyny's implied fair value as a specific, trackable thesis about the business, so you can observe how that view holds up over time on Simply Wall St's Community page.
One of the top community narratives on Progyny: 19% undervalued
"The valuation currently reflects that the recent share price decline following lower EBITDA guidance and modestly softer growth expectations is giving limited credit to Progyny's cash generation..."
Discover why this Narrative puts Progyny at 19% undervalued.
Progyny's valuation still leaves one powerful angle unresolved
Numbers tell only part of Progyny's story. The people setting priorities and the way they are rewarded can strongly influence how that earnings base is treated over time. See who runs Progyny and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com