
Will QatarEnergy LNG Deal Change Woodside Stock's Narrative?
- Woodside Energy Group recently agreed a 20 year LNG supply deal with QatarEnergy for up to 3 million tonnes a year from the under construction Louisiana LNG project, adding long dated volume commitments to its US growth pipeline.
- The contract gives Woodside early customer visibility for Louisiana LNG well ahead of its targeted 2029 start up. This can influence project phasing, financing choices, and how management prioritises capital between US LNG and other large developments.
- We will look at how Woodside Energy Group's investment narrative is shaped by this long term QatarEnergy offtake contract commitment.
Compare Woodside Energy Group's long term LNG story with other potential opportunities by scanning our hand picked list of 2 high quality undervalued stocks that combine quality fundamentals with attractive pricing signals.
Woodside Energy Group Investment Narrative Recap
To own Woodside Energy Group, you need to be comfortable with a business that leans heavily on long life LNG projects and disciplined capital decisions rather than rapid volume expansion. The recent quarterly update shows higher operating revenue of $4,281 million on lower production of 503 Mboe/d, which keeps the focus on price realisation, cost control, and contract quality.
The key near term swing factor is execution against full year production guidance of 174 MMboe to 185 MMboe while funding large projects and dividends from cash flow. The biggest immediate risk is that weaker volumes or higher costs pressure free cash flow coverage of the payout, especially as major projects like Louisiana LNG demand capital.
The production guidance revision is the most relevant announcement for this story. Management now expects 174 MMboe to 185 MMboe for 2026, slightly lifting the top end from 181 MMboe. For you, that frames how the Louisiana LNG contract sits alongside existing operations rather than replacing them in the near term.
In the short term, your attention is on whether Woodside Energy Group converts this guidance into consistent output and cash generation while production for the quarter and year to date sits below the prior year. Execution against that range, and the cash it generates, will influence how comfortably the group can fund large projects, service debt, and maintain dividends.
Woodside Energy Group's current narrative points to revenues of $16.1 billion and earnings of $3.2 billion by 2029, which implies forecast revenue growth of 5.1% a year and an earnings increase of about $0.1 billion from earnings today of $3.1 billion.
Uncover why Woodside Energy Group's fair value indicates that consensus views are roughly in line with its current price.
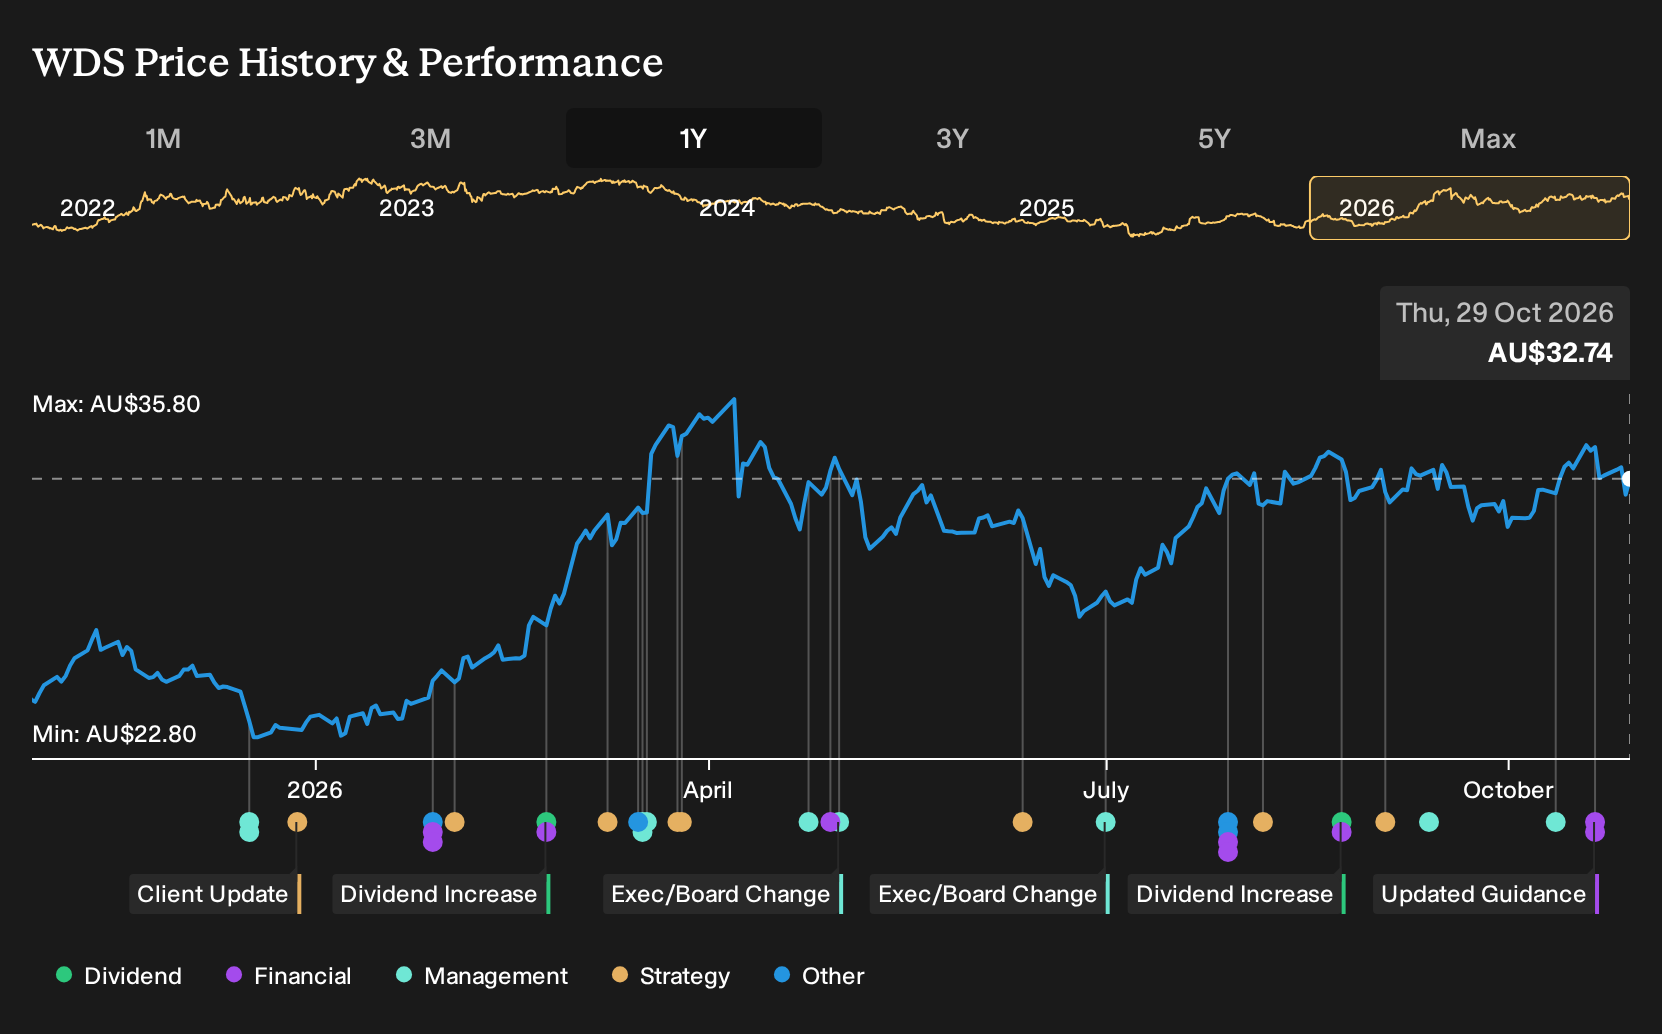
Exploring Other Perspectives
One alternate view focuses on cost cuts rather than LNG contracts. The most optimistic analysts were already pencilling in revenue of about $18.1b and earnings near $4.0b by 2029, compared with the $16.1b and $3.2b consensus. That gap shows how far opinions can stretch, and why this new QatarEnergy deal may eventually reshape both stories.
Explore 6 other Woodside Energy Group fair value estimates, including one that suggests there could be as much as 135% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own independent analysis.
- A great starting point for your Woodside Energy Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Woodside Energy Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Woodside Energy Group's overall financial health at a glance.
Looking for more investment ideas beyond Woodside Energy Group?
Once you have formed a view on Woodside Energy Group, it can help to widen the lens and compare that LNG story with companies in very different positions. The Simply Wall St Screener lets you do that quickly by filtering for financial strength, income potential, or overlooked opportunities that may better fit your risk profile and time horizon.
- If you want companies that aim to combine resilience with measured risk, consider reviewing a 6 resilient stocks with low risk scores that may suit a more conservative approach.
- For investors who care most about balance sheet strength and underlying fundamentals, run your eye over a list of solid balance sheet and fundamentals (12 results) and see which stocks clear that quality bar.
- If you prefer hunting for less crowded opportunities, scan through a 15 high quality undiscovered gems that might not yet be widely followed but still show solid financial characteristics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com