
How Investors Are Reacting To Beach Energy (ASX:BPT) Higher Western Flank Production
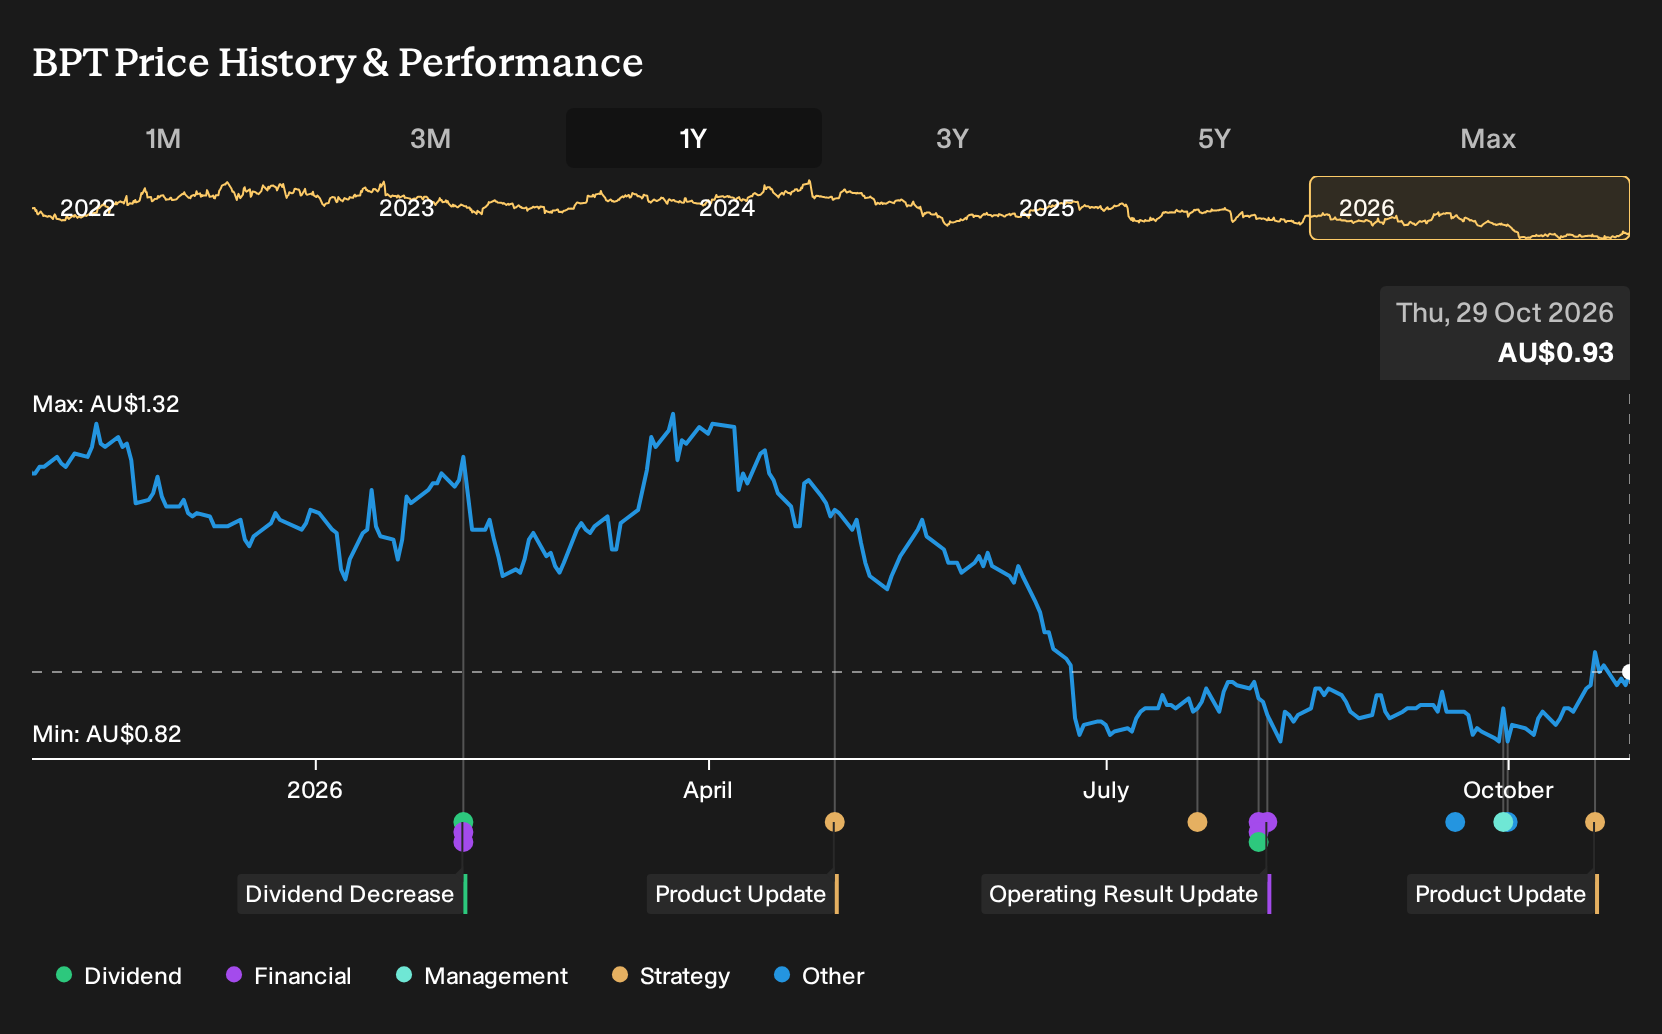
- Beach Energy reported that in the first quarter of FY 2026, Western Flank production was 15% above the prior quarter, with oil output 21% higher as flood affected wells returned and new connections were added, and most FY 2026 appraisal and development wells were online and producing in line with initial expectations.
- The planned nine well Western Flank exploration program, following two new oil development wells, indicates that Beach Energy is using its current operational momentum to test new horizons and potentially refresh its medium term drilling inventory.
- We will now examine how Beach Energy's Western Flank production gains could influence the existing investment narrative around cash generation and reserves.
Scan for other producers with drilling momentum and fresh appraisal results on your radar by reviewing the hand picked 15 high quality undiscovered gems alongside Beach Energy's Western Flank activity.
Beach Energy Investment Narrative Recap
To own Beach Energy, you need to be comfortable with a shorter reserve life and a business that leans on new drilling and potential deals to keep production steady. The Western Flank uplift in the first quarter helps the near term story on uptime and cash generation, but it does not remove the bigger reserve replacement question.
The key short term swing factor remains execution on core projects and keeping operating issues like flooding under control so volumes stay reliable. The largest risk still sits in reserves and the need for either successful exploration or acquisitions, where missteps could pressure returns and stretch the balance sheet.
The Taroom Trough farm out talks matter because they point to Beach Energy using partnerships to extend its gas portfolio rather than carrying all the spend alone. For you, the link is simple: more options in the ground can ease the reserve life issue if those assets are eventually converted into booked volumes.
This kind of transaction also plugs into the wider catalyst set around Waitsia, LNG exposure and East Coast gas contracts. Execution risk does not disappear. Farm out terms, development timing and capital intensity all influence whether new acreage supports earnings or drags on cash, so this update is one to track closely against your thesis.
What The Beach Energy Consensus Is Really Asking You To Believe
Beach Energy's narrative projects A$2.0b revenue and A$454.2 million earnings by 2029. This implies revenue declining 1.8% per year and an earnings swing of about A$570 million from a loss of A$115.9 million today.
Uncover why Beach Energy's fair value indicates a 15% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One catalyst the most optimistic analysts keep coming back to is Beach Energy’s ability to turn lower costs and tighter capital spending into higher free cash flow. Before this Western Flank and Taroom Trough news, that group was already modelling revenue of about A$2.1b and earnings near A$597.7 million by 2029. You can see how that more upbeat script might shift once fresh production data and farm out details are fully worked into these models, so treat this as a moment to compare several viewpoints rather than assume one narrative has it right.
Explore 4 other Beach Energy fair value estimates, including one that suggests potential upside of up to 331% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Beach Energy research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Beach Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Beach Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Beach Energy?
If Beach Energy is on your watchlist, it can help to set it alongside a wider bench of opportunities so you can compare quality, income and risk in one place.
- For investors hunting for potential mispriced opportunities with solid fundamentals, scan our 2 high quality undervalued stocks and see how they stack up next to Beach Energy.
- If resilience and balance sheet strength matter most to you, you can filter for companies with conservative debt and healthy liquidity using the list of solid balance sheet and fundamentals (12 results) as a reference set.
- When predictable income is a priority, line up Beach Energy against other high yield payers by reviewing the 4 dividend fortresses and weighing their payouts and profiles side by side.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com