
Enterprise Financial Services (EFSC), Why Is Its Latest Update Drawing Attention?
Enterprise Financial Services (EFSC) just packed several key updates into one day. Fresh third quarter results arrived alongside higher common dividends, a preferred payout declaration, and a clear signal on recent credit charge offs.
At a share price of $62.43, Enterprise Financial Services has seen a 3.8% 30 day share price return and a year to date share price gain of 15.5%. Its 1 year total shareholder return of 21.9% and 3 year total shareholder return of 92.0% suggest momentum has been building over time around the stock as investors weigh the latest earnings, higher common dividend and increased credit charge offs together.
Spot opportunities with a similar profile to Enterprise Financial Services by scanning our hand picked 26 high quality undervalued stocks that pair balance sheet strength with meaningful upside potential.Enterprise Financial Services just paired a higher dividend with softer earnings and heavier charge offs, which puts timing front and center. Do you press in after this run, or wait for a cleaner entry on the same story?
Most Popular Narrative: 12% Undervalued
Enterprise Financial Services is priced at $62.43 against a widely followed fair value estimate of $71, which points to a material valuation gap that rests on how the credit clean up and funding mix play out over time.
Active credit cleanup, including the expected normalization of net charge-offs toward the long run 15 bps average and progress on resolving around US$77m of Southern California real estate owned that is largely under contract or subject to offers, creates room for lower provision expense and steadier earnings once the elevated nonperforming assets work through.
See why 1 investors see Enterprise Financial Services as 12% undervalued.
Result: Fair Value of $71 (UNDERVALUED)
Still, the bullish narrative on Enterprise Financial Services hinges on cleaner credit and steadier fee income, so any renewed problem loans or choppy tax credit revenue could quickly test conviction.
Find out about the key risks to this Enterprise Financial Services narrative.
Another View: What P/E Says About Enterprise Financial Services
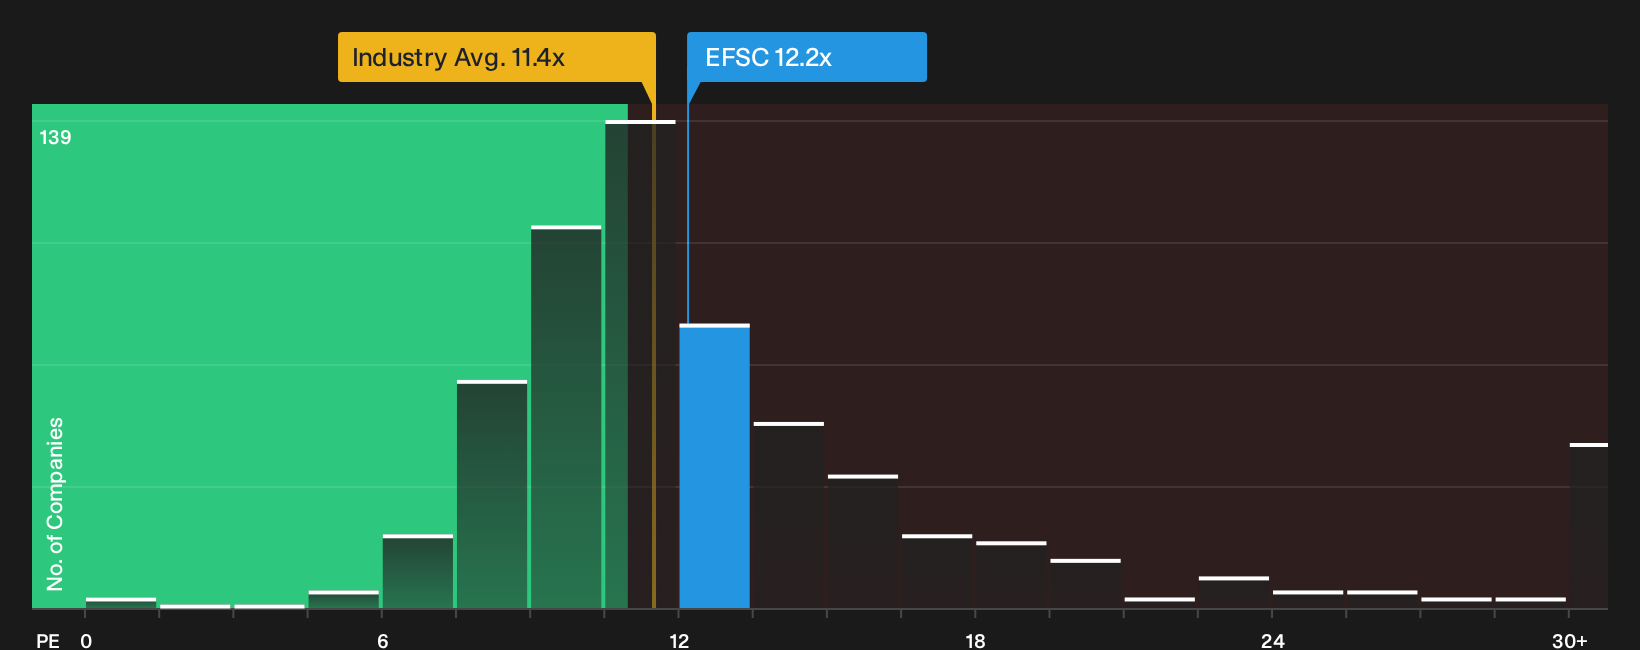
There is a very different message coming from the simple P/E check. Enterprise Financial Services trades on 12.2x earnings, compared with a 12x fair ratio estimate, a 10.2x peer average and an 11.5x US Banks industry figure. That richer tag raises a basic question for investors. Is the margin of safety really as wide as the story suggests?
For a closer look at how this pricing gap could close in either direction, including how the fair ratio might pull the current multiple toward it over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Enterprise Financial Services is mixed, so it is worth checking the underlying numbers yourself and deciding where you stand. If you want a quick way to see what others view as the bright spots in the story, start with the 3 key rewards.
Looking for more investment ideas beyond Enterprise Financial Services?
If you only stop at Enterprise Financial Services, you risk missing other opportunities that may better match your goals, time horizon, and risk comfort.
- Target dependable cash flow by scanning higher yielding opportunities in the 6 dividend fortresses that could help anchor your portfolio income.
- Hunt for mispriced quality using the 19 high quality undiscovered gems that filters for resilient businesses the market may be overlooking.
- Dial back portfolio risk by reviewing the 32 resilient stocks with low risk scores focused on companies with more conservative profiles and steadier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com