
EQT (EQT) Stock May Be A Bargain As Its $13b Deal Lands
EQT Corporation has ridden a powerful multi year run in its share price, and the latest acquisition plans have put an even brighter spotlight on what investors are paying for its earnings today. With the stock around US$56.22, the key issue now is whether the current valuation still lines up with what the business is generating in profit.
- Over the past 5 years EQT has delivered a very large 195.5% share price return, which raises the question of how much of that strength is now fully reflected in its earnings multiple.
- The agreed acquisition of Range Resources, which would create the largest vertically integrated natural gas producer in the U.S., can reshape EQT's earnings profile by affecting future margins, capital spending needs and how quickly cash flows materialize.
- There is a second opinion on EQT worth weighing. See what analysts think EQT's shares could be worth.
The issue now is whether EQT's recent share price, after that run and the planned Range Resources deal, is justified by what investors are paying for its earnings power today.
If this Range Resources deal has you rethinking what you pay for gas producers' earnings, apply the same lens to a broader group of 26 high quality undervalued stocks
Is EQT Still Cheap on Earnings?
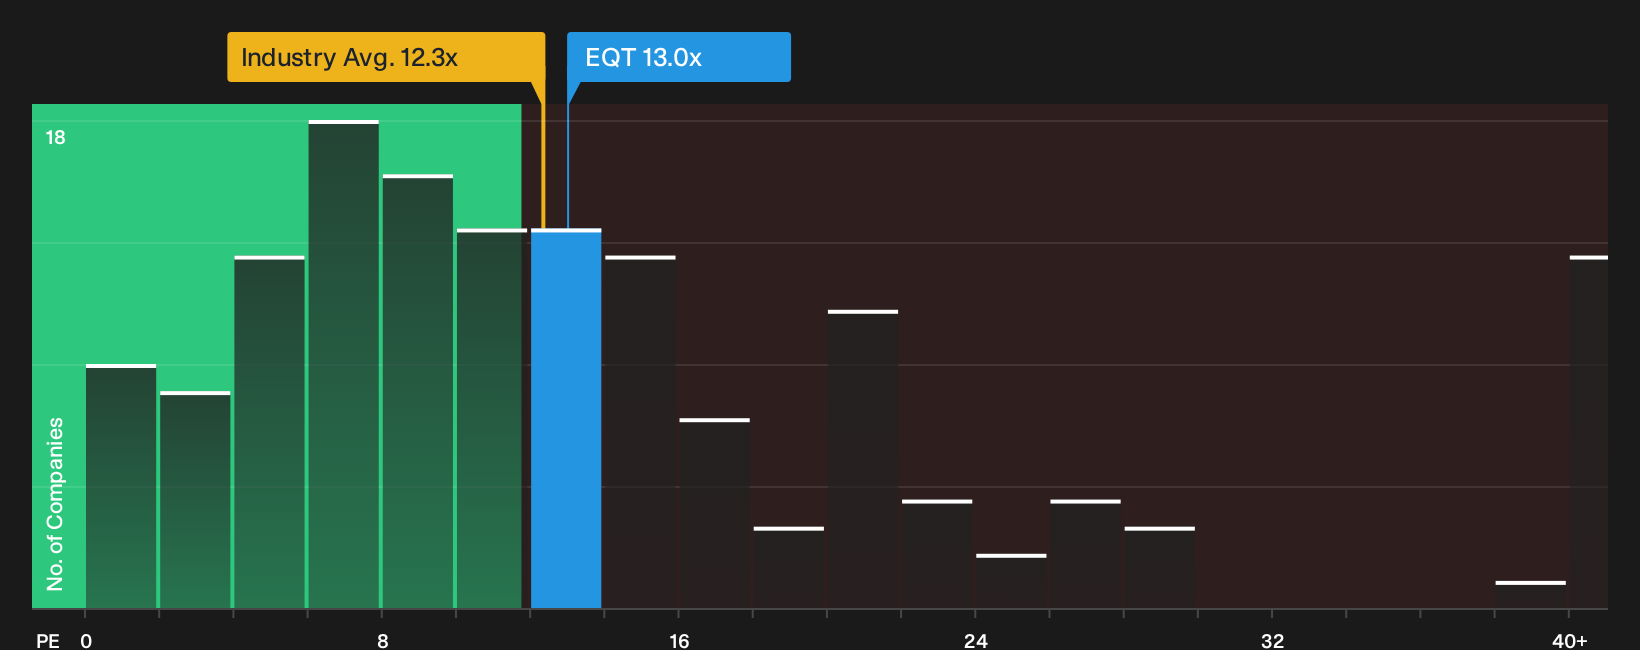
The P/E ratio works well for EQT because earnings are a key focus for investors in established producers. At roughly 12.9x earnings, EQT trades close to the wider Oil and Gas industry average P/E of about 12.3x. This suggests the market is not attaching a large sector level premium or discount. Against a broader peer set where the average P/E is about 19.5x, the stock changes hands at a visibly lower earnings multiple.
On this framework, EQT screens below the P/E level that a tailored model suggests could be justified by its mix of growth assumptions, margins, scale and risk. Because the agreed US$13b Range Resources acquisition is a sizeable swing factor for future earnings shape, the gap implies investors are still pricing in a measure of deal and integration risk even after the news. For anyone comparing gas producers on what they pay per dollar of profit, the current P/E suggests EQT is valued at a discount to that customised benchmark and to peers with higher multiples. Explore the numbers behind EQT's P/E valuation.
The EQT Narrative: What Would Justify Today's Price?
EQT's valuation puzzle only really becomes clear once the underlying storylines are spelled out. This is what Simply Wall St Narratives on the Community page aim to do by setting out what would need to happen to growth, margins and earnings for the stock to be worth materially more or less than today. Each narrative ties its number to a clear view on how EQT's future scale, profitability and risks might evolve, giving you a reference point to revisit as fresh information comes through.
Community views on EQT are split between those who see the integrated gas platform as underappreciated and those who think regional pricing still caps the upside.
Bull case: 15% undervalued
"Analysts expect EQT to translate long-term gas contracts, new power and data center-linked demand, and expanded infrastructure into durable, high-quality free cash flow…"
Discover why this Narrative puts EQT at 15% undervalued.
Bear case: 6% overvalued
"Although EQT is lining up long dated gas supply for new power and data center projects in Appalachia, the recent dip in regional spot prices to the company’s own shut in trigger near $1.50 per MMBtu suggests pipeline constraints could still force curtailments…"
Explore why this Narrative puts EQT at 6% overvalued.
The share price is only one piece of the EQT story
Before making any judgment on EQT, it helps to ask who is steering the business, how their incentives are set, and whether those rewards truly line up with your interests. See who runs EQT and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com