
3 US Stocks Riding AI Data Center Spending Growth
AI investment is no longer a side story; it is one of the main forces shaping U.S. growth as capital pours into data centers, chips and cloud infrastructure. That surge creates both potential winners and vulnerable bystanders, and missing the difference can be costly. This article walks through three quality U.S. stocks exposed to this AI spending wave, explaining how the latest macro signals could influence their next chapter.
The three stocks profiled below are just a starting sample, since the full screen surfaced 29 more large cap U.S. companies tied to the AI build out with equally compelling business stories that are not covered here. To see the broader field and quickly identify which tickers best fit your own thesis on AI led U.S. growth, go straight to the US Quality Growth Stocks Leveraged to AI-Led Economic Expansion screener.
Western Digital (WDC)
Overview: Western Digital develops and sells hard disk drive based storage systems that underpin data centers, cloud services and AI workloads globally.
Operations: Western Digital generates about US$14.5b from Hard Disk Drives, with reported regional disclosure including US$2.2b from Europe, the Middle East and Africa.
Market Cap: US$142.6b
Western Digital matters for this AI-focused screen because it supplies the bulk storage that keeps ever expanding AI data flows both affordable and online. This ties the stock directly to how aggressively hyperscalers and enterprises keep building out their infrastructure.
"First, capacity. The whole thesis rests on the duopoly holding the line. The moment either player, or a cash-rich new entrant, decides to chase this demand with new plants, the shortage becomes a glut, as it always has in memory and storage."
What happens to Western Digital's rich AI-fueled economics if a single unseen pressure quietly flips that balance in the years ahead?
If that supply trigger worries you, read the full narrative for Western Digital to see how Western Digital’s AI story could still accelerate even if the duopoly comes under strain.
Riskified (RSKD)
Overview: Riskified runs an AI and machine learning based e-commerce risk platform that helps online merchants approve more orders while tackling fraud.
Operations: Riskified currently generates about US$368 million in revenue from Security Software & Services that support global online commerce.
Market Cap: US$1.2b
Riskified fits this AI led growth screen as online fraud gets more complex and merchants spend more on smarter protection that can lift approval rates and keep checkout experiences smooth.
"Accelerating complexity and sophistication of online fraud (especially with the emergence of Agentic Commerce and AI-driven attack vectors) is prompting merchants to increase spending on advanced fraud prevention, creating new budget opportunities and raising Riskified's total addressable market, likely supporting sustained revenue and platform expansion."
What happens to Riskified’s improving profitability story if one key assumption about how merchants share the gains from higher approvals quietly shifts?
That quiet shift is exactly what could reshape the Riskified story, and the full narrative for Riskified lays out how merchant behavior, pricing power and AI spend might really be interacting.

IES Holdings (IESC)
Overview: IES Holdings designs and installs electrical, communications and technology infrastructure for U.S. data centers, commercial projects and housing.
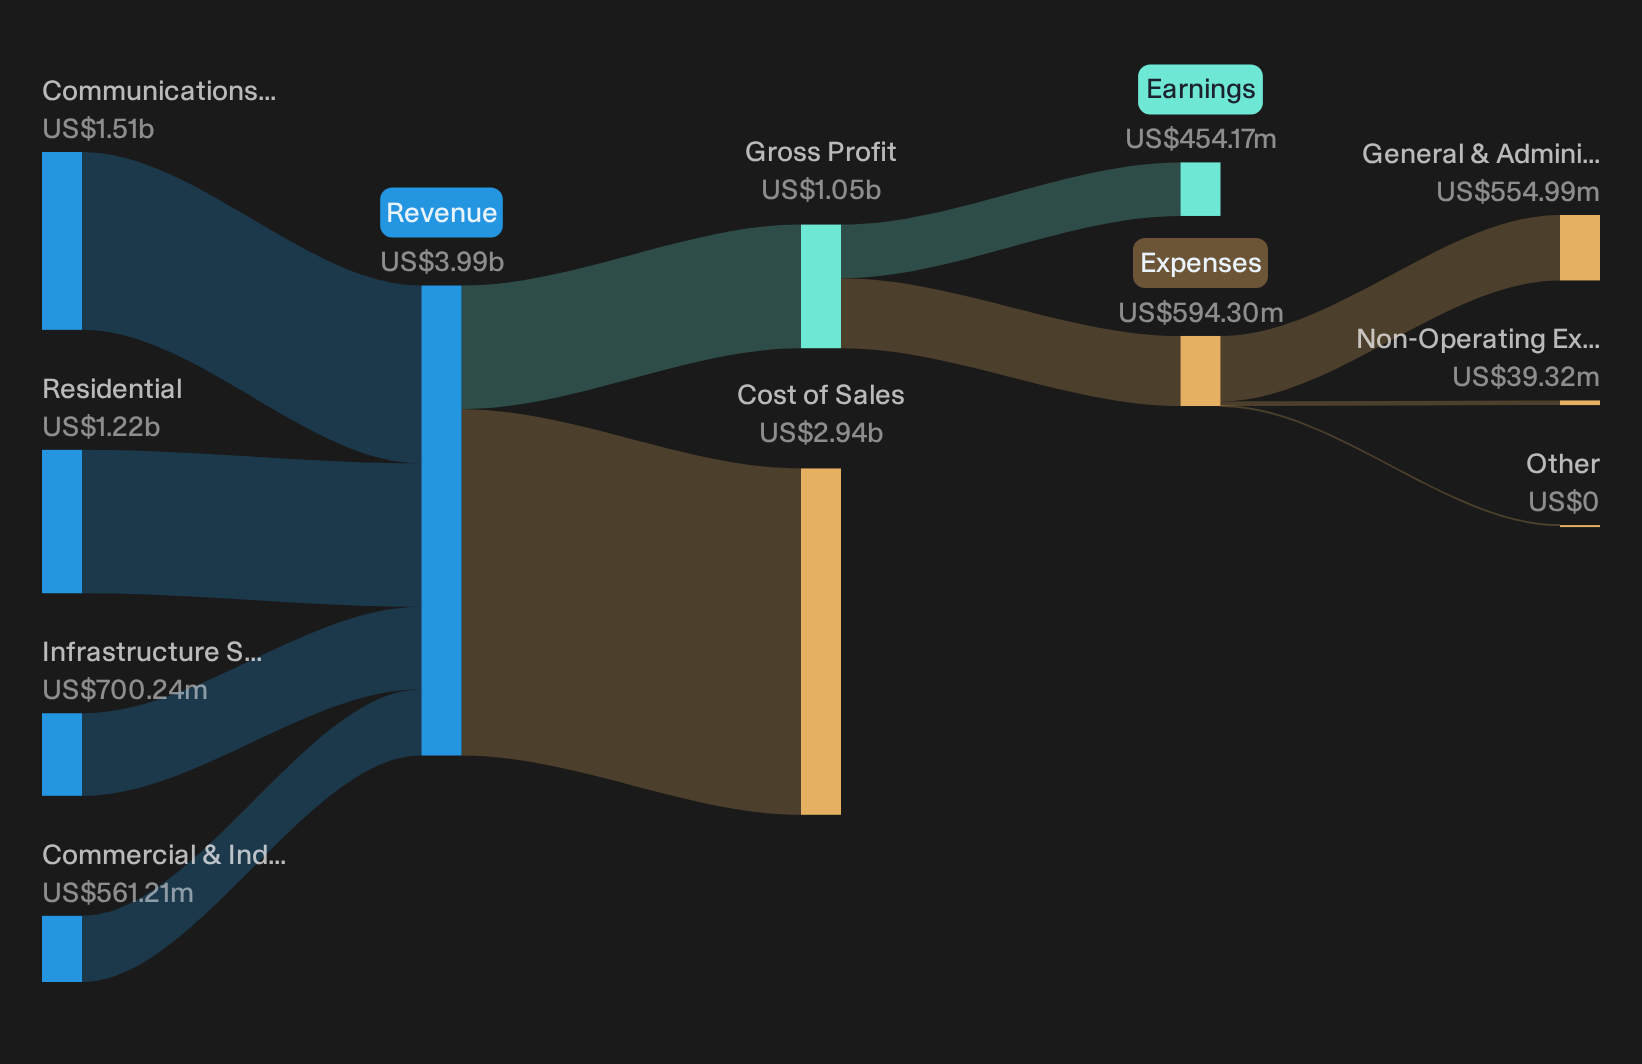
Operations: IES Holdings generates about US$1.5b from Communications, US$1.2b from Residential, US$700 million from Infrastructure Solutions and US$561 million from Commercial & Industrial, almost entirely in the United States.
Market Cap: US$9.1b
IES Holdings matters in this AI-focused screen because it wires and equips the physical sites where data center and cloud demand actually show up, turning software ambitions into power, steel and low-voltage systems on the ground.
"IES is well positioned to continue making a healthy impact within it's sector due to the continued demand for hyperscaling datacenter construction."
The real swing factor is what happens to that promising setup if one concentrated source of data center work suddenly cools or overruns costs.
That concentration risk is exactly why the full narrative for IES Holdings examines how IES Holdings could keep accelerating even if big data center buildouts pause or shift direction.
Seeking Alternatives Before Markets Catch Up?
Fresh themes are breaking out while attention stays glued to headline tickers. Spot under the radar moves before momentum flies away and the data goes stale. Get in early.
- Target resilient payouts while prices swing and use the 6 dividend fortresses to focus on higher yielding businesses that still carry solid underlying fundamentals.
- Hunt for financially strong operators by running the list of solid balance sheet and fundamentals (24 results) so you narrow in on balance sheets built to handle tougher conditions.
- Channel your curiosity toward future materials demand and scan the 33 best rare earth metal stocks for producers tied to important long term technology supply chains.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com