
Why Kemper Stock Is Getting Attention After Profit Guidance Turned Positive
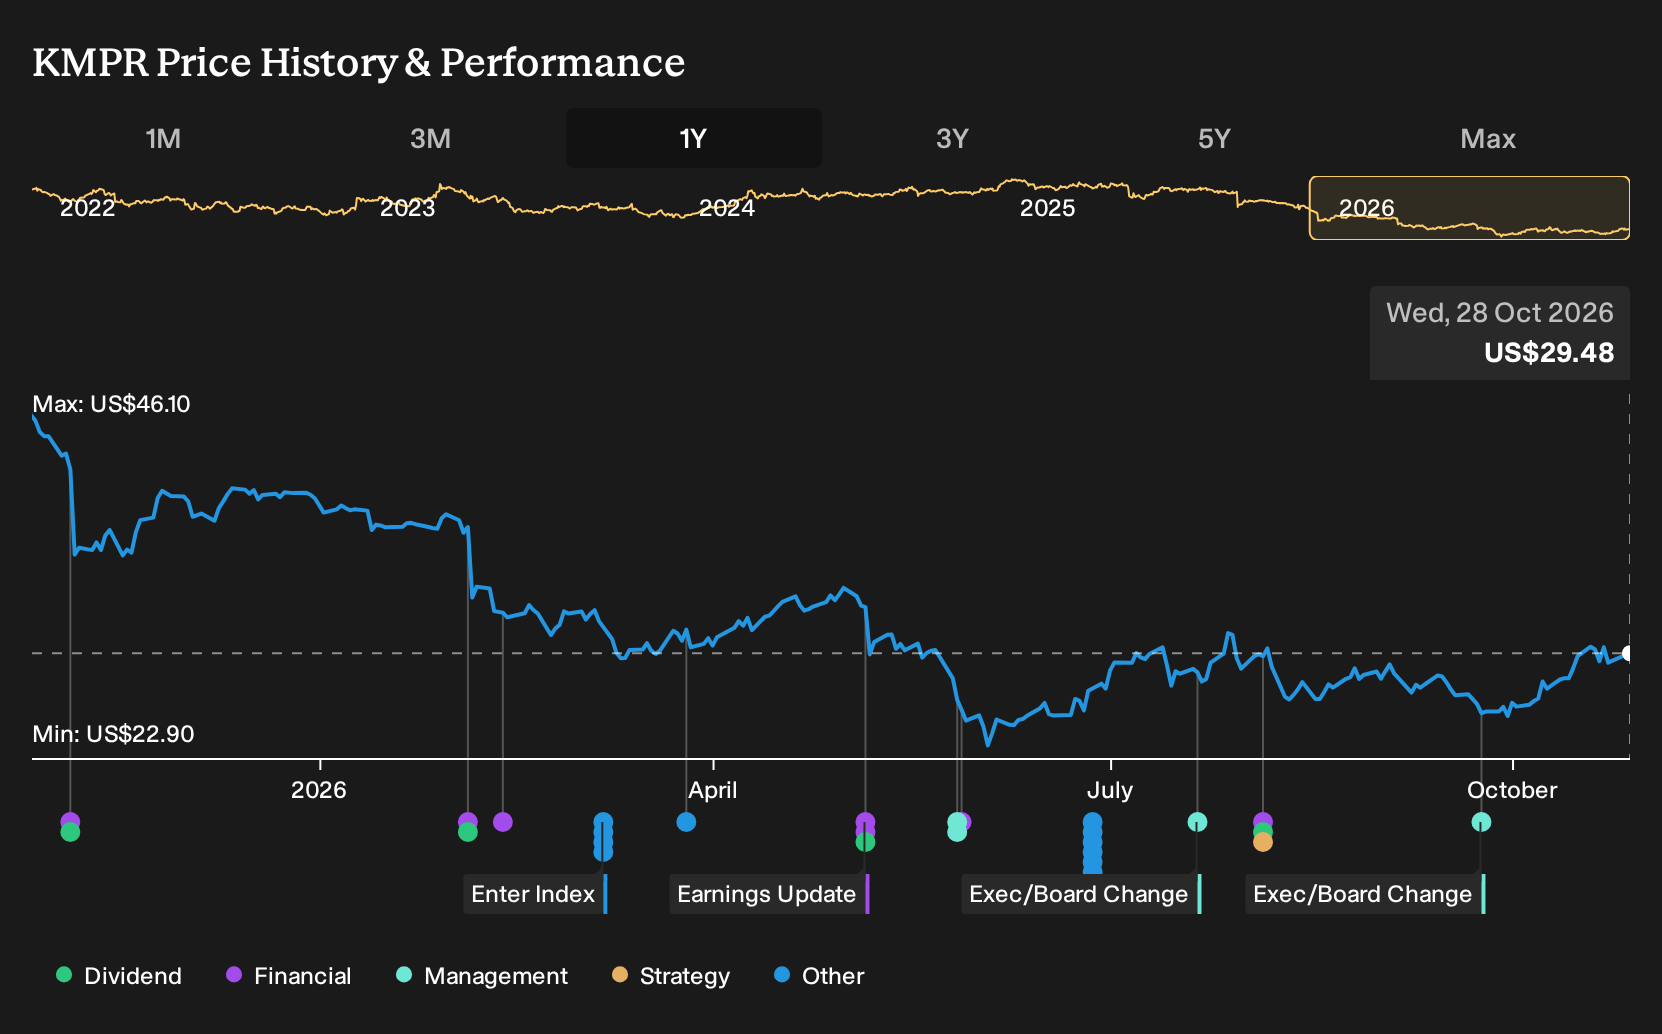
- Kemper Corporation issued third quarter 2026 earnings guidance indicating expected net income of about US$52 million, or US$0.88 per diluted share, compared with a reported net loss of US$465 million, or US$7.90 per share, in the second quarter of 2026.
- The swing from a large prior quarter loss to guided profitability highlights how recent restructuring efforts and portfolio repositioning are starting to show up in Kemper's projected bottom line rather than just in narrative updates.
- This analysis will examine how Kemper's investment narrative is affected by the guided shift from a Q2 loss to Q3 profitability.
Compare Kemper's guided turnaround with other insurers potentially setting up similar rebounds by scanning our hand picked 32 resilient stocks with low risk scores aligned with resilient financial profiles and controlled risk scores.
Kemper Investment Narrative Recap
To own Kemper, you need to believe the heavy lifting in specialty auto restructuring and cost cuts can eventually show up in cleaner, recurring earnings, not just one off impairment adjustments. The guided swing to about US$52 million of Q3 2026 net income puts the focus on whether pricing, claims and expenses are actually tracking to plan.
The key short term catalyst is evidence that California personal auto and broader specialty auto underwriting are becoming more sustainable after the large Q2 loss. The biggest near term risk remains further earnings pressure if rate actions, claims trends or credit loss allowances undercut that improving profitability story.
The most relevant datapoint against this guidance is still the roughly US$464.8 million Q2 2026 net loss, driven mainly by a US$460 million non cash goodwill impairment in specialty auto. That number keeps the spotlight firmly on how volatile that segment can be for Kemper’s reported earnings.
As you weigh catalysts, that impairment and the earlier US$21 million allowance for credit losses on surplus notes at Kemper Reciprocal Exchange define the execution bar. Any miss on underwriting discipline, rate adequacy or investment income could quickly challenge the guided Q3 profit and extend the timeline to steadier returns.
Kemper Long Term Consensus Bridge
Kemper's narrative projects US$4.3b revenue and US$527.0 million earnings by 2029. That profile lines up with analysts assuming revenue will decline 2.2% per year while profit margins move from a reported loss of about US$495.5 million today to the guided US$527.0 million profit, which is an earnings swing of roughly US$1.0b.
Uncover how Kemper's fair value indicates a 23% potential upside to its current price before that gap closes.
Exploring Other Perspectives
Some bullish analysts focused on Kemper’s data driven underwriting saw a different story before this guidance. They were penciling in about US$4.6b of 2029 revenue and roughly US$488.8 million of earnings. If you want that more optimistic earnings power to hold after the Q3 outlook, compare how those views might now shift.
Explore 3 other Kemper fair value estimates, including one that suggests potential upside of up to 88% from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and approach the opportunity independently.
- A great starting point for your Kemper research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kemper. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kemper's overall financial health at a glance.
Looking For More Ideas Beyond Kemper?
If you want to stress test your thesis on Kemper against other opportunities, it helps to scan a wider field of companies with clear financial profiles and different risk and return trade offs.
- For investors hunting for mispriced quality, start with a curated set of companies that screen as high quality yet potentially overlooked by checking the 26 high quality undervalued stocks.
- If balance sheet strength sits high on your checklist, compare Kemper with a list of solid balance sheet and fundamentals (24 results) to see which businesses pair resilient finances with consistent fundamentals.
- Income focused readers can round out their watchlist by reviewing a 6 dividend fortresses that filters for companies offering higher yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com