
Energy Fuels (TSX:EFR) Lands Donald Project Financing As Fair Value Debate Heats Up
Energy Fuels (TSX:EFR) has just secured conditional credit approval for up to A$180 million in Australian government backed financing for Phase 1 of the Donald Rare Earth and Mineral Sands Project in Victoria.
That government backed funding news arrives after a tough stretch for Energy Fuels shareholders. The stock has fallen about 49% on a year to date share price basis and the 1 year total shareholder return is down about 59%. However, the 3 year total shareholder return is still slightly positive. This suggests recent momentum has been weak and investors are reassessing risk as the rare earth and uranium plans progress.
Scan beyond Energy Fuels and compare this rare earth financing story with a curated list of 33 best rare earth metal stocks that are also tied to critical minerals and supply chain projects.
The sharp slide in Energy Fuels shares could signal doubts about its rare earth build out, or it could have run ahead of the underlying projects. That tension is exactly what the valuation now needs to unpack.
Most Popular Narrative: 69% Undervalued
On the most followed narrative, Energy Fuels screens as materially undervalued, with a fair value of CA$38.13 against a last close of CA$11.73. This puts the spotlight on how its uranium and rare earth plans feed into that gap.
Multiple shovel-ready or advancing heavy mineral sands and rare earth projects (Donald in Australia, Toliara in Madagascar, Bahia in Brazil) are nearing final feasibility and investment decisions. These projects could unlock significant production scale, diversify feedstock supply, and drive step-changes in revenue and gross profit as government support for non-Chinese supply chains intensifies.
See why 62 investors see Energy Fuels as 69% undervalued.
Result: Fair Value of CA$38.13 (UNDERVALUED)
Still, this story can break if rare earth feedstock remains tight or if large project funding for Donald and other developments proves slower and more expensive than hoped.
Find out about the key risks to this Energy Fuels narrative.
Another View: Energy Fuels Looks Expensive On Sales
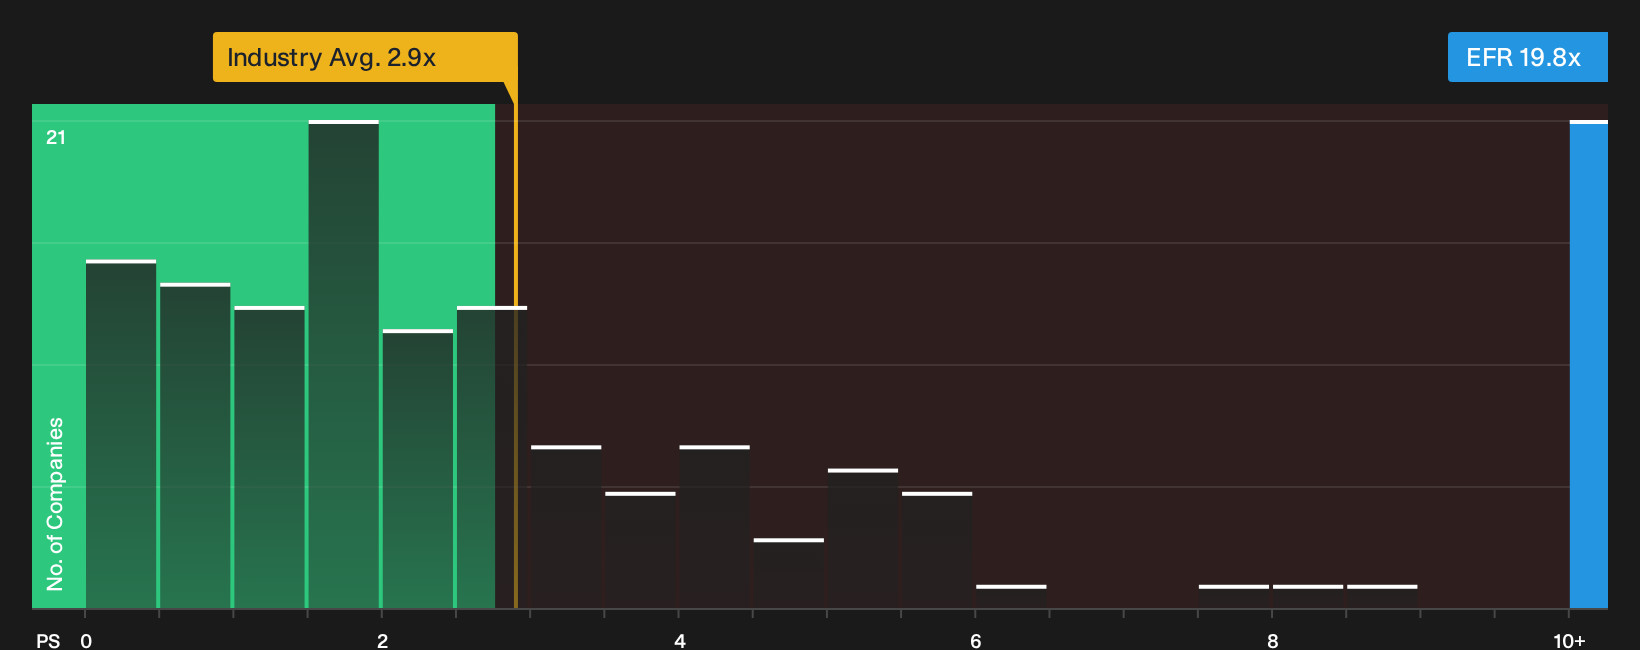
Price against fair value screens Energy Fuels as cheap, with the shares trading about 40% below an estimated CA$19.56 cash flow value and 69% below the CA$38.13 narrative fair value. On sales, the picture flips. The stock trades on a P/S of 19.8x versus an industry average of 2.9x and a fair ratio of 2.5x, which points to a very rich revenue multiple and heightens the risk if those bullish growth assumptions slip at all.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Energy Fuels draws strong opinions on both sides, so consider acting promptly and carefully stress test the story against your own expectations. To weigh the potential upside that some investors are focused on, start by reviewing the 2 key rewards.
Looking for more investment ideas beyond Energy Fuels?
Do not stop with a single ticker when there are entire shortlists built to surface fresh ideas that match the way you like to invest.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (6 results) that filters for financial strength first.
- Hunt for mispriced opportunities by reviewing a focused 4 high quality undervalued stocks that screens for quality businesses trading below estimated worth.
- Prioritise stability and lower downside risk by checking a tailored 8 resilient stocks with low risk scores built around companies with more defensive profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com