
3 Eurozone Financial Stocks Built For Higher ECB Rates
Eurozone interest rates are moving higher, energy pressures remain a drag and the European Central Bank is signaling tighter financial conditions just as growth estimates soften. That mix can punish weaker balance sheets yet reward businesses whose income benefits from higher yields. This article walks through three eurozone financial stocks that screen well for basic quality and could be positively exposed to the current ECB backdrop, helping you stress test your own watchlist.
The three stocks discussed next are just a sample from a wider pool, and the full screen surfaced 7 more eurozone banks and financial groups with similarly compelling stories that are not covered in this article.
If you want to quickly identify, compare, and analyze those additional rate sensitive ideas side by side, head straight to the Eurozone Banks and Rate-Sensitive Financials screener.
Triodos Bank (ENXTAM:TRIO)
Overview: Triodos Bank is a eurozone retail and business lender. Its deposit and loan margins are closely linked to European Central Bank interest rates.
Operations: Triodos Bank generates most of its income in the Netherlands at about €193 million, with additional contributions from the UK, Spain, Belgium and its investment management arm.
Market Cap: €496 million
Triodos Bank matters for this screener because it is a pure play on eurozone retail and business banking. Every shift in ECB policy ripples quickly through deposit pricing, loan yields and the outlook for its mission driven lending book.
"Management has already announced the sale of the non-core German fibre-optic portfolio, and the Dutch central bank also removed Triodos’ MREL requirement in April 2026, which slightly eases the capital and funding burden."
What happens to Triodos Bank’s earnings profile from here largely hinges on how one unresolved pressure on its credit costs ultimately plays out.
That unresolved pressure is exactly what the full narrative for Triodos Bank unpacks, highlighting how Triodos Bank’s mission lending could be either masked risk or accelerating opportunity.
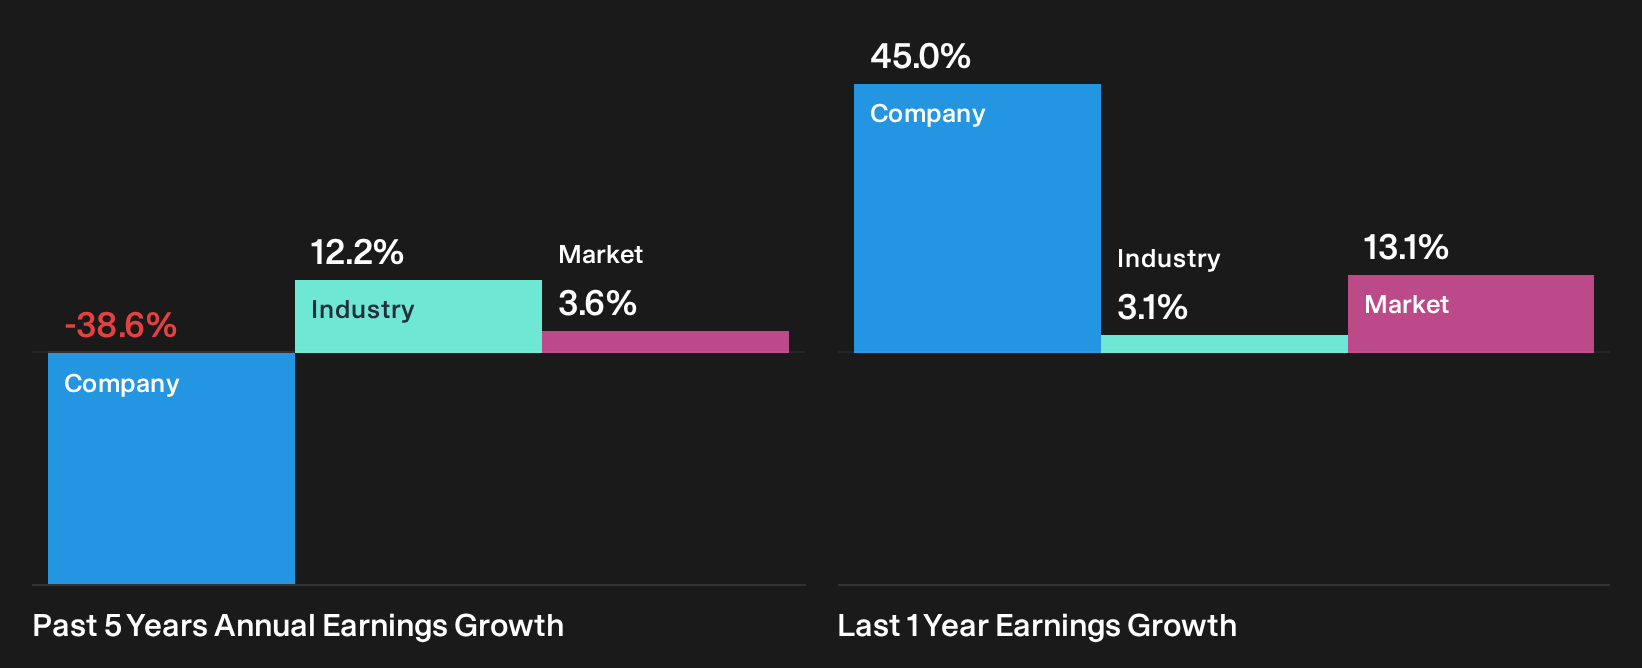
MLP (XTRA:MLP)
Overview: MLP is a German financial services group that advises households and businesses on insurance, banking, investments and retirement solutions, fitting the eurozone rate sensitive financials theme.
Operations: MLP generates most of its revenue from Financial Consulting at about €425 million, with FERI at €266 million and Banking at €230 million, complementing insurance, industrial and real estate activities.
Market Cap: €1.2b
MLP matters in this screener as a more advisory focused alternative to eurozone banks, where earnings still lean on interest rates, bond markets and client risk appetite across wealth, pensions and insurance.
"Ongoing investments in artificial intelligence and digital platforms across MLP, including tools for claims handling and adviser support, are driving process automation and cost efficiency, which can support net margins and earnings."
What happens if a single assumption about how clients respond to tighter ECB policy and higher funding costs quietly shifts over the next few years?
That question is exactly why the full narrative for MLP digs into how client behaviour, fee flows and interest income could be quietly decoupling from headline ECB moves.

BAWAG Group (WBAG:BG)
Overview: BAWAG Group is a Vienna based banking group focused on eurozone retail, SME and corporate lending that is closely linked to ECB rate trends.
Operations: BAWAG Group generates about €1.8b from Retail & SME activities and €291 million from Corporates, Real Estate & Public Sector, plus a smaller segment adjustment.
Market Cap: €12.5b
BAWAG Group sits right in the sweet spot of this screener, with a eurozone focused loan book that reflects ECB moves directly through deposit margins, unsecured lending yields and credit quality.
"Integration and delivery of the PTSB acquisition, which is expected to be P&L accretive from day one and to contribute more than €250 million of net profit by 2028 with over 20% EPS accretion after three years, could support higher earnings and improve the valuation multiple if BAWAG Group executes as planned."
What happens if a single assumption about how far BAWAG Group can push unsecured and card lending without pressuring risk costs starts to shift?
If that risk and reward balance is what you care about, the full narrative for BAWAG Group shows where BAWAG Group’s earnings engine could be accelerating or quietly stalling.

Seeking Alternatives Before Momentum Runs
Fresh ideas move first. Once a theme catches momentum, entry points can start flying or dropping fast. Scan under the radar for now and act early.
- Consider early-stage breakouts in smaller companies that already post solid numbers with the 607 high quality undiscovered gems before their stories get fully caught by the crowd.
- Focus on resilient balance sheets built for shocks using the list of solid balance sheet and fundamentals (207 results) while valuations still reflect old expectations instead of potential shifts in the cycle.
- Explore the income trend as yields remain in focus by tapping into the curated 227 dividend fortresses before payout momentum attracts more investors to the same trades.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com