
Will Record Earnings Change Seagate Stock Narrative
- Seagate Technology Holdings reported record fiscal Q1 2027 results, with sales of US$4.23b, net income of US$1.76b and sharply higher earnings per share compared with the prior year.
- The business paired this profitability with a higher quarterly dividend, meaningful debt reduction and long-duration data center storage commitments that extend toward 2030, tightening the link between AI demand and future cash generation.
- The focus now turns to how Seagate’s record quarter and stronger dividend profile may reshape its investment narrative and long-term appeal.
Scan the AI storage theme beyond Seagate Technology Holdings by reviewing hand picked 54 AI infrastructure stocks that are also tied directly to data center build outs and hyperscaler demand.
Seagate Technology Holdings Investment Narrative Recap
To own Seagate Technology Holdings, you need to believe AI driven data center storage remains the anchor for the business and that HAMR based Mozaic drives keep pulling a larger share of nearline capacity. The record fiscal Q1 2027 results, together with strong guidance for fiscal Q2 2027, reinforce that thesis in the near term rather than change it.
The key short term swing factor is whether hyperscaler demand, long dated storage contracts and pricing discipline hold up against any emerging concerns about shipment growth and industry supply. The biggest risk is that high expectations, concentrated exposure to nearline HDDs and any trade or policy shock trigger a sharp reset in sentiment even if operations stay healthy.
The most relevant recent announcement is Seagate’s fiscal Q1 2027 report, paired with guidance for fiscal Q2 2027 revenue of about US$4.8b, plus or minus US$100m. That update ties directly into the existing catalyst list, because it speaks to how Mozaic HAMR drives, long term data center agreements and price per exabyte trends are flowing into actual sales and earnings.
For you as an investor, the operational story now leans on Seagate turning those record quarterly numbers, higher dividend and debt reduction into repeatable cash generation while shipment volumes and industry capacity are closely watched. The tension between strong reported profitability and concerns about future supply, AI spending durability and sentiment driven repricing is what likely drives the risk reward profile from here.
What Analyst Expectations Assume For Seagate Technology Holdings
Analysts that follow Seagate Technology Holdings are effectively sketching out a very different earnings profile for the business by the late 2020s. Their models lean heavily on AI linked storage demand, higher profit margins and long duration customer agreements to justify current price targets.
According to the consensus assumptions, revenue is projected to rise at about 37.3% a year over the next three years. Profit margins are modeled to move from 26.1% today to 51.4% in three years, which would reshape how much of each dollar of sales turns into profit if it plays out as expected. Those margin and growth inputs sit behind the record fiscal Q1 2027 print and the debate about how durable the current cycle could be.
Current earnings for Seagate Technology Holdings are cited at US$3.2b. The same analyst group expects that figure to reach US$16.2b by around 2029, with some forecasts running as high as US$19.1b. That implies earnings a little over 5x higher than today at the consensus level, and even more at the top end of the range, although there is clear disagreement about how far that step up can realistically go.
On top of that, the analyst framework builds in roughly 6.13% annual growth in the share count for the next three years and uses a discount rate of 8.3% to translate those future cash flows back to today. The key moving pieces for you are straightforward: faster top line expansion, higher margins and a higher earnings base by 2029 are all assumed, and the narrative around Seagate’s AI storage exposure is what ties those numbers together.
Seagate Technology Holdings' narrative projects US$31.5b revenue and US$16.2b earnings by 2029. This rests on revenue growing at about 37.3% a year and earnings rising by roughly US$13.0b from the current US$3.2b base.
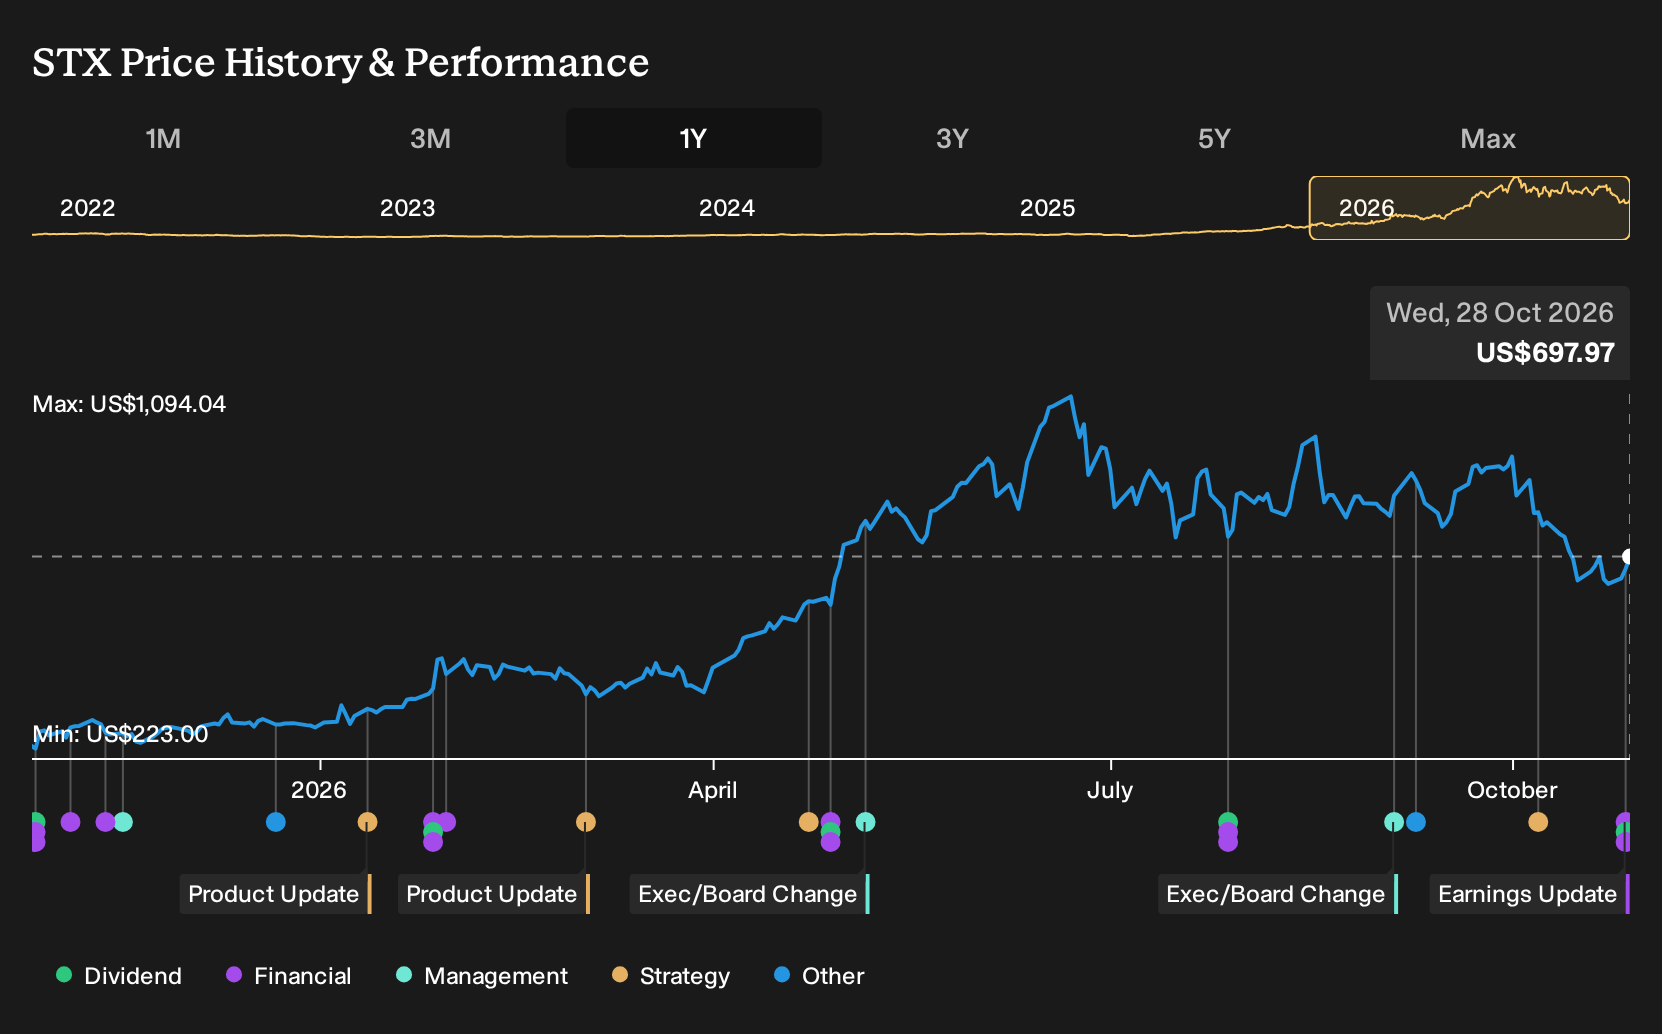
Uncover why Seagate Technology Holdings' fair value indicates a 56% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most bullish Seagate Technology Holdings analysts were already penciling in about US$36.8b of revenue and US$19.0b of earnings by 2029, assuming tight supply and premium pricing hold. You now have record Q1 results, a higher dividend and fresh guidance, all set against that optimistic script. Use this as a cue to compare several viewpoints and decide which assumptions feel realistic to you, knowing these models were built before the latest earnings news.
Explore 5 other Seagate Technology Holdings fair value estimates, including one that suggests as much as 127% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Seagate Technology Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Seagate Technology Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Seagate Technology Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Seagate Technology Holdings?
Once you have formed a view on Seagate Technology Holdings, it can help to widen the lens and compare it with other potential opportunities using the Simply Wall St Screener. That way you can pressure test your thesis, line up alternatives and decide where new capital deserves the next dollar.
- If you want potential upside with stricter quality filters, scan a 19 high quality undiscovered gems that combine solid fundamentals with less crowded investor attention.
- For income focused goals, consider companies in the 6 dividend fortresses that pair higher yields with an emphasis on resilience.
- If capital preservation is front of mind, narrow your watchlist to a 32 resilient stocks with low risk scores where balance sheet strength and lower risk scores sit at the forefront.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com