
StoneCo (STNE) Stock Could Be Cheap Following Its 69% Five Year Fall
StoneCo has seen a sharp reset in sentiment, with the stock changing hands at US$8.09 after a steep pullback, which puts fresh focus on whether that price can be squared with the earnings the business is generating. With the political backdrop in Brazil again in the spotlight, the key issue for you is how much of the recent share-price slide is about headline risk and how much is about the underlying profit engine.
- Over the past 5 years the share price has fallen 69.2%, which puts real weight on the question of what level of earnings power the current valuation is actually reflecting.
- The sharp selloff that followed President Luiz Inácio Lula da Silva’s re-election in Brazil has pushed investors to rethink StoneCo’s potential profitability and capital needs in a policy environment where fiscal priorities and regulation could influence payment volumes, credit risk and returns on equity.
- There is a second opinion on StoneCo worth weighing. See what analysts think StoneCo's shares could be worth.
The issue now is whether today’s price for StoneCo is appropriately anchored to the earnings the business is producing and is expected to produce.
To put StoneCo’s reset into context and to see how other companies with compressed expectations are priced relative to their fundamentals, compare it with 26 high quality undervalued stocks
Is StoneCo a Bargain on Earnings?
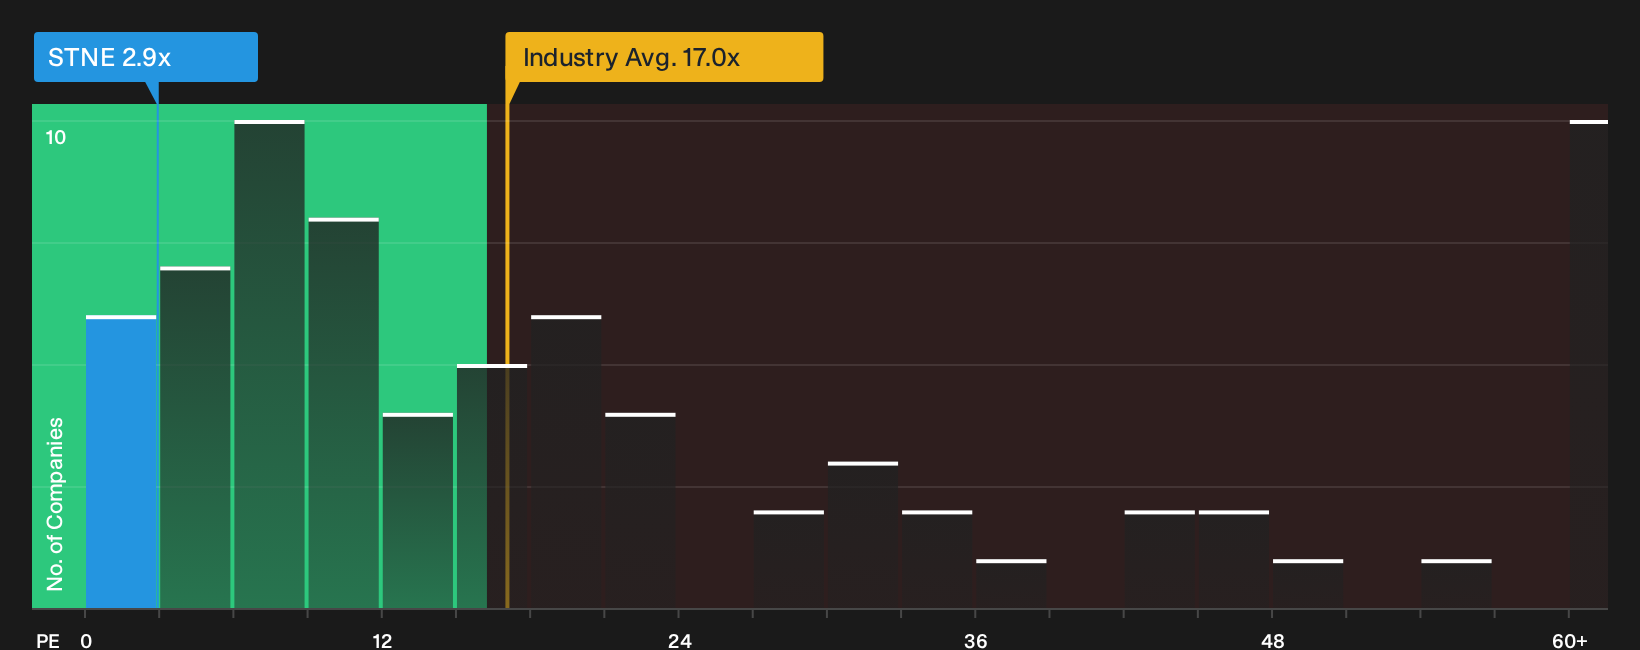
P/E fits StoneCo because earnings are a key driver for payment businesses that scale off transaction volumes and credit quality. On that yardstick, the stock trades on a P/E of 2.9x, against about 17.0x for the broader diversified financial industry and roughly 20.2x for peers. That is a steeply lower earnings multiple for StoneCo, given how similar companies are usually assessed on this metric.
Because the re-pricing after President Lula’s re-election has hit sentiment hard, the current discount to a tailored fair P/E multiple suggests the market is treating StoneCo as undervalued on earnings. For you as a holder or potential buyer, the key question is whether the risks around Brazilian policy, regulation and credit justify this kind of gap, or whether the present earnings base and forecast return on equity support a higher P/E over time. Explore the numbers behind StoneCo's P/E valuation.
The StoneCo Narrative: What Would Justify Today's Price?
StoneCo Narratives on Simply Wall St take the valuation puzzle a step further by spelling out which combinations of growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today’s price. Each scenario ties a fair value estimate to a clear storyline about StoneCo’s possible catalysts and risks, so you can track over time which version seems to be unfolding.
One of the top community narratives on StoneCo: roughly fairly valued
"The main thing that has to go right is that StoneCo turns its push to be a full bank for entrepreneurs and the rapid expansion of its higher risk credit portfolio into sustainable, well priced growth..."
Discover why this Narrative puts StoneCo at roughly fairly valued.
One more angle on StoneCo that could change how you see this valuation
Everything so far has focused on today’s earnings and risk, yet professional forecasts sketch out where StoneCo might be a few years from now and give you a different yardstick to compare with the current price. Explore where analysts expect StoneCo to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com