
What O'Reilly Automotive Stock Earnings Beat Means For Shareholders
- O'Reilly Automotive reported Q3 2026 sales of US$5.12b and net income of US$785.62m, with diluted EPS of US$0.97 that topped Wall Street expectations and reflected stronger comparable store sales across both professional and DIY customers.
- The retailer lifted full year 2026 guidance for sales, comparable store performance, gross margin and operating profit, signaling confidence in its store expansion program, sourcing model and mix of higher volume professional business, alongside tariff refund benefits.
- We will now look at how O'Reilly Automotive's stronger comparable sales and raised full year guidance could reshape its investment narrative.
O'Reilly Automotive Investment Narrative Recap
To be comfortable owning O'Reilly Automotive, you need to believe the chain can keep turning its scale in inventory, distribution and private label into steady market share gains without giving up its 51.5% to 52% gross margin ambition. The Q3 beat and higher 2026 guidance support that thesis near term, since stronger comparable sales and tariff refunds ease some pressure on product costs.
The key near term swing factor is execution on professional do it for me growth and rapid store openings while carrying higher leverage and negative equity. If sales or cash generation soften against that debt load, balance sheet flexibility and buyback capacity could tighten, which remains the main operational risk.
The most relevant update for that thesis is the record Q3 2026 performance, with US$5.12b in revenue, US$785.62m in net income and diluted EPS of US$0.97, alongside a raised full year outlook for sales, comparable store growth, gross margin and operating profit. That result lines up with the existing catalyst view that distribution strength, professional customer mix and private label can support earnings power.
Q3 also sits alongside heavy investment plans such as US$1.3b to US$1.4b of 2026 capex and an ongoing store buildout target of 225 to 235 net new locations for the year. Those projects, combined with the proposed roughly US$10b all cash bid for the NAPA unit and a leverage goal of 2.5x, keep execution risk and funding discipline firmly in focus despite the recent operating outperformance.
O'Reilly Automotive Forecasts That Underpin The Current Valuation Debate
Analysts are effectively sketching a medium term roadmap for O'Reilly Automotive that assumes steady growth in both sales and profit, then using that picture to judge whether today's share price makes sense. The forecast calls for revenue to expand by 6.1% each year over the next three years, with profit margins expected to edge up from 14.3% today to 14.5% by 2029, which frames how much earnings power the business might be able to support by the end of the decade.
On those assumptions, earnings are projected to reach US$3.2b by 2029, up from US$2.7b today, with analysts broadly aligned on that end point and an implied earnings per share of US$4.21 as share count drifts lower at an expected 4.16% annual decline. That backdrop feeds into the P/E expectations, since the stock would need to trade at about 30.4x those projected profits versus roughly 25.9x today and above the current 15.9x for the wider US specialty retail group. This leaves investors to judge whether the Q3 execution and store rollout justify a premium multiple.
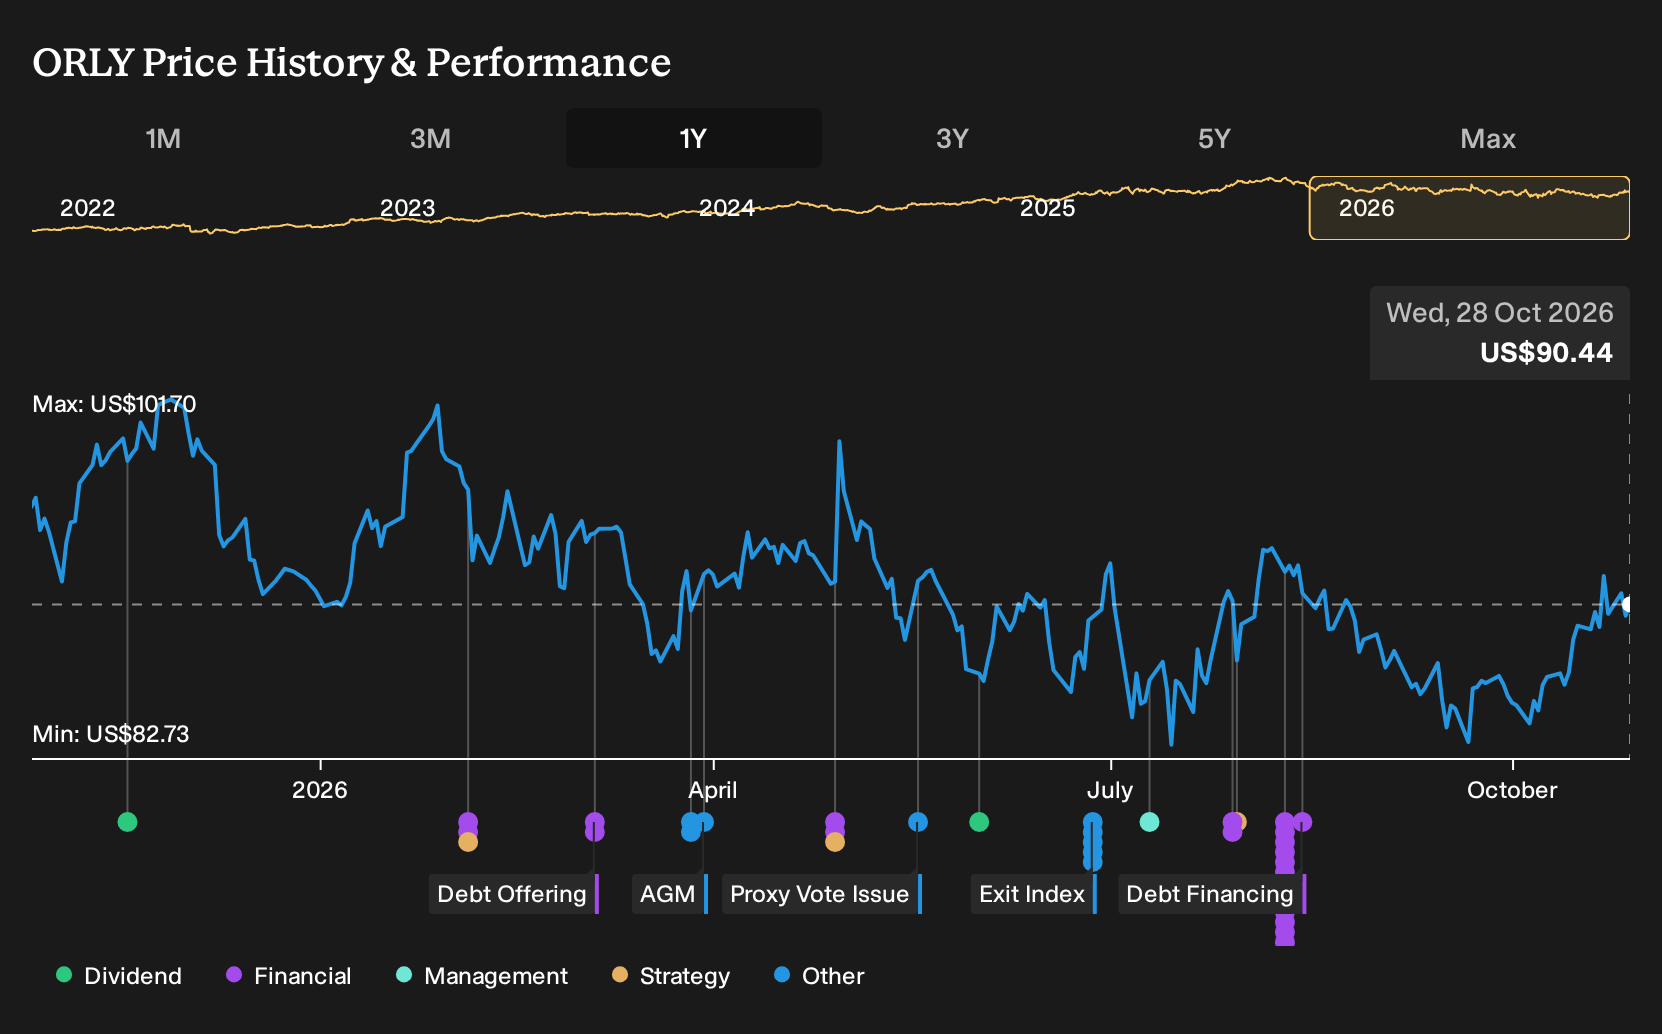
On the top line, the same framework ties O'Reilly Automotive to a 2029 revenue marker of US$22.2b, paired with the US$3.2b earnings figure and an 8.5% discount rate that many analysts are using as a hurdle to translate those future cash flows back into today's fair value estimates. Those numbers underpin the consensus price target of US$107.80, which sits 21.4% above the recent US$84.71 share price. However, the range between the US$89 bear case and US$120 bull case shows that conviction levels differ across the street.
One extra layer is the sensitivity to buybacks and leverage, since the forecast assumes shrinking share count and a higher P/E multiple, which both lean on continued access to funding and consistent cash generation. If execution around the proposed roughly US$10b NAPA acquisition, the 2.5x leverage goal or the US$1.3b to US$1.4b capex plan diverges from expectations, the path to those 2029 earnings and valuation markers could look very different than the consensus sketch.
O'Reilly Automotive's current analyst blueprint points to forecast revenue of US$22.2b and earnings of US$3.2b by 2029, which rests on 6.1% yearly revenue growth and an earnings increase of about US$500m from the current US$2.7b base.
Uncover why O'Reilly Automotive's fair value indicates a 19% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For a very different angle, consider the risk that O'Reilly Automotive relies too heavily on debt-funded expansion. The lowest analysts were penciling in only about 5.5% yearly revenue growth to roughly US$21.8b and earnings of around US$3.1b by 2029. Those forecasts, set before this Q3 beat, show how cautious some views remain and invite you to compare several narratives as new results roll in.
Explore 4 other O'Reilly Automotive fair value estimates, including one that suggests as much as 21% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your O'Reilly Automotive research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for O'Reilly Automotive. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate O'Reilly Automotive's overall financial health at a glance.
Looking For More Investment Ideas Beyond O'Reilly Automotive?
If the O'Reilly Automotive story has sharpened your thinking about quality, balance sheet strength and earnings power, it can be useful to compare it with other businesses that share some of those traits. The Simply Wall St Screener gives you a way to move from one stock to a wider watchlist built around the factors that matter most to you.
- Prefer to focus on financial resilience and staying power first? Start with a 32 resilient stocks with low risk scores that concentrates on companies with sturdier risk profiles.
- Hunting for quality at a price that still looks reasonable? Use the 26 high quality undervalued stocks to see which businesses combine solid fundamentals with more modest expectations baked into the share price.
- Interested in income and cash returns as part of your plan? Filter for payout strength using the 6 dividend fortresses and see which stocks offer higher yields backed by robust balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com