
Learn Why The Bull Case For Wacker Chemie Stock Could Change Following Return To Profit
- Wacker Chemie reported third quarter 2026 sales of €1,465.7 million and net income of €83.6 million, with nine month revenue of €4,388.9 million and profit of €434.8 million, compared with losses in the prior year periods.
- The shift from prior losses to profit indicates that Wacker Chemie’s cost base and product mix are currently supporting positive earnings across the group.
- We will now assess how Wacker Chemie’s return to profitability could reshape the investment narrative built around cost savings and mix.
Scan how Wacker Chemie’s earnings rebound compares with other cash generative industrials by reviewing our hand picked list of solid balance sheet and fundamentals (207 results) that is aligned with similar financial resilience themes.
Wacker Chemie Investment Narrative Recap
To own Wacker Chemie, you need to believe the shift toward specialty silicones and semiconductor polysilicon, plus cost programs like PACE, can keep earnings supported even when construction and solar exposed demand is soft. The latest quarter’s profit suggests the cost base is currently working. In the near term, the main swing factor still appears to be how fully existing capacities are utilized.
The biggest operational risk remains that demand in construction and solar stays weak and keeps plant loading below what cost measures require. The Q3 rebound does not remove that risk. It simply gives management more room to push savings and mix improvements while Biosolutions and solar exposed activities remain a drag.
The fresh Q3 and nine month figures matter because they put real numbers behind Wacker Chemie’s cost savings and mix story. Sales of €1,465.7 million and net income of €83.6 million for the quarter, plus €4,388.9 million revenue and €434.8 million profit year to date, indicate that the group is now earning money again.
This return to profit intersects directly with the catalysts investors have been watching, especially the PACE program and the refocus toward semiconductor grade polysilicon. The current figures provide a reference point to judge whether future quarters continue to support that shift or whether weak construction, solar, or slower Biosolutions ramp up again put pressure on margins.
Wacker Chemie's narrative projects €6.0 billion revenue and €255.7 million earnings by 2029. This assumes 3.0% yearly revenue growth and an earnings swing of about €693.5 million from current earnings of a €437.8 million loss to the 2029 consensus figure.
Uncover how Wacker Chemie's fair value indicates a 7% potential upside to its current price that may not last much longer.
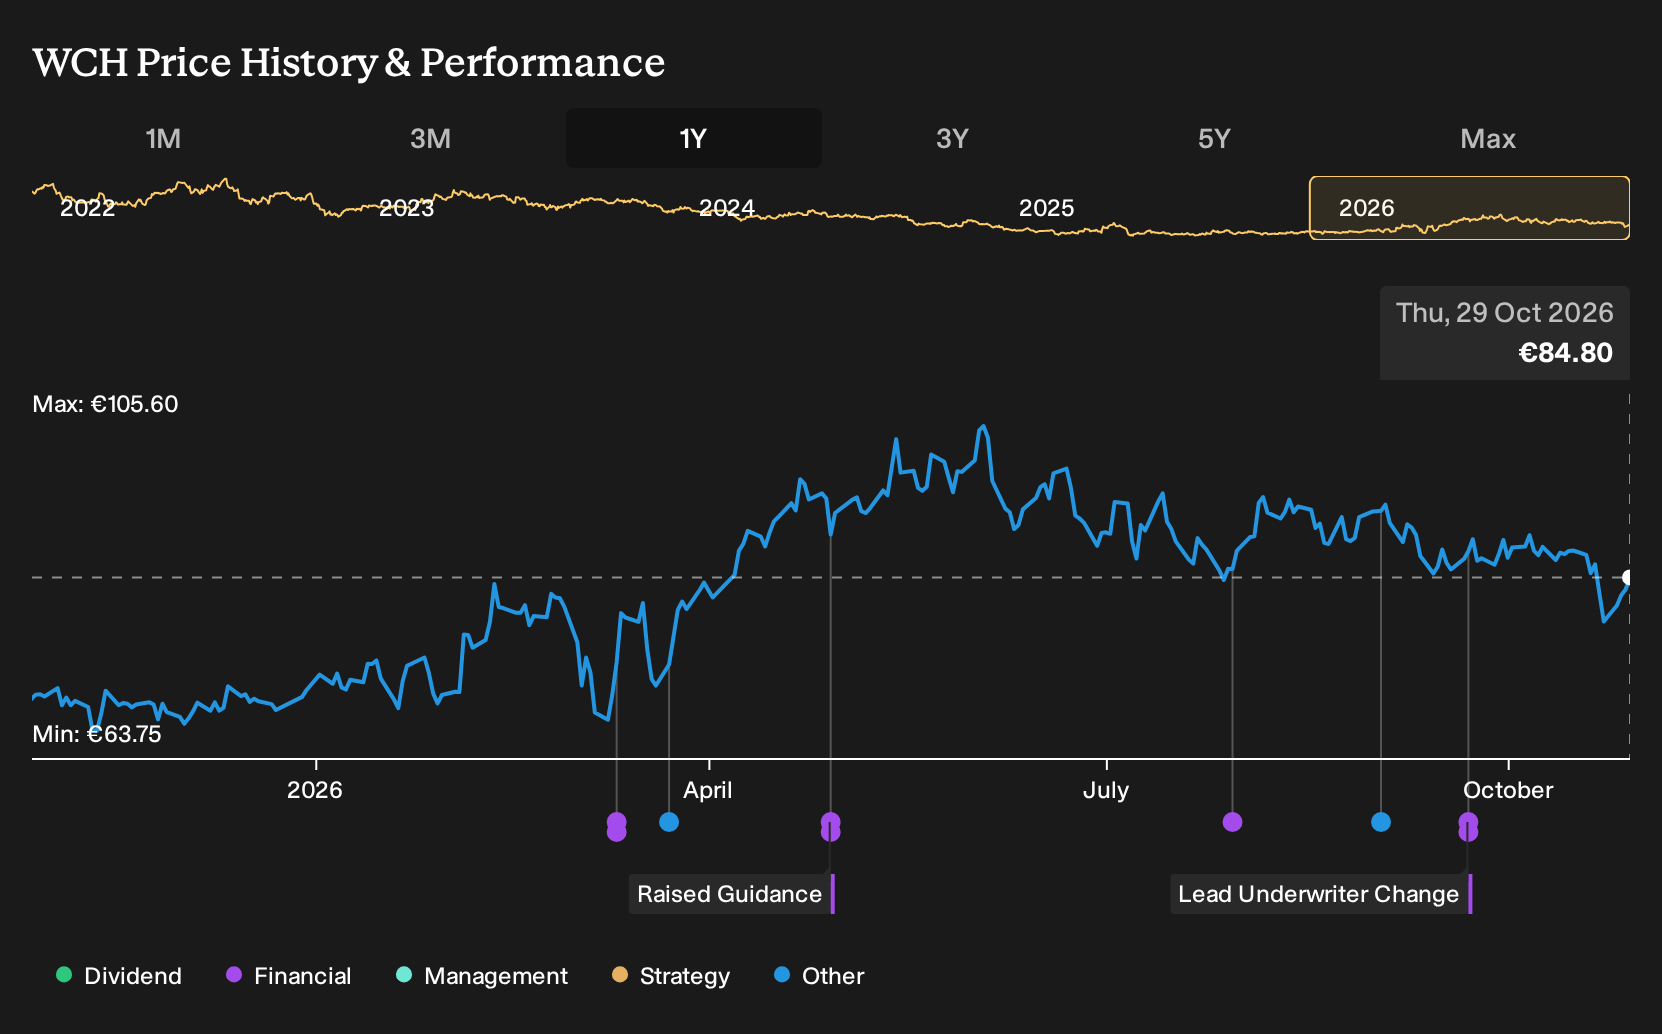
Exploring Other Perspectives
One alternate view around Wacker Chemie puts far more weight on the PACE cost program as a catalyst. Some analysts were already working with revenue reaching €6.7b and earnings of €411.3 million by 2029 before this Q3 report. You can treat this earnings rebound as a fresh reason to compare these assumptions with your own and explore how opinions might shift from here.
Explore 3 other Wacker Chemie fair value estimates, including one that suggests up to 323% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Wacker Chemie research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Wacker Chemie. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wacker Chemie's overall financial health at a glance.
Looking for more investment ideas beyond Wacker Chemie?
If the Wacker Chemie story has sharpened your thinking about balance sheets, earnings quality, and resilience through cycles, it can help to widen the lens and compare it with other listed businesses that share similar financial traits.
- For investors who want potential mispricings with solid fundamentals at their back, review our hand picked 191 high quality undervalued stocks that screens for financially robust companies trading below their estimated worth.
- If income stability is a priority, consider using our curated 228 dividend fortresses to focus on companies pairing higher yields with balance sheets that look built to support ongoing payouts.
- When capital preservation matters just as much as upside potential, filter the market using our 229 resilient stocks with low risk scores to zero in on businesses with more resilient financial risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com