
AIA Group (SEHK:1299) Names New Regional Chief, Is It A Bargain Or Fully Priced?
AIA Group (SEHK:1299) has reshuffled its leadership, appointing former HSBC insurance executive Edward Moncreiffe as regional chief executive for key markets including Australia, New Zealand, India, and Sri Lanka, effective 2 November 2026.
AIA Group shares trade at HK$71.65 after a 1 day share price return of 1.06%. However, the stock is still down 13.99% on a year to date share price basis, while a 1 year total shareholder return of 0.28% and 3 year total shareholder return of 13.52% point to a longer track record that investors now weigh against this leadership reshuffle.
Scan how AIA Group compares with other insurers reshaping leadership across Asia Pacific by reviewing our hand picked list of solid balance sheet and fundamentals (206 results)
AIA Group now sits at a crossroads, with a fresh regional leader in place and a share price that has lagged this year. Do you treat this as an early entry, or keep waiting for a cleaner setup on value?
Most Popular Narrative: 30.5% Undervalued
AIA Group's most followed thesis anchors fair value at HK$103.03 against the last close of HK$71.65. The current leadership change lands on top of an already wide gap that hinges on execution across Asia.
The ongoing expansion of AIA Group across Mainland China, Hong Kong, ASEAN and India, with record group value of new business of US$3.2b in the first half of 2026 and broad based growth across most regions, is contributing to the compounding of revenue and new business value as these multiple engines are built out.
See why 25 investors see AIA Group as 30% undervalued.
Result: Fair Value of HK$103.03 (UNDERVALUED)
Still, this AIA Group narrative depends heavily on broad based VONB and OPAT growth across key Asian markets, as well as on investor willingness to support a higher future P/E multiple.
Find out about the key risks to this AIA Group narrative.
Another View: What AIA Group’s P/E Is Telling You
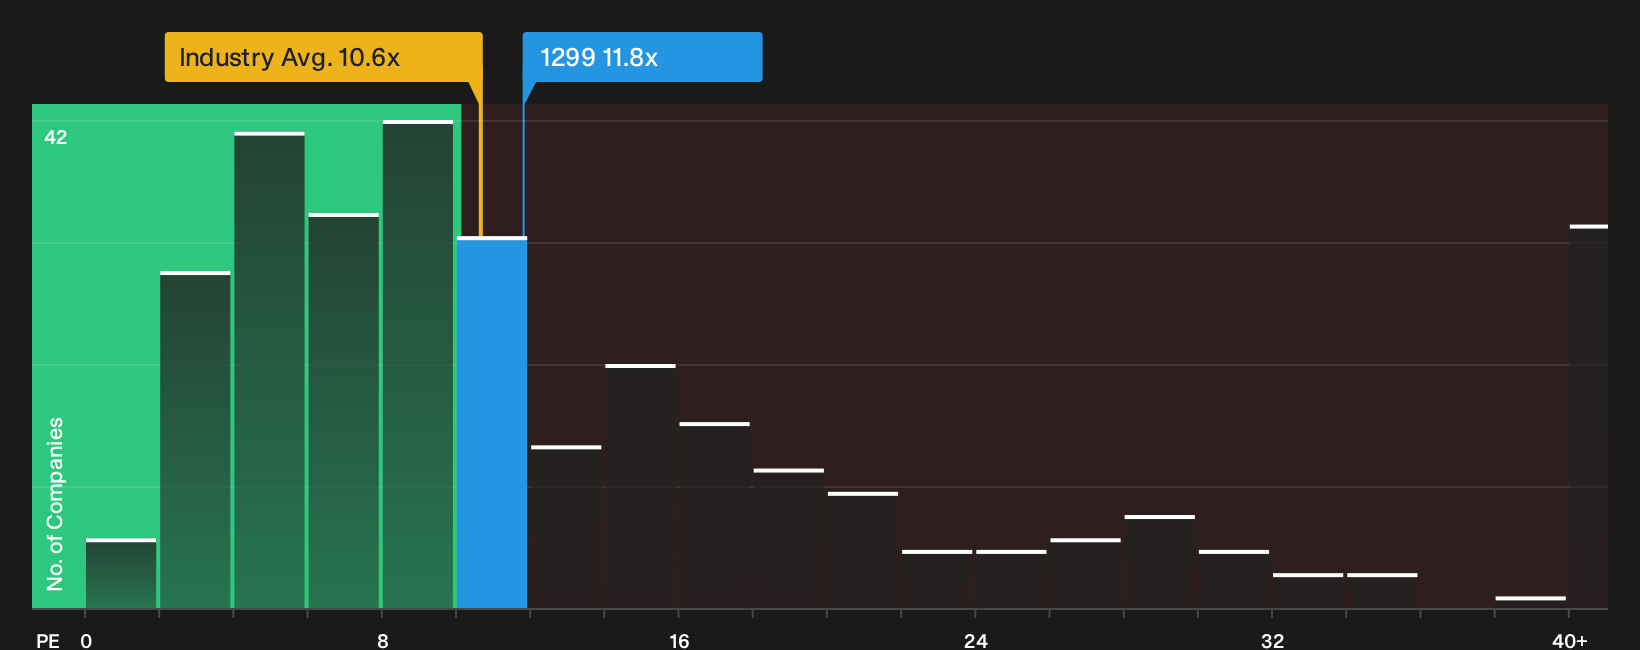
A second lens on AIA Group uses its current P/E of 11.8x. That level is higher than both the Asian insurance group average at 10.6x and the estimated fair ratio of 6.5x, which signals investors are paying up and leaves less room if sentiment cools from here.
If you rely more on this earnings multiple than on optimistic fair value estimates, the question becomes simple. Are you comfortable owning AIA Group on a richer P/E while waiting for the growth story to keep justifying that gap, or do you prefer to hold out for pricing closer to the fair ratio investors could eventually move toward?
For a closer look at how these earnings multiples stack up against peers, and what that means for valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Confident about AIA Group after this, or still on the fence as the leadership change beds in and valuation debates continue? If you want to understand what optimists are focusing on, review the 4 key rewards
Looking for more investment ideas beyond AIA Group?
If AIA Group has sharpened your focus on quality, do not stop here. Broaden your opportunity set with a few targeted stock ideas tailored to different goals.
- Target resilient compounding potential by scanning a 193 high quality undervalued stocks that filters for quality businesses priced below what their fundamentals might justify.
- Strengthen your income stream by reviewing 228 dividend fortresses that highlight companies combining higher yields with a focus on sustainability.
- Dial down portfolio stress by assessing 228 resilient stocks with low risk scores designed for investors who want steadier balance sheets and fewer unpleasant surprises.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com