
Earnings And Dividend Raise Could Be A Game Changer For Artisan Partners Stock
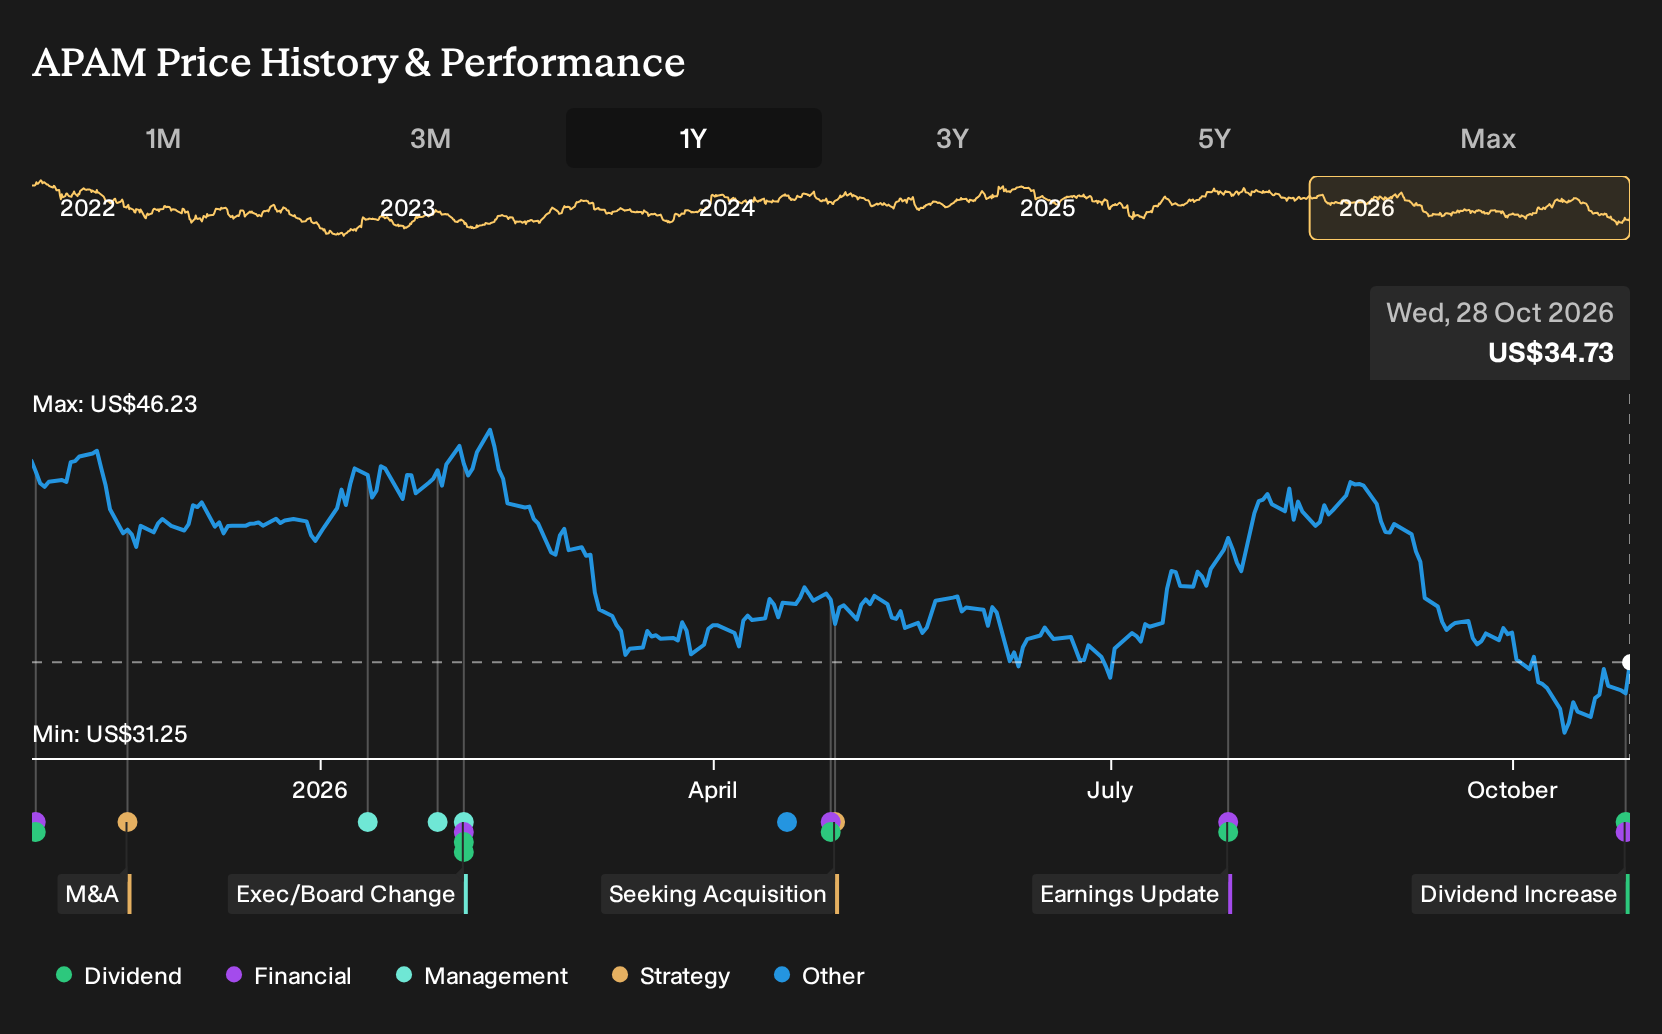
- Artisan Partners Asset Management reported third quarter 2026 revenue of US$312.5 million and net income of US$75.2 million, along with a 10% higher quarterly dividend of US$0.88 per share that covered roughly 80% of cash generated.
- The asset manager absorbed US$10.6b of net client outflows tied to value equity changes, while also highlighting ongoing positive flows in credit and alternatives, as well as plans for ETF share classes and an interval fund.
- We will look at how Artisan Partners Asset Management's investment narrative is affected by higher earnings together with a larger variable dividend.
Artisan Partners Asset Management Investment Narrative Recap
To own Artisan Partners Asset Management, you need to believe its credit and alternatives engine can offset ongoing pressure in traditional equity mandates and the wind down of the U.S. Value team. The third quarter print, with higher revenue and earnings year on year, supports that the franchise is still producing healthy profits while absorbing change.
The key short term swing factor is whether equity outflows tied to value strategies stabilize while newer offerings keep attracting assets. The biggest risk remains persistent firm wide outflows that undercut fee revenue faster than newer products scale. The latest results do not remove that risk, but they do not worsen it either.
The board’s decision to declare a variable quarterly dividend of US$0.88 per share, equal to about 80% of cash generated in the September quarter, matters for how you think about Artisan Partners Asset Management as a cash return story. A high payout model can appeal if you want income, but it tightens the margin for error if flows weaken or expenses rise.
This dividend move also interacts with the main catalyst. The key question is whether expansion in credit, alternatives and new vehicles such as future ETF share classes and a planned interval fund can scale without eroding margins. Sustaining a rich distribution while funding product build out, technology and distribution spend will test execution, especially with sector wide fee pressure and the risk of further equity mandate losses.
Artisan Partners Asset Management's current earnings sit at US$274.9 million, and analysts expect earnings to reach US$283.3 million by 2029. That implies an earnings increase of about US$8.4 million based on flat forecast revenue and a projected revenue base of US$1.2b by 2029.
Uncover how Artisan Partners Asset Management's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the lowest analysts put much more weight on the risk that equity outflows and client reallocations keep Artisan Partners Asset Management on a flat track. They were pencilling in roughly US$1.2b of revenue and about US$284.7 million of earnings by 2029 before this earnings beat and dividend lift, so treat their cautious stance as one more lens to compare with your own view as fresh data becomes available.
Explore 4 other Artisan Partners Asset Management fair value estimates, including one that suggests as much as 15% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Artisan Partners Asset Management research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Artisan Partners Asset Management. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Artisan Partners Asset Management's overall financial health at a glance.
Looking for more investment ideas beyond Artisan Partners Asset Management?
Once you have a view on Artisan Partners Asset Management, it can help to line it up against other opportunities that match your preferred mix of quality, risk, and income. The Simply Wall St Screener lets you filter for that combination rather than sifting through tickers one by one.
- If capital preservation and steadier price swings matter most to you, start with a set of 31 resilient stocks with low risk scores that score well on resilience and risk controls.
- For investors who care about strong balance sheets and fundamentals before anything else, focus on a list of solid balance sheet and fundamentals (23 results) that can shoulder tougher conditions without resorting to dilutive capital raises.
- If you are hunting for underfollowed opportunities, widen your watchlist with a 18 high quality undiscovered gems that pair solid financials with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com