
How Investors Are Reacting To ICON (ICLR) Record Contract Wins
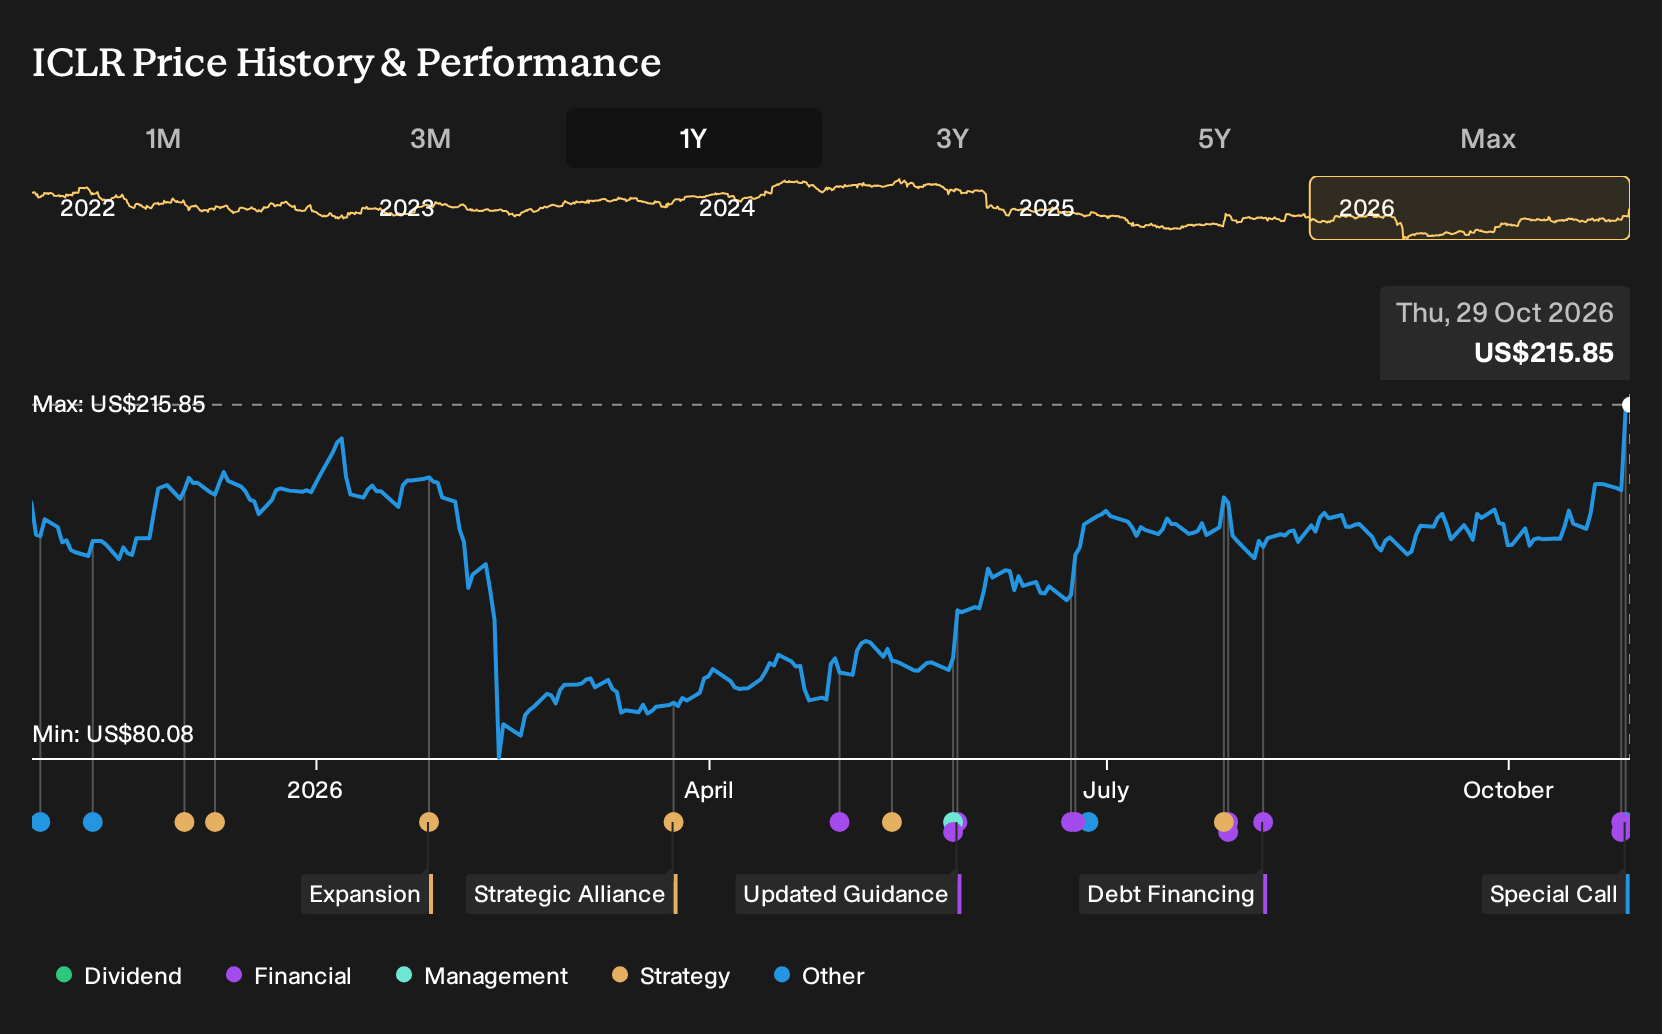
- ICON reported Q3 2026 earnings with basic EPS from continuing operations of US$1.59, compared to a basic loss per share of US$3.67 a year earlier. The company tightened full year guidance to US$8.1b to US$8.2b in revenue and highlighted record net business wins of US$3.15b with an adjusted EBITDA margin of 16.6%.
- The firm paired stronger profitability and a larger backlog of US$24.5b with US$400m of share repurchases and a fresh US$750m buyback authorization, underscoring how operational execution and capital allocation are being used together to support ICON's long term earnings profile.
- Next, the focus shifts to how ICON's investment narrative is affected by record net business wins alongside raised full year guidance.
ICON Investment Narrative Recap
To own ICON, you need to believe record net business wins and a US$24.5b backlog can translate into healthier direct fee revenue and a rebuilding of margins after a period of mix pressure and accounting noise. The big near term swing factor is execution, as those wins move from awards into active projects without eroding profitability.
The most immediate risk is that compressed adjusted EBITDA margins and weaker recent net profit margins linger, while governance concerns from past control issues stay in investors’ minds. This quarter’s higher EPS, improved adjusted EBITDA margin of 16.6% and tighter 2026 guidance help but do not fully remove that overhang.
The single update that matters most here is ICON’s confirmation of 2026 guidance, alongside record Q3 net business wins of US$3.15b and a book to bill of 1.56x. Taken together, this indicates that the commercial engine is securing work while management still sees a path to US$8.1b to US$8.2b of annual revenue.
For catalysts, investors are watching how that backlog and four consecutive quarters above a 1.3x book to bill translate into direct fee growth and steadier margins through 2027. The guidance, together with ongoing AI tools, lab expansion and buyback capacity, outlines the potential upside, while any stumble in converting these awards into profitable delivery remains the key operational risk.
ICON's narrative projects US$9.1b revenue and US$716.2m earnings by 2029. This assumes 3.3% yearly revenue growth and an earnings increase of about 26x from US$27.0m today.
Uncover how ICON's fair value indicates a 13% potential downside to its current price, suggesting that the current premium may not be sustainable.
Exploring Other Perspectives
Some of the lowest ICON analysts leaned hard into margin risk. Before this earnings beat, they were working off expectations that revenue would reach about US$8.9b by 2029 with earnings of roughly US$500.3m, far below the US$716.2m consensus view. That gap shows how sharply opinions differ and why you may want to compare several narratives that could shift after this quarter.
Explore 5 other ICON fair value estimates, including one that suggests as much as 26% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ICON research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ICON. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ICON's overall financial health at a glance.
Looking For More Investment Ideas Beyond ICON?
If ICON's story has sharpened your thinking about earnings quality, backlogs and capital returns, it can be useful to scan for other businesses with traits that line up with your own checklist. The Simply Wall St Screener lets you move from one stock to a full watchlist in a few clicks, filtered by risk, balance sheet strength or potential value gaps.
- For investors hunting for income streams that aim to be both sizeable and resilient, start with a set of 6 dividend fortresses that can anchor a dividend focused watchlist.
- If capital preservation sits high on your priority list, narrow the universe to 31 resilient stocks with low risk scores that score well on resilience and measured volatility.
- When you want to focus on quality fundamentals without chasing well covered large caps, filter for 18 high quality undiscovered gems that may not yet be on every analyst's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com