
NRC Health (NRC) Q3 Earnings Back AI Progress As Margin Questions Persist
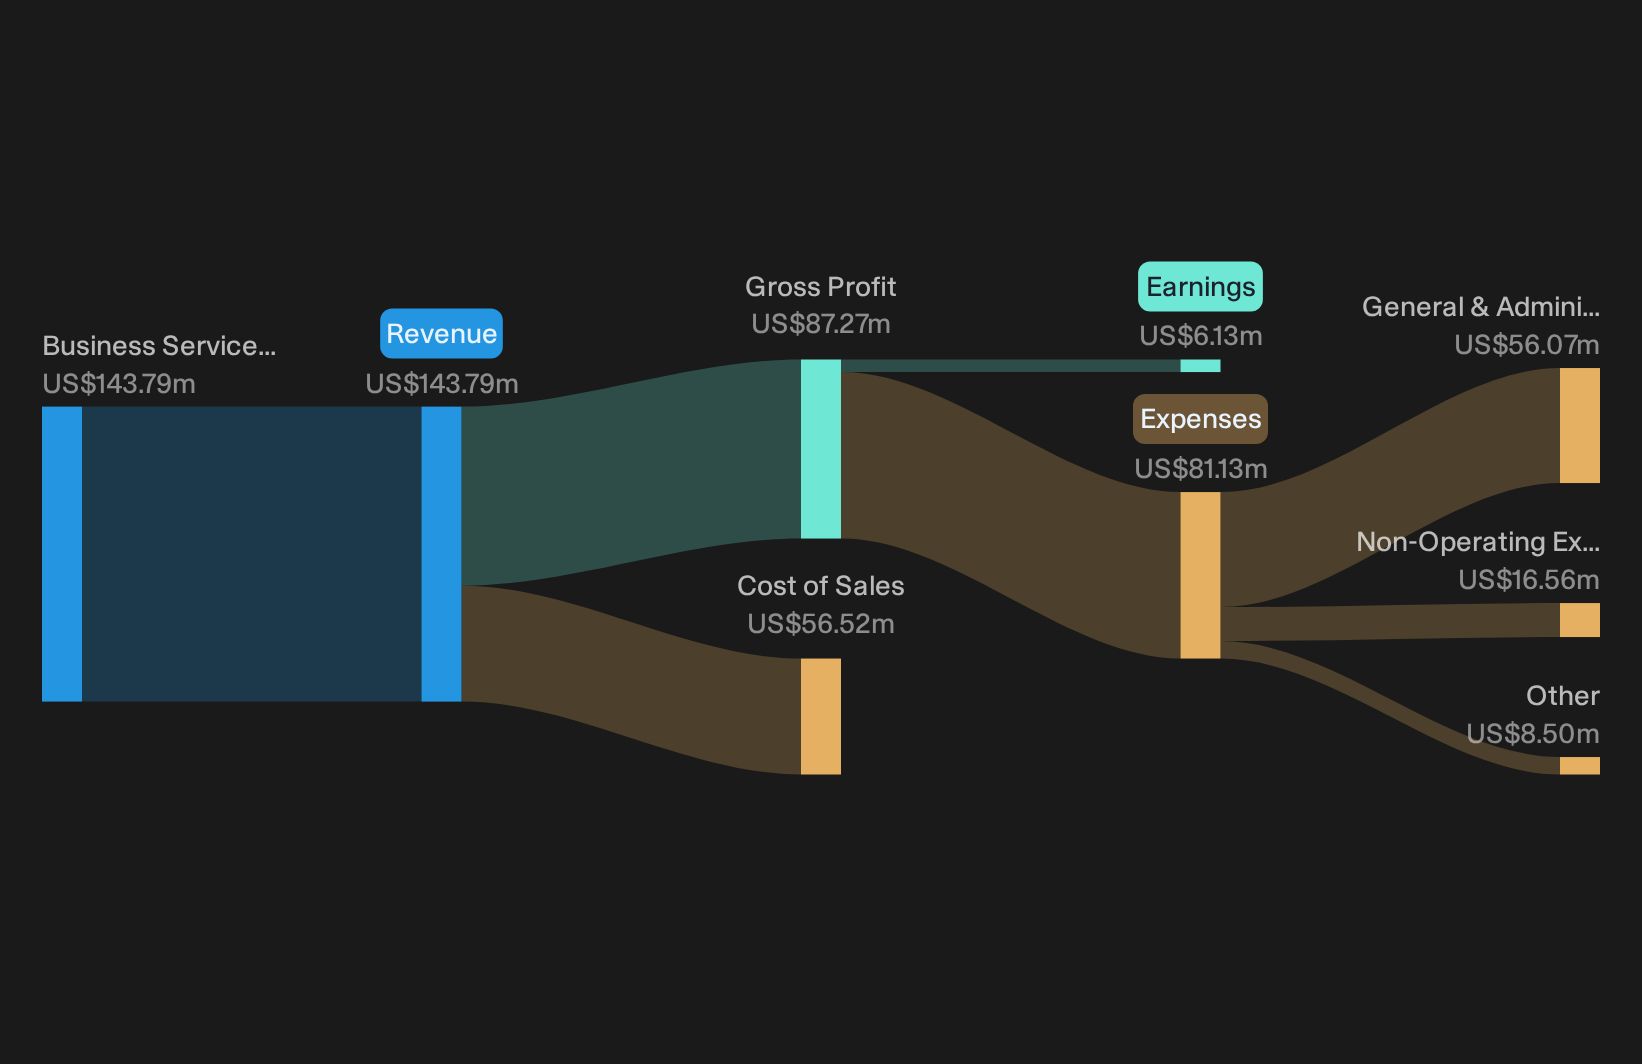
NRC Health came into this Q3 2026 report with the stock already grinding higher over the past three months, yet the immediate reaction has been muted. The share price barely moved, up just 0.09% to US$23.49, even as the company put up US$38.4 million of revenue and US$4.7 million of net income. For a business often pigeonholed as a slow, utility-like data provider to hospitals, this quarter’s combination of top line progress and cleaner profitability tells a sharper story than the flat tape suggests.
Love the cleaner NRC Health profitability but unsure whether this slow grind in the share price suits your style? Compare it with a curated screener of financially stronger, lower risk opportunities in our 30 resilient stocks with low risk scores.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$38.4 million vs. US$34.6 million (up about 11%).
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): US$4.7 million vs. US$4.0 million (up about 18%).
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.22 vs. US$0.18 (higher earnings per share year on year).
- Adjusted EBITDA Margin (Q3 2026 vs. Q3 2025): 28% vs. about 31% (profitability margin lower after the timing impact of the HUB conference).
Margins and free cash flow both jumped as TRCV converted into revenue. Ask Charlie what turned NRC Health’s contract growth into cash.
NRC Health’s AI Ambition Meets Early Revenue Proof
The bullish story hangs on NRC Health turning richer feedback tools and AI into deeper customer embed, not just more surveys.
"Wider adoption of value-based care models increases demand for tools that link patient feedback to outcomes and cost savings. NRC Health highlights this through service recovery and ambient AI rounding, potentially supporting pricing power and net margins as customers see operational benefits."
Q3 shows partial validation. Revenue and TRCV both rose, and broad based gains across Experience, Market Insights and Governance suggest customers are buying into workflow tools. Early Huey AI pilots and the launch of nQuire Pro point to execution on the product vision, although adjusted EBITDA margin compression and HUB timing noise mean any pricing power or cost benefits are not yet clearly visible in profitability.
Testing NRC Health’s Margin And Execution Fears
On the flip side, the concern is that cost growth and complex rollouts mute earnings progress even when contracts expand.
"Expanding delivery, customer success and product capabilities, alongside higher corporate expenses and share based compensation, may keep adjusted EBITDA margin closer to current levels for longer than investors expect, which could limit near term earnings progress even if TRCV continues to rise."
Q3 offers some support for that caution. Adjusted EBITDA margin landed at 28%, about 3 points lower than a year ago, even with 9% TRCV growth and a full quarter from the largest implementation. Management flagged HUB conference timing that reduced margin and noted the next phase of the big deal will be smaller, so cost absorption is working but not yet translating into clear operating leverage.
One Narrative disagrees with today's price. → See where this Narrative says NRC Health should trade.
Hunt Quiet Balance Sheet Upside
NRC Health shows that cleaner earnings can still leave a share price volatile. The real opportunity is hunting stocks that could be low debt before markets close that gap.
- Company 1 - 23% below our estimate - builds cloud and workplace tools enterprises adopt as AI workloads scale.
- Company 2 - 43% below our estimate - converts data center and modular build backlogs into higher value service work.
- Company 3 - 36% below our estimate - wins subsea contracts that shorten brownfield tieback timelines and secure long duration services.
Three companies from the same screener. Open the full list of 22 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com