
Rush Enterprises (RUSH.A) Stock Can Q3 Earnings Keep Margins In Focus
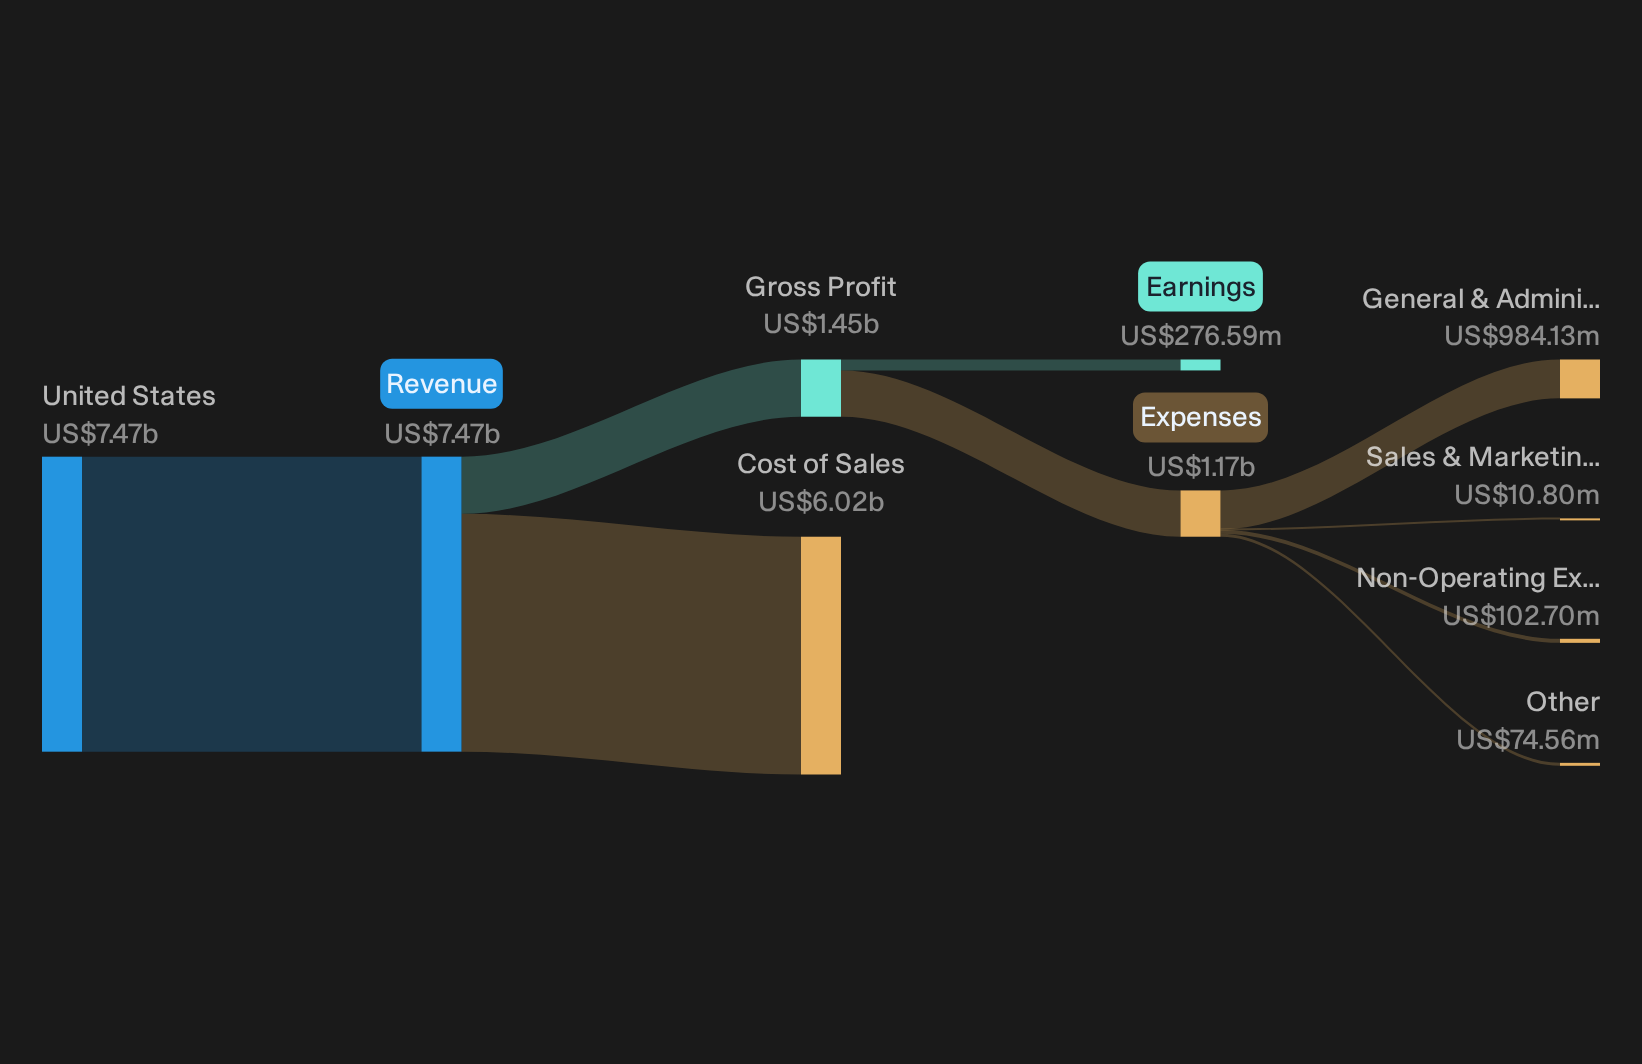
Rush Enterprises entered its Q3 2026 report with a weak recent chart and a relatively low-looking P/E, after the share price declined over the past week, month and quarter. Then traders reversed course. The stock rose 4.4% today as the trucking dealer reported about US$2.1b in revenue and roughly US$0.65 in earnings per share.
The main focus is margin and profit strength. Net income of about US$78m now has investors considering whether today’s move simply aligned with the company’s fundamentals or moved ahead of them based on sentiment.
Impressed by Rush Enterprises posting about US$2.1b in sales with solid earnings per share but unsure if the margin story justifies the move in the chart? Compare this setup with companies screened for stronger balance sheets and fundamentals in our list of solid balance sheet and fundamentals stocks (22 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$2,113.1m vs. US$1,880.8m (+12.4%)
- Net Income (Q3 2026 vs. Q3 2025): US$78.0m vs. US$66.7m (+17.0%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.67 vs. US$0.57 (+17.4%)
- Aftermarket Revenue (Q3 2026 vs. Q3 2025): US$680m vs. approximately US$643m (+5.8%), contributing about 63% of total gross profit in Q3 2026
Earnings give you the headline, but investors who care about what they are paying for Rush Enterprises often anchor on the cash that actually comes through the business. Those cash flows tell a different part of the story, and on that basis the stock could be a clear 23% undervalued.
Rush Enterprises aftermarket thesis meets an early checkpoint
Bulls argue Rush Enterprises can lean on recurring service activity while newer acquisitions mature.
"Analysts expect Rush Enterprises to keep using its high-margin aftermarket and leasing operations to provide relatively stable gross profit and earnings contributions through the truck cycle."
Aftermarket revenue of roughly US$680m supplied about 63% of total gross profit, which fits the idea of a cushioning profit base. Leasing and rental income rose, supported by better utilization and contract maintenance growth. Q3 net income of about US$78m and EPS near US$0.65 suggest the service heavy mix is currently offsetting freight and order timing noise rather than amplifying it.
Rush Enterprises execution risk still on the table
The key worry is whether a larger network and refrigeration JV actually convert into durable earnings power.
"The main thing that has to go right is that Rush Enterprises continues to grow and integrate its expanded dealership and refrigerated transport footprint so that aftermarket, leasing and new vehicle sales all benefit from the larger network."
Q3 shows progress, not proof. Class 8 and medium duty unit sales both rose while aftermarket activity delivered record shop gross profit per day. The new refrigerated transport joint venture closed and is contributing to an enlarged platform. Yet the recent multi quarter share price decline and still cautious order intake around EPA 2027 rules indicate investors remain unconvinced that these moves already translate into structurally stronger earnings.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Hunt Quiet Balance Sheet Winners
Rush Enterprises just showed how a single quarter can shift sentiment on earnings and balance sheet strength. The real opportunity is finding solid operators that could be low debt before the market closes the gap.
- Company 1 - 43% below our estimate - converts a record project backlog in data center and modular builds into higher value mechanical and monitoring work.
- Company 2 - 36% below our estimate - wins subsea projects by pairing faster brownfield tiebacks with longer duration services built on a capital light model.
- Company 3 - 32% below our estimate - sells AI chips and software that data center operators adopt as workloads strain existing power and compute limits.
Those are three of them. See every one of the 22 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com