
Earnings Upgrade Might Change The Case For Investing In Aviva Shares
- Morgan Stanley upgraded Aviva to overweight, highlighting UK and Ireland general insurance, where past motor pricing decisions are feeding into stronger personal insurance margins and a potential beat versus current operating profit expectations.
- The focus on improving UK personal insurance profitability ties directly into Aviva’s broader push toward capital-light, fee-driven activities in wealth and protection, which can reshape the mix of earnings quality over time.
- We will now see how Aviva’s investment narrative could be influenced by Morgan Stanley’s focus on improving UK personal insurance margins.
Scan how insurers like Aviva are repositioning around capital-light, fee-based earnings and compare that shift with our curated list of solid balance sheet and fundamentals (10 results).
Aviva Investment Narrative Recap
Owning Aviva means buying into a story where stronger UK and Ireland personal lines, a growing wealth arm and capital light products gradually carry more of the earnings load. The short term hinge point is simple: you want clearer evidence that personal insurance margins are holding up while group profitability improves from a low net margin base.
The biggest operational risk sits in execution and pricing. Integration work, inflation in claims costs and pressure on UK and Canadian personal lines pricing can still squeeze returns if not matched by underwriting discipline. The recent focus on better UK motor and home margins does not remove that risk; it just shows where management is pushing hardest.
The recent analyst and shareholder calls around Aviva’s Wealth business tie directly into this. Wealth, pensions and fee based products rely less on balance sheet risk than traditional life or annuities, so growth here can help offset any future pressure in general insurance earnings and support the capital light tilt the group is targeting.
That makes the wealth discussion relevant to near term catalysts. Clearer disclosure on flows, fee margins and capital usage in Wealth can influence how investors weigh Aviva’s exposure to mature UK insurance lines against its longer term opportunity in retirement and workplace savings. It also feeds into how sustainable current dividend expectations look, given commentary that the payout is not well covered by earnings.
Aviva's current analyst narrative points to £45.4b revenue and £1.9b earnings by 2029, based on 16.5% yearly revenue growth and an earnings increase of about £1.1b from the £767.0m level reported today.
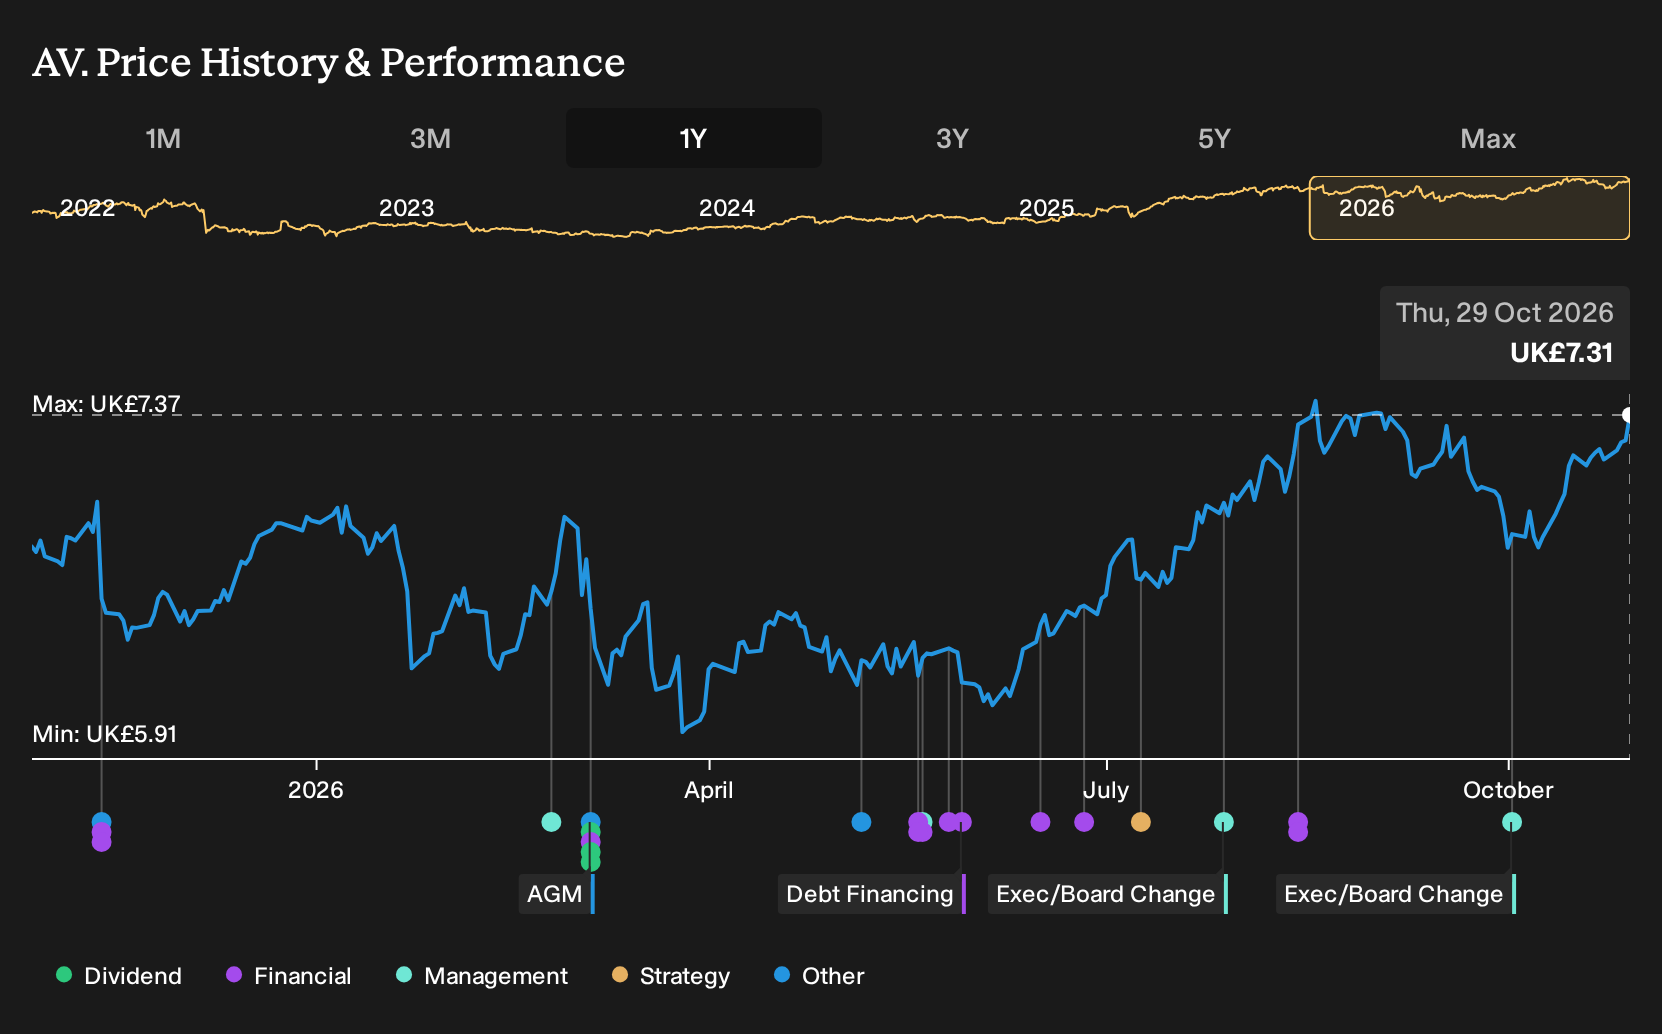
Uncover why Aviva's fair value indicates a 5% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
Seven fair value estimates from the Simply Wall St Community span roughly £6.93 to £13.09, with views clustering across the £7 to £12.50 range. That spread already shows how far opinions on Aviva can differ. Set it against upcoming Wealth calls and UK insurance pricing risks, then weigh several contrasting viewpoints before deciding your own stance.
Explore 6 other Aviva fair value estimates, including one that suggests up to 79% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Aviva research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Aviva. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aviva's overall financial health at a glance.
Looking for more ideas beyond Aviva?
If you want to stress test your thesis on Aviva or simply broaden your opportunity set, use the Simply Wall St Screener to line up other companies by balance sheet strength, income profile and valuation quality, all measured against the same yardstick.
- For investors who like to hunt for smaller opportunities with robust metrics, scan a curated group of 13 elite penny stocks with strong financials that already show stronger financial foundations than most peers.
- If your priority is resilient cash generation and capital protection, compare Aviva with a 4 resilient stocks with low risk scores that applies a disciplined lens to stability and downside risk.
- When you want quality fundamentals that the market may not be pricing in yet, line up candidates from a 5 high quality undiscovered gems and see how they stack up against Aviva on your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com