
Universal Display (OLED) Stock Price Drops After Q3 Earnings Strength
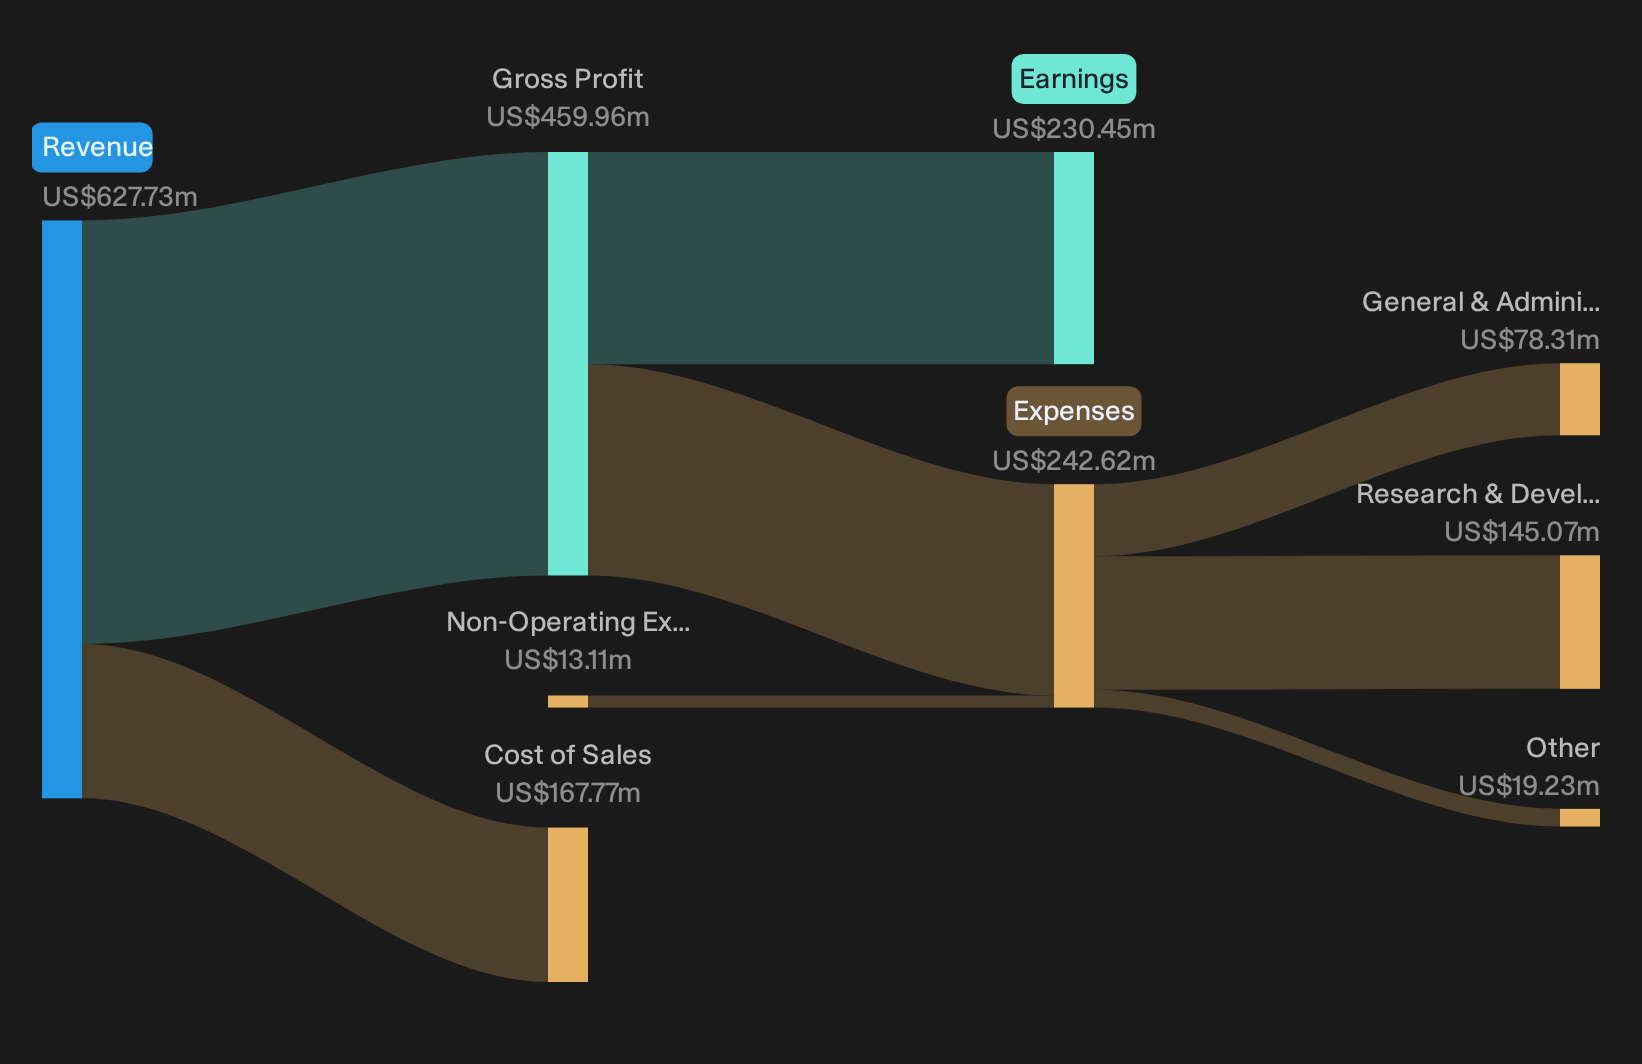
Universal Display entered Q3 2026 earnings after a solid 30-day run, with the share price up double digits over the past month. Then the release hit and the stock dropped about 6% to roughly US$85 by Thursday’s close. The headline story is not the top line; it is the profitability engine. Quarterly revenue printed at US$160.4m while net income reached US$78.9m, keeping this OLED materials specialist firmly in high margin territory even as the market briefly marked the ticker down.
Love Universal Display’s margins but wary of how quickly sentiment can flip on a single quarter? Compare this setup with other profitable compounders in our 30 high quality undervalued stocks
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$160.4m vs. US$139.6m (up about 15%)
- Net Income, excl. extra items (Q3 2026 vs. Q3 2025): US$78.9m vs. US$44.0m (up about 79%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.73 vs. US$0.93 (up about 87%)
- Gross Margin (Q3 2026 vs. Q3 2025): 73% vs. 75% (modestly lower; still in a high range for materials and licensing)
Universal Display kept spotlighting phosphorescent blue as its big swing. Ask Charlie what phosphorescent blue means for Universal Display’s future.
Evaluating Universal Display’s Margin And Mix Ambitions
Supporters argue Universal Display can compound earnings through a richer technology mix and resilient profitability, not just volume.
"Sustained total gross margins around the midpoint of the 74% to 76% range, even during a period of softer material demand, indicate room for operating leverage if material volumes improve."
The latest quarter partially supports that claim. Overall gross margin of 73% sits slightly below the targeted band, and material margin stayed near 50% for a second quarter. Royalty and license income rose relative to materials, which supports the case for higher margins. However, management now guides full year margins toward the low end of its range.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Universal Display Bear Case: Timing Risks Still Unresolved
The bearish view argues that Universal Display’s earnings path is capped by choppy customer orders and slow fab ramps rather than demand forecasts.
"Uneven ordering patterns like the recent pull-ins and timing shifts may continue to cause volatility in quarterly revenue and limit near term earnings visibility."
Quarterly revenue reached US$160.4m, with materials revenue slightly below the prior year and a US$4.8m unfavorable mix adjustment, which keeps that concern alive. Royalty and license income filled the gap this time, but guidance toward the low end of both revenue and gross margin ranges suggests the order cadence and utilization picture is not yet on a smoother footing.
Hunt Quiet Fundamental Disconnects
Universal Display shows that strong margins may not align with a calm share price. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 36% below our estimate - convert a growing backlog of subsea work into quicker tiebacks and extended services arrangements.
- Company 2 - 23% below our estimate - embed an AI assistant into everyday productivity tools so enterprises shift core workflows into its cloud.
- Company 3 - 32% below our estimate - tie premium accelerators to a proprietary software stack that keeps AI customers committed to its compute platform.
Those are three of them. See all 22 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com