
Alphabet (GOOGL) Stock Drops As Q3 Earnings Reveal Profit Reset
Alphabet just dropped Q3 2026 numbers that put the business near a US$0.5b annual revenue run rate, yet the stock closed down 12.6% to US$283.82. One trading session treated this like a problem quarter. The figures on the table told a very different story.
The market fixated on the abrupt reset in basic earnings per share to US$2.14, even as total revenue reached US$127.6b and Google Cloud posted triple digit year on year growth. That disconnect between a sharp price reaction and a still powerful earnings engine is the sentiment story investors now need to unpack.
Love Alphabet’s sheer revenue scale and Google Cloud’s rapid expansion but uneasy about an earnings reset that sends the share price down double digits in a day? Filter for peers that pair resilient cash generation with steadier profit trends using the list of solid balance sheet and fundamentals stocks (22 results).
Q3 2026 Earnings Summary
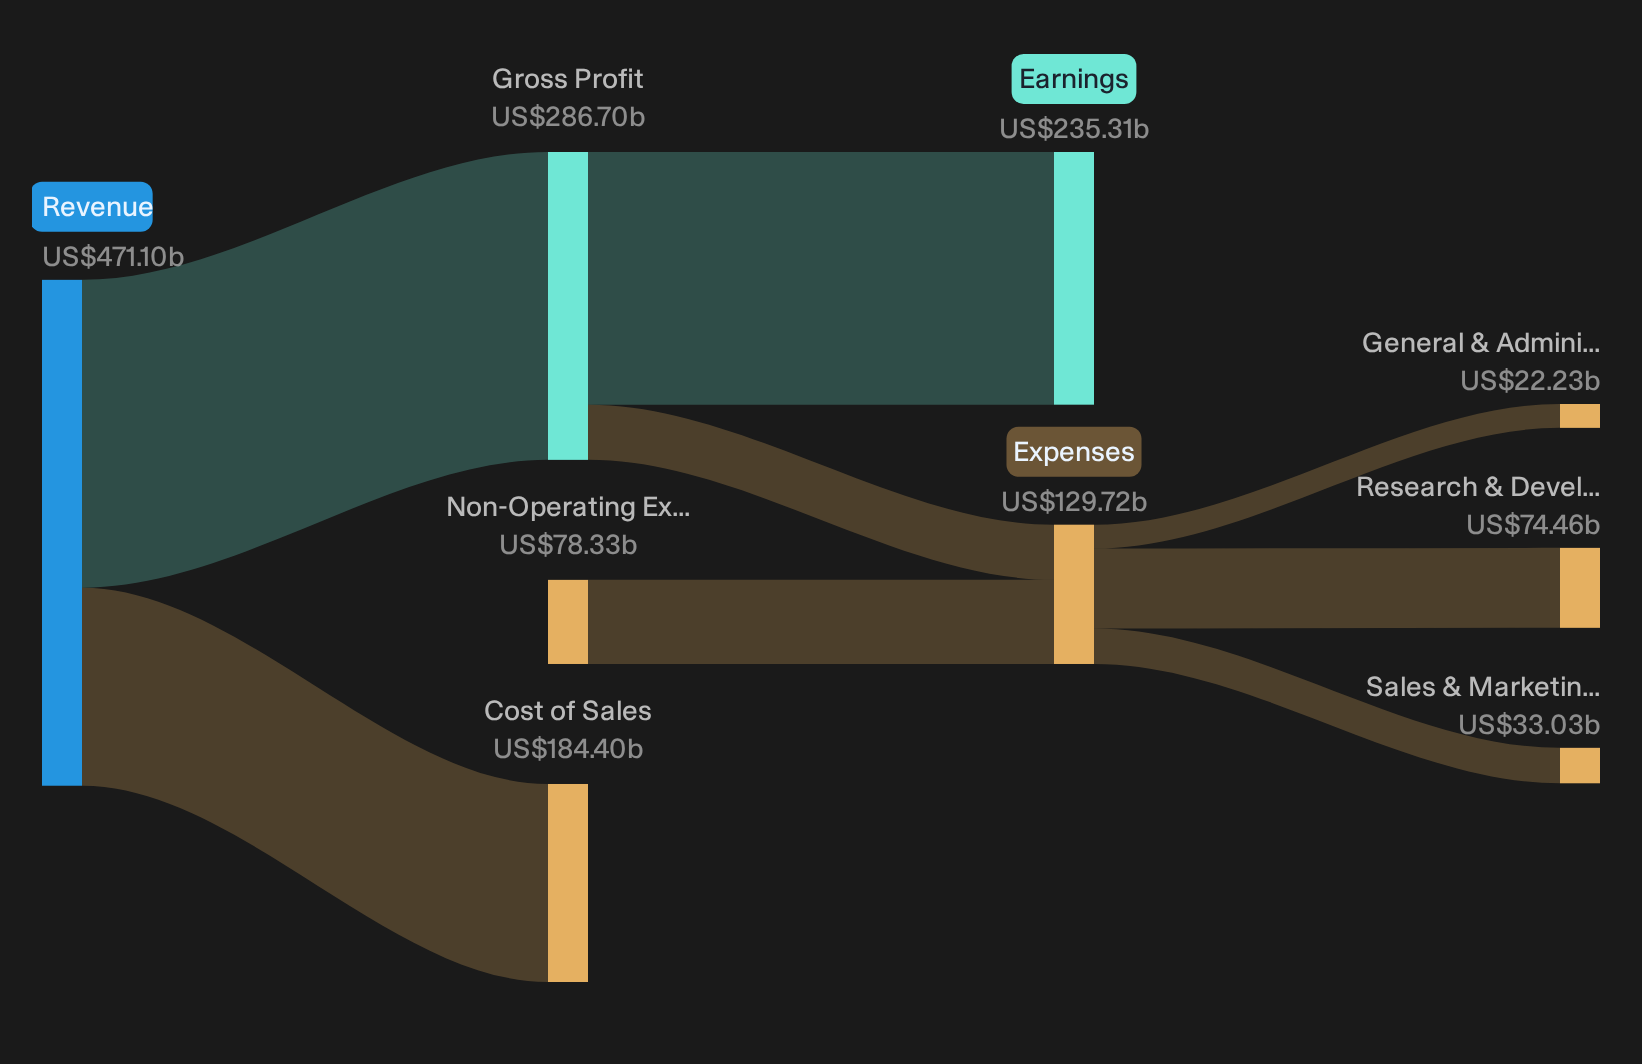
- Revenue (Q3 2026 vs. Q3 2025): US$127.6b vs. US$102.3b (up roughly 25% year on year)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$26.2b vs. US$35.0b (down about 25%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$2.14 vs. US$2.89 (fell about 26%)
- Google Cloud Revenue (Q3 2026 vs. Q3 2025): US$30.7b vs. roughly US$15.1b (about double year on year, with Cloud operating margin at 36.2%)
Earnings grab the headlines, but cash generation is what many valuation focused investors lean on when they judge a business like Alphabet. When you put less weight on this quarter’s headline EPS and look through to Alphabet's cash flows instead, the stock could be a striking 46% undervalued.
Alphabet’s AI Thesis Meets Real Cloud Milestones
Alphabet’s bullish story hinges on AI led enterprise adoption translating into stickier, higher quality Cloud revenue rather than just headline growth.
"More than 17 product lines already exceed US$1b in revenue and new customer acquisitions have more than doubled year on year, while customers typically spend over 50% more than their committed amounts."
Q3 results give that claim real backing. Google Cloud revenue reached US$30.7b with 36.2% operating margin, and the backlog climbed to US$561b with roughly 55% expected to convert inside two years. That scale, plus 103% Cloud growth, shows enterprise AI demand is hitting tangible milestones.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Alphabet’s AI Spend Thesis Hits Margin Reality
Bearish investors have argued that Alphabet’s AI buildout risks turning into a long slog of heavy spending with only patchy payoff so far.
"Alphabet's heavier regulatory and compliance load around data, privacy, and antitrust [will] keep pressuring margins as AI driven products and massive AI infrastructure remain under scrutiny."
Q3 results give that concern real teeth. Operating income of US$40.6b sits against full year CapEx still pegged at US$195b to US$205b and a planned step up in 2027. Q3 free cash flow has already been dragged into roughly US$9b of outflow. Cloud margin at 36.2% looks strong, yet management again flagged third party compute and data centre hardening as future headwinds.
Hunt For Balance Sheet Strength
Alphabet just reminded investors that a sharp earnings reset can collide hard with a hyped narrative. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 32% below our estimate - builds specialized compute platforms for demanding AI workloads in aging data centers.
- Company 2 - 36% below our estimate - converts short lead subsea projects into installation and long term service contracts.
- Company 3 - 23% below our estimate - embeds AI assistants into productivity, developer and security tools on a unified cloud backbone.
Those are three of them. See the full list of 22 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com