
3 UK Energy Stocks That Could Help Offset Rising Household Bills
UK households face rising energy bills, squeezed disposable income and fresh doubts over public spending, which puts pressure on many UK-focused sectors while leaving some large-cap energy producers in a very different position. That gap matters if you are trying to protect your portfolio from the same forces hitting your wallet. This article highlights three UK-listed energy stocks that appear most exposed to these news-driven currents and explains what that could mean for long term investors.
The stocks highlighted below are only a small sample, and the full screen on Simply Wall St surfaced 14 more UK large-cap energy producers with equally compelling stories that are not covered in this article. To see the broader field and identify which ones fit your own risk and income mix, head straight into the UK Large-Cap Energy Producers screener to filter, analyze, and target your highest conviction ideas.
Zephyr Energy (AIM:ZPHR)
Zephyr Energy is a London headquartered oil and gas explorer and producer that gives the screener US upstream exposure rather than direct UK bill sensitivity, generating about US$17 million from exploration and development activities and carrying a market value of roughly £66 million.
Zephyr Energy plugs UK investors into US oil and gas production, with the Paradox Project in Utah offering direct exposure to commodity price cycles while remaining outside the UK consumer squeeze. Recent profitability, rising production and an expanding gas processing setup all point toward earnings that could look very different if one unseen pressure on future cash generation moves in the right direction.
If that unseen pressure matters to you, review the DCF valuation analysis for Zephyr Energy to see how different cash flow paths could reshape Zephyr Energy’s risk reward profile.
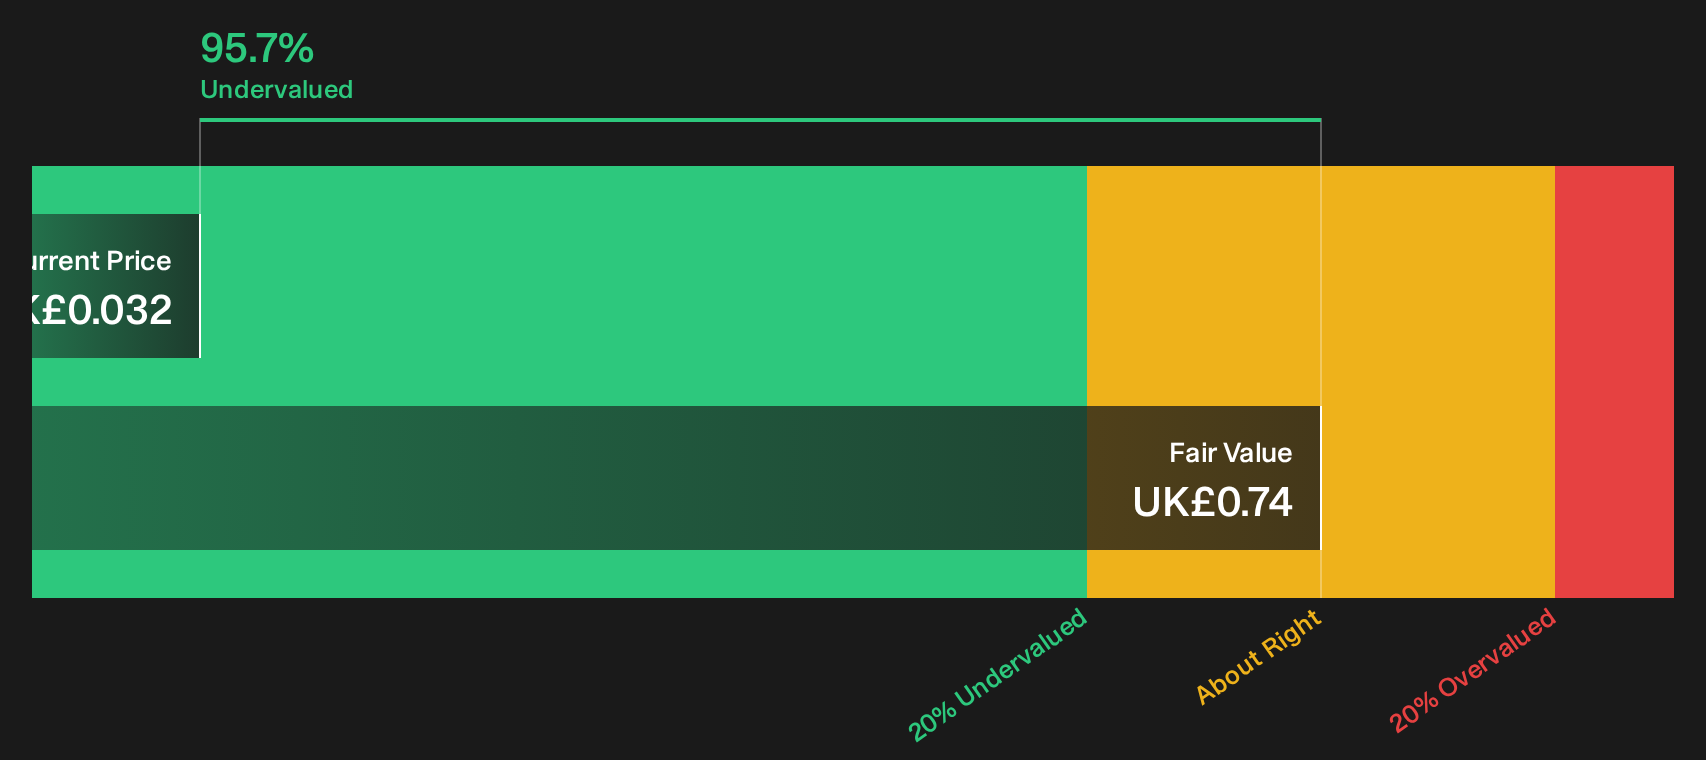
Jadestone Energy (AIM:JSE)
Jadestone Energy slots into the UK Large-Cap Energy Producers theme as an AIM-listed upstream player, giving you pure exposure to oil and gas production across Asia-Pacific through assets in Australia, Malaysia and Indonesia, and a market value of about £234 million.
Jadestone Energy is an Asia-Pacific focused producer in the UK energy screen, with around $259 million from Australian fields, $62 million from Malaysian assets and $93 million from Indonesian production underpinning its upstream story.
For investors looking at energy producers as a potential offset to rising UK household bills, Jadestone Energy brings a focused upstream portfolio where project delivery and contract quality matter as much as headline volumes.
Execution of further infrastructure led gas opportunities around Nam Du and U Minh, where management cites around 800 Bcf of unrisked gas in place with high geological success rates and debottlenecking potential from 80 to 120 mmscfd, could turn the Vietnam hub into a much larger source of contracted sales volumes and multi year revenue.
What happens to future cash generation if a single assumption inside that growth plan shifts even slightly in either direction?
That single shift can reshape the whole story, and the full narrative for Jadestone Energy pulls together how Jadestone Energy’s contracts, capex profile and risk levers could accelerate or stall that cash engine.

Capricorn Energy (LSE:CNE)
Capricorn Energy is one of the clearest fits for the UK Large-Cap Energy Producers theme, with upstream oil and gas operations focused on Egypt that tie earnings power more to global commodity prices than to squeezed UK household demand.
Capricorn Energy generates almost all of its revenue from Egyptian Western Desert assets, with Egypt contributing about $175 million out of roughly $176 million in 2025, and the stock carries a market value of about £294 million.
For investors concerned about weaker UK consumer spending but interested in energy exposure, Capricorn Energy provides a different angle on the same macro story, reflected in the trade off at the heart of its Egyptian focus.
Heavy reliance on Egyptian assets leaves Capricorn vulnerable to payment issues, rising expenses, and geopolitical risks, which may threaten revenue and margin stability even when industry demand is strong.
What happens to Capricorn Energy’s earnings power if one behind the scenes factor in that Egyptian setup shifts sharply in either direction?
If that behind the scenes factor is on your radar, the full narrative for Capricorn Energy lays out how Capricorn Energy’s Egypt exposure could either unlock upside or keep value stalled.

Seeking Alternatives Before Everyone Else
Fresh opportunities move fast. Some are already building breakout momentum while others stay under the radar for now. Scan these ideas before the crowd catches up and consider them while interest is still limited.
- Spot resilient cash generators early by reviewing the list of solid balance sheet and fundamentals (10 results) and focus your research on businesses where debt, liquidity, and fundamentals already look more robust.
- Track potential AI-related ideas with 38 profitable AI stocks that aren't just burning cash where the emphasis is on cash producing operators rather than stories that rely entirely on future funding.
- Explore income opportunities while yields are still elevated and study the 5 dividend fortresses that highlights companies combining higher payouts with balance sheets that can potentially support ongoing distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com