
Albany International (AIN) Stock Cheers Q3 Earnings While Debt Questions Linger
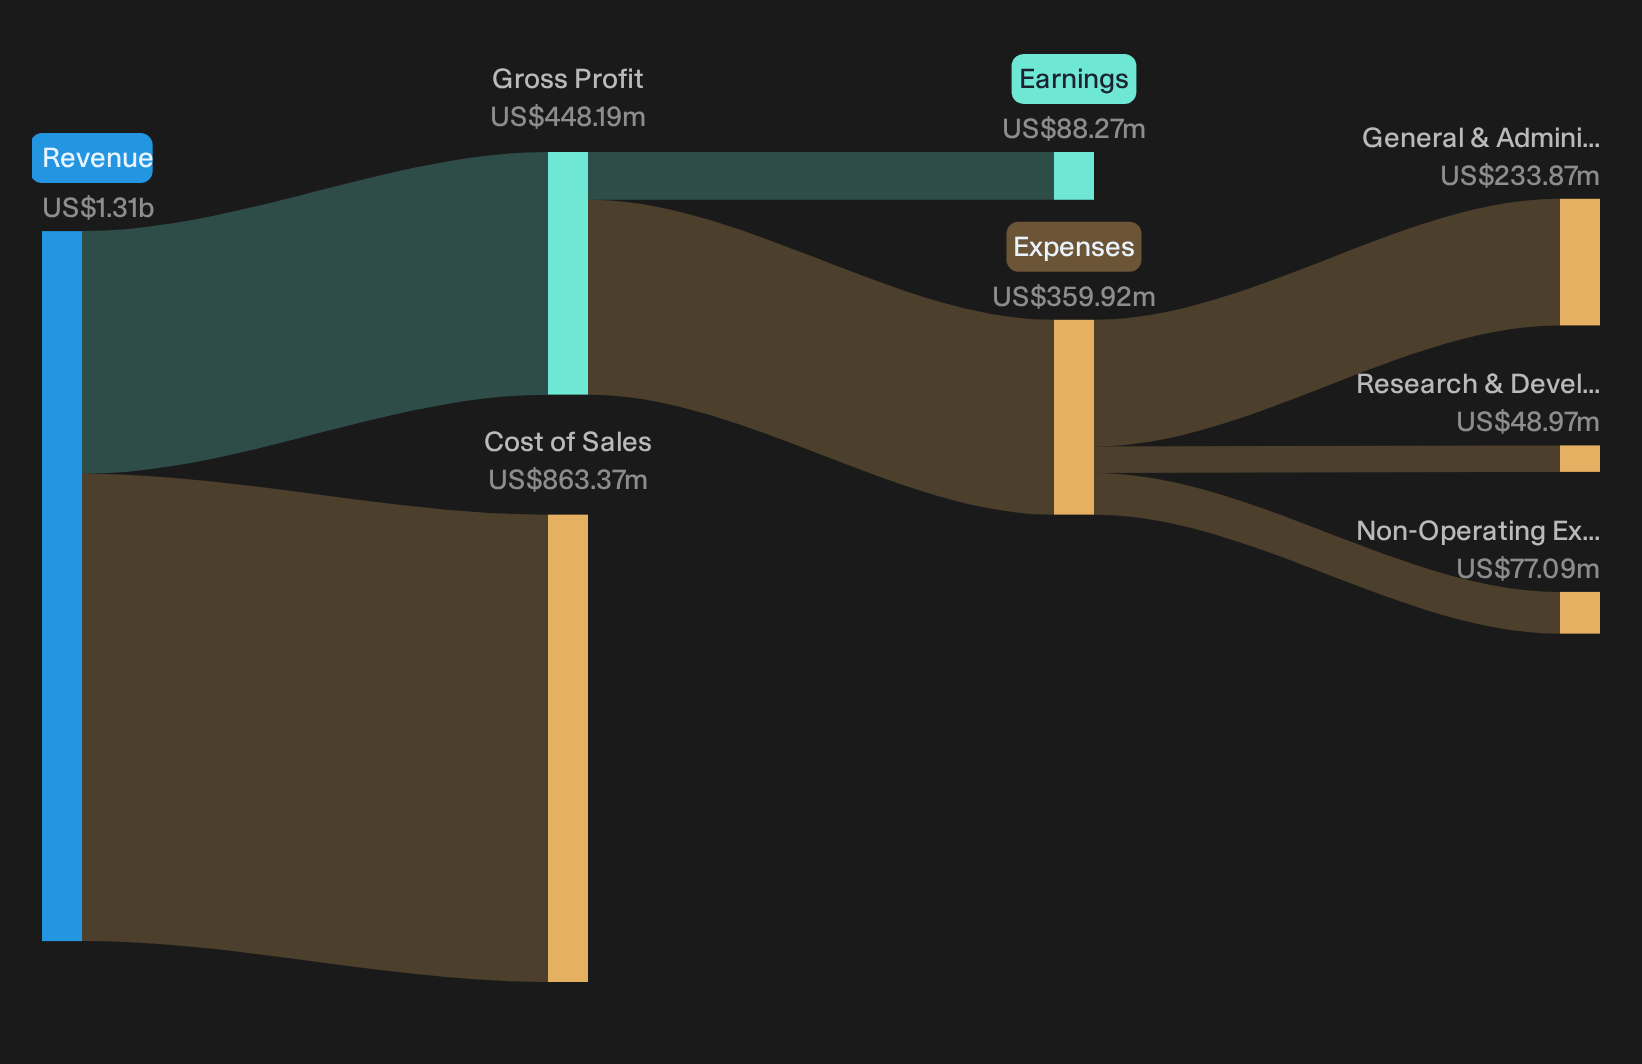
Albany International shares closed at US$64.96 on Thursday, up 4% on the day, as traders cheered a punchy headline from the Q3 2026 report. The company posted basic earnings per share of US$1.47 on revenue of US$349.5m, with profit helped by a large CH‑53K program settlement that lifted Engineered Composites.
In the short term, that kind of jump can appear exciting. Over a longer period, the key question is how much of this profitability is repeatable once the one-off contract benefit fades and how that reconciles with a balance sheet that still carries meaningful debt.
Love the clean US$1.47 EPS print and CH‑53K boost but worried it is a one off with debt still in the background? Benchmark Albany International against our list of solid balance sheet and fundamentals stocks (22 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$349.5m vs. US$261.4m (up about 34%)
- Net Income, Excluding Extra Items (Q3 2026 vs. Q3 2025): US$41.7m vs. a loss of US$97.8m (swing back to profit)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.47 vs. a loss of US$3.37 per share (sharp earnings recovery)
- Engineered Composites Adjusted EBITDA Margin (Q3 2026, including CH 53K effects): 36.5% reported, and management indicated an underlying recurring level of about 12.5%
Earnings grab attention, but cash flows tell you how much hard cash Albany International is actually pulling through the door and how that might anchor any valuation work you do.
On cash flows alone, and keeping all the recent twists in mind, Albany International's current profile suggests the stock could be a clear 22% undervalued.
Albany International’s Bull Story Meets Cash Flow Reality
The upbeat case hinges on Albany International turning contract clean up into reliable cash. The ambition is clear.
"The main thing that has to go right is that Albany International converts its growing composites backlog and contract restructurings into stronger free cash flow despite higher capital spending and working capital swings."
Q3 does provide an early proof point. The CH 53K settlement fed a sharp step up in Engineered Composites profitability, and free cash flow reached US$36.5m even with US$12.2m of capex and US$12.2m of R&D. That hints the contract resets can support cash generation rather than just accounting optics, at least in this quarter.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Albany International: Cash Strain Fears Not Fully Retired
The bearish view hinges on cash being eaten up by composites ramps and Machine Clothing softness rather than landing in shareholders’ pockets.
"Although Albany International highlights record Engineered Composites revenue and a growing list of aerospace and defense programs, the associated inventory build that turned Q2 2026 free cash flow into a net use of US$14.5 million raises the risk that future ramps continue to absorb cash faster than customers convert orders into payments."
Q3 free cash flow of US$36.5m, helped by the CH 53K settlement, shows Albany International can reverse that pressure. Yet underlying AEC EBITDA nearer 12.5% and guidance for lower Q4 earnings mean the test of self funded growth is not finished. The bearish cash strain story is weakened, not closed.
Hunt For Quiet Pricing Gaps
Albany International recently highlighted how a single contract can reshape a quarter and reset expectations. The real opportunity could be in solid businesses that the market prices cautiously before sentiment aligns with fundamentals.
- Company 1 - 40% below our estimate - expands branded and private label coconut drinks as retailers promote the category across more shelves.
- Company 2 - 16% below our estimate - adds manufacturing lines aimed at AI driven data center optics as customers push higher value photonics work.
- Company 3 - 49% below our estimate - tests whether a dominant payments and marketplace ecosystem can copy its model into a new country.
Three companies from the same screener. Open all 30 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com