
Align Technology (ALGN) Stock Faces Flat Reaction After Q3 Earnings Beat
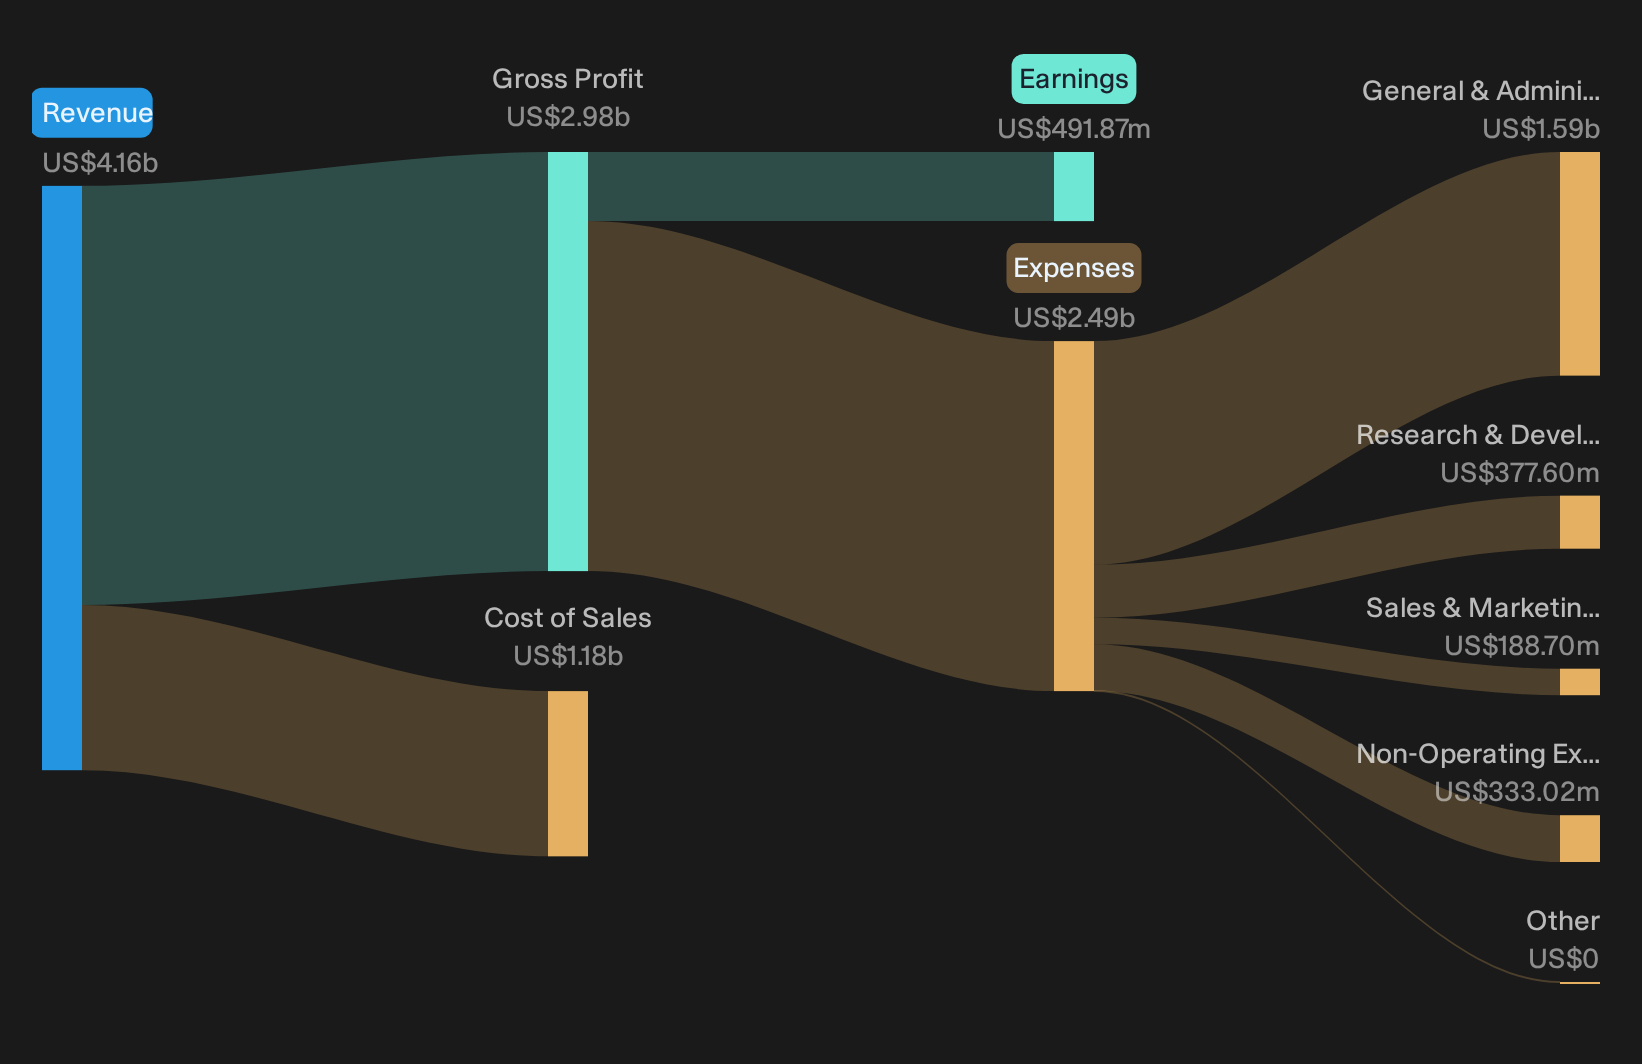
Align Technology just reported Q3 2026 and the headline is clear. Earnings per share moved to about US$1.90 on revenue of roughly US$1.01b, while the stock barely budged, up only 0.06% today around US$154. For an orthodontics and dental equipment specialist that lives and dies on procedure volume and pricing power, that muted share reaction sits oddly against a quarter where profit per share outpaced earlier in the year even as sales stayed roughly flat.
Like the earnings profile at Align Technology but uneasy about a flat share price reaction and reliance on procedure volume? Consider using the list of solid balance sheet and fundamentals stocks (22 results) as a benchmark list for companies that pair dependable balance sheets with steadier market sentiment.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$1,014.8m vs. US$995.7m (up about 1.9%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): US$135.0m vs. US$56.8m (more than doubled)
- Basic EPS (Q3 2026 vs Q3 2025): US$1.90 vs. US$0.78 (very large year on year increase)
- Trailing 12 Month Net Income (Excl. Extra Items; Q3 2026 TTM vs Q3 2025 TTM): US$491.9m vs. US$378.4m (up about 30%)
Align is changing CEOs just as it rewires its strategy. Ask Charlie what Align’s CEO transition means for its 2027 plan.
Align bullish story: execution vs expectations
Optimists argue that Align Technology can convert international and DSO momentum plus new access models into sturdier growth. The key ambition is captured here.
"The main factor that has to go right is that Align Technology continues to expand access and utilization through new products, flexible acquisition models, and consumer financing while managing regulatory and legal developments in key markets."
Q3 showed some of this playing out. Clear aligner shipments reached 691,000 with record doctor submitters and higher utilization, and the installed scanner base grew double digits even as Systems & Services revenue declined. Operating margin also improved against last year’s TTM profit base.
Align bear worries: demand and mix risks tested
On the flip side, skeptics focus on U.S. demand and scanner mix as possible drags that could offset Align Technology’s international strength.
"Persistent weakness in North America retail Invisalign demand, which management describes as a drag compared with stronger international and DSO channels, could limit clear aligner case volumes and constrain Align Technology revenue and earnings if it offsets growth elsewhere."
Q3 revenue landed near US$1.01b with only modest top line progress and the stock barely moved. Systems & Services revenue declined 7.6% as leasing and rentals replaced upfront sales. That mix shift plus ASP pressure in clear aligners supports concerns that softer North America and lower priced models are still a live headwind.
One Narrative disagrees with today's price. → See where this Narrative says Align Technology should trade.
Hunt For Mispriced Earnings Power
Align Technology just showed how earnings strength and a flat share price can disconnect. The real opportunity could sit in stocks the market has not fully re-priced yet.
- Company 1 - 26% below our estimate - builds specialized chips and software that move, secure, and manage data as AI and cloud reshape digital infrastructure demand.
- Company 2 - 21% below our estimate - expands a surgical robotics platform as hospitals adopt new joint procedures and connected care tools relying on its installed hardware base.
- Company 3 - 46% below our estimate - turns an AI-heavy recommendation engine into a system that predicts purchases and sells that intent to advertisers across attention-rich apps.
That is three of the list. See the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com