
Landstar System (LSTR) Q3 Results Reveal An Insurance Cost Squeeze
Landstar System walked into this Q3 2026 earnings print with a stock that had slid over the past quarter, then popped 1.9% today to about $141. That quick relief rally sits awkwardly against the headline result. Core trucking revenue reached roughly $1.4b and net income came in near $48m, yet an unusually heavy insurance and claims bill took a clear bite out of profit quality.
Short term traders are cheering the bounce. Long term holders are now weighing whether a recurring cost problem is being exposed just as the broader freight cycle shows signs of life again.
Impressed by Landstar System’s freight reach but uneasy about that heavy insurance and claims hit to Q3 profit quality? Check out our list of solid balance sheet and fundamentals stocks (22 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$1,514.1m vs. US$1,208.7m (up about 25%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$48.0m vs. US$19.4m (more than 2x higher)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.42 vs. US$0.56 (more than 2x higher)
- Gross Margin (Q3 2026 vs. Q3 2025): 8.4% vs. 9.2% (margin rate compressed)
Earnings paint part of the picture for Landstar System, but cash flows often tell you more about what you are really paying for each dollar the business brings in. Investors who care about valuation tend to start there rather than stop at quarterly profit headlines.
On cash flows alone, if you run the numbers on Landstar System’s recent performance, the stock could be a hefty 38% undervalued.
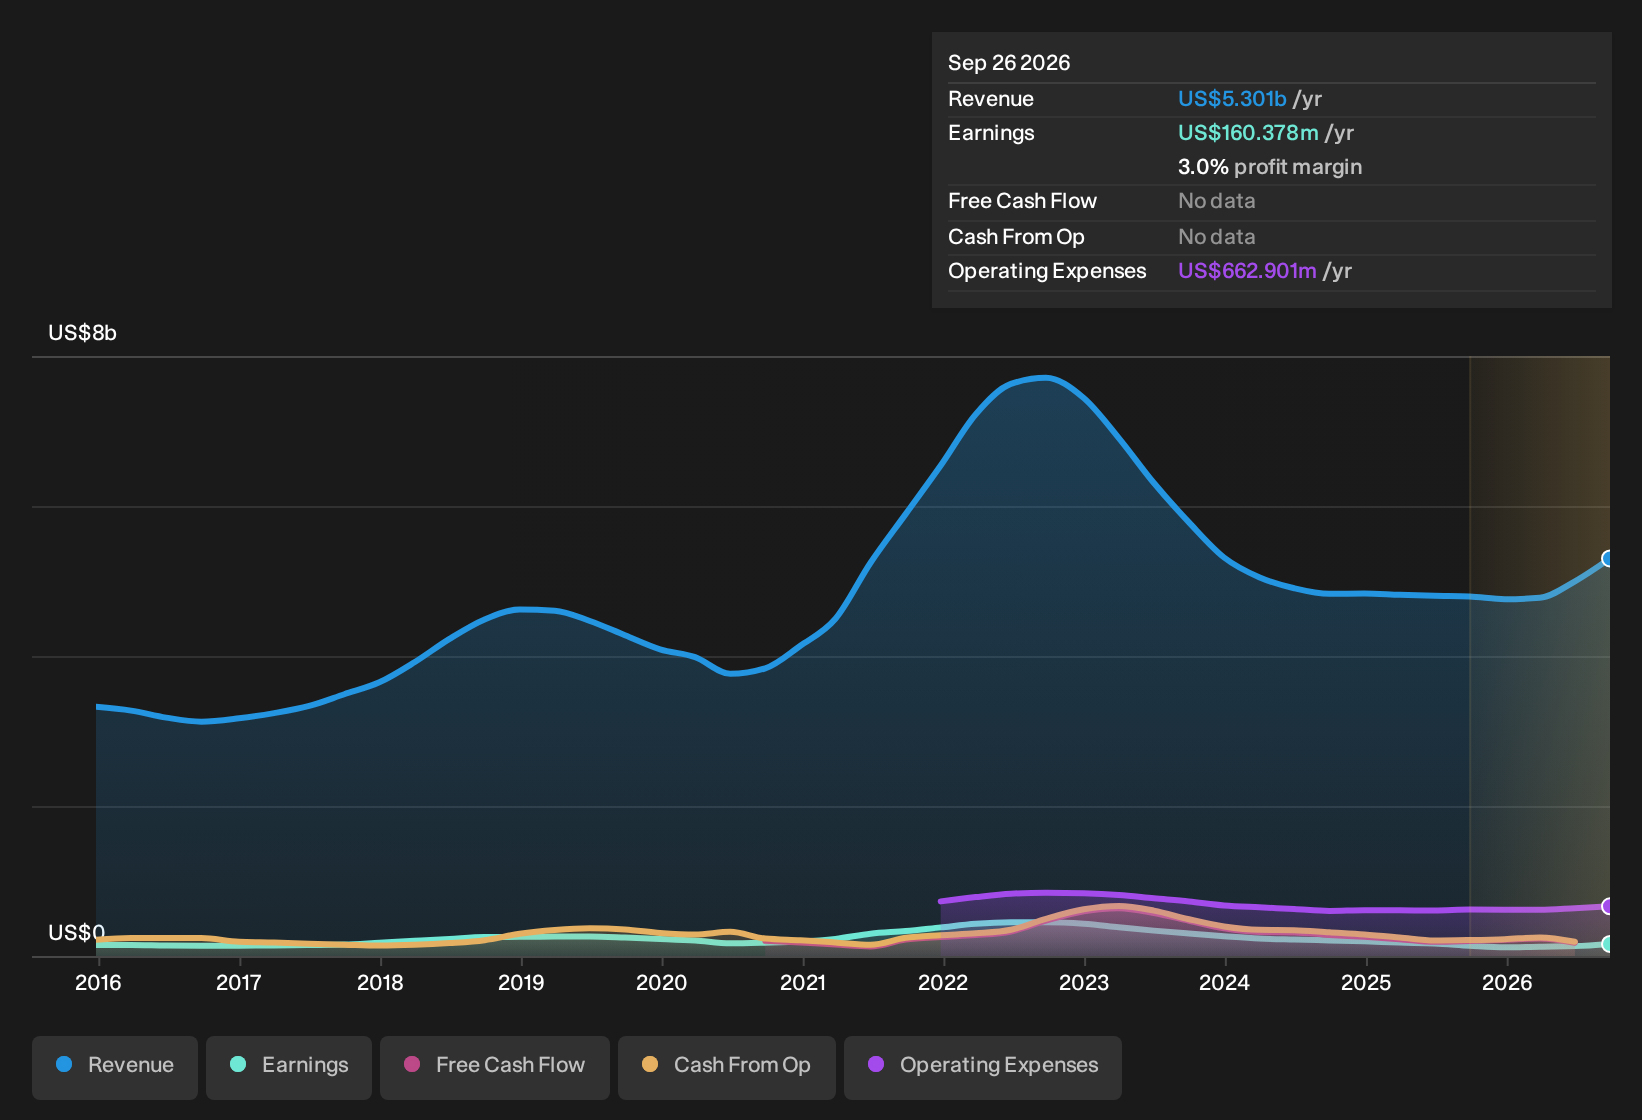
Evaluating Landstar’s Bull Case Against Q3 Milestones
Supporters argue Landstar System can compound through a heavier freight mix and better technology. That ambition is clear in management’s own words.
"The focus on heavy haul within the unsided platform business, supported by dedicated leadership, agent engagement and targeted equipment investment, is attracting broad based demand from sectors such as data centers, energy, government and aerospace."
Q3 results give that claim additional support. Heavy haul revenue reached about US$185m with 11% more loads and 13% higher revenue per load. Broader truck revenue per load rose 25%, with October loads and pricing both running well ahead of last year, which points to tangible freight mix and pricing milestones for the bullish view.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Landstar Liability Fears Move From Theory To P&L
Bearish investors worry that Landstar System’s legal and regulatory backdrop will quietly erode profitability over time rather than in one obvious hit.
"The Supreme Court case and potential legislative responses may push brokers to carry larger insurance limits and change liability rules. While Landstar System already runs a sizable insurance tower, higher required coverage levels and legal complexity could still raise insurance and claims costs and offset recent improvements in cargo theft frequency and severity at the earnings line."
Q3 results lean toward validation. Insurance and claims expense jumped to US$55.3m, including US$22m of prior year reserve adjustments, and materially compressed net income despite solid freight pricing and heavy haul traction.
Hunt For Mispriced Earnings Stories
Landstar System just showed how cleaner freight metrics can coexist with complex insurance and claims outcomes. The real opportunity is finding stocks that could be undervalued before the market reevaluates them.
- Company 1 - 20% below our estimate - builds a broader cardiometabolic and obesity therapy lineup while scaling manufacturing capacity and payer coverage.
- Company 2 - 37% below our estimate - expands protective film output and supply chains to deepen higher margin services with automakers and dealerships.
- Company 3 - 40% below our estimate - grows coconut based beverage volumes across branded and private label offerings while containing packaging, energy and freight costs.
Those are three of them. See the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com