
Norwood Financial (NWFL) Stock Cools After Record Q3 Earnings Strength
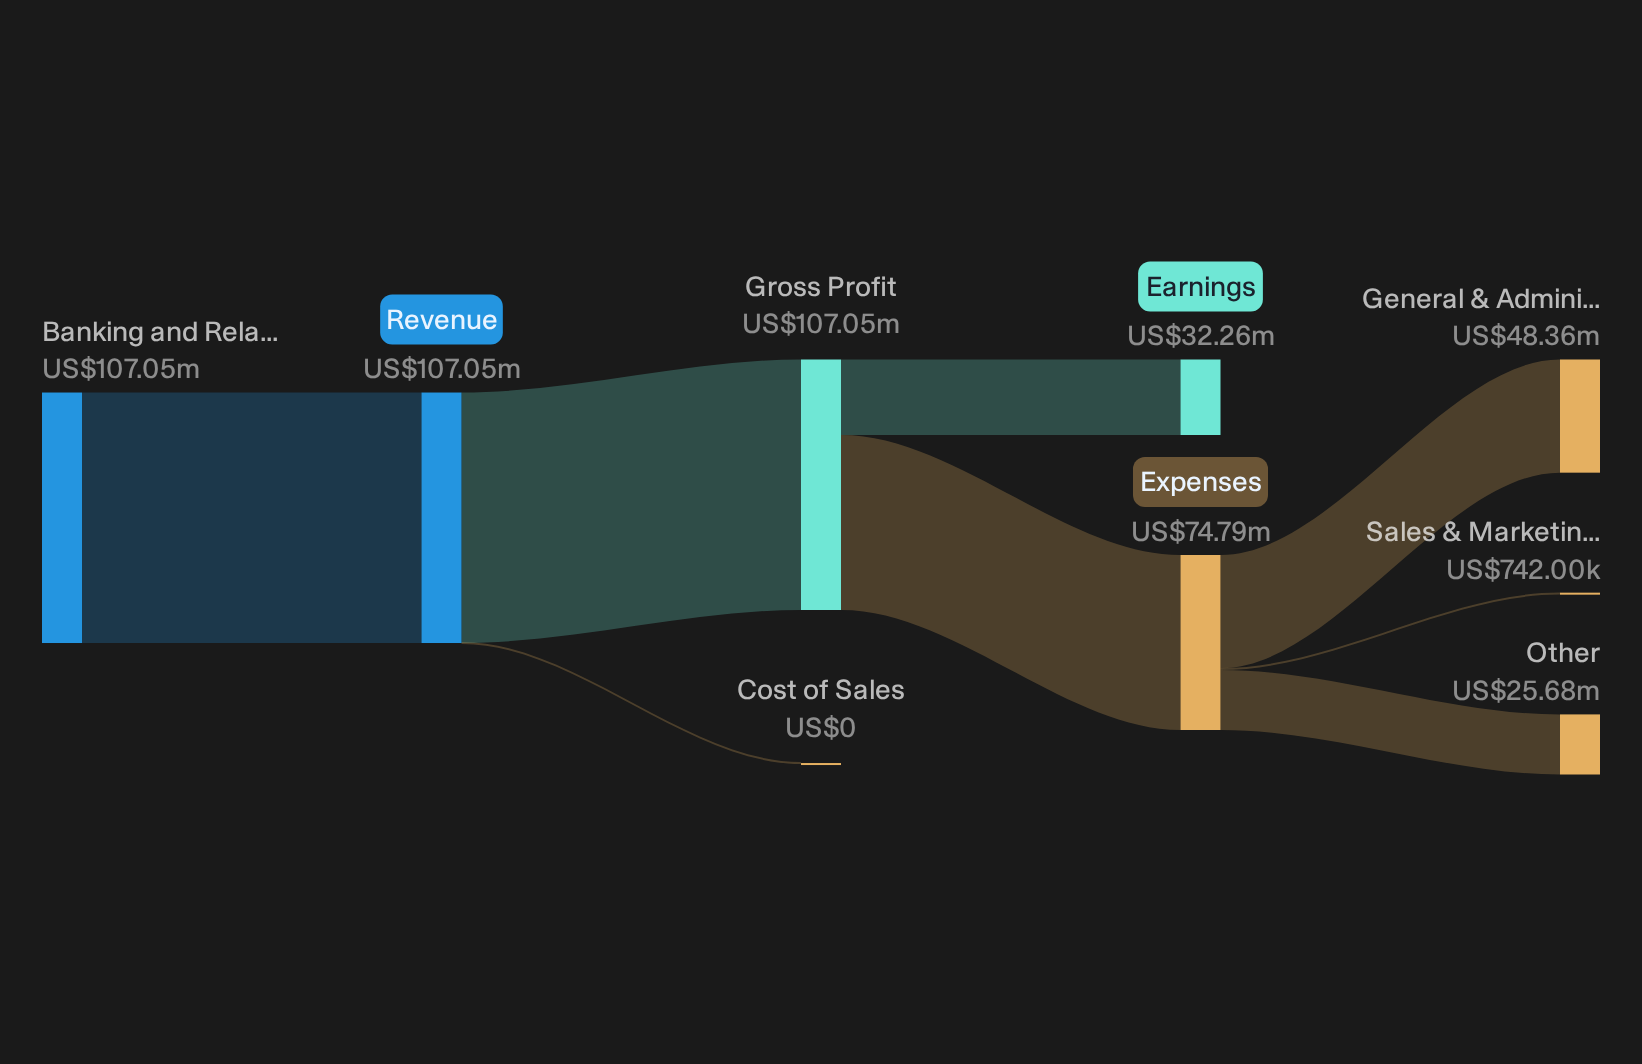
Norwood Financial just released its Q3 2026 numbers and the headline is straightforward. Record net income of US$11.8 million and earnings of US$1.08 per share came alongside a net interest margin of 4.01%. Yet the stock slipped about 0.7% to US$35.64.
That small dip follows a solid run over the past month and appears more like a cool down than a verdict on the quarter. The market is reacting to a generally negative trading day, while the results themselves highlight a bank reporting stronger profitability and only a muted shift in sentiment.
Like the look of Norwood Financial’s record net income and 4.01% net interest margin but want a wider set of banks with strong profitability and solid balance sheets to compare it against? Line up Norwood’s results next to a curated list of solid balance sheet and fundamentals stocks (22 results).
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs Q3 2025): US$30.829 million vs. US$23.465 million (higher quarterly top line)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): US$11.763 million vs. US$8.334 million (stronger quarterly profit)
- Basic EPS (Q3 2026 vs Q3 2025): US$1.08 vs. US$0.894589 (firm earnings per share improvement)
- Net Interest Margin, NIM (Q3 2026 vs Q3 2025): 4.01% vs. 3.63% (clear margin expansion on lending activity)
Norwood is rolling out AI across the bank after record margins. Ask Charlie what Norwood’s AI push really means for profits.
Norwood Financial’s Margin Ambitions Face A Real-World Check
Optimists have argued Norwood Financial’s loan and securities moves would steadily lift profitability toward internal targets.
"Ongoing repricing of the loan portfolio at higher yields, combined with the 2024 securities repositioning, should continue to push net interest margin toward management’s target and support earnings expansion."
Q3 delivered a 4.01% NIM with record net interest income of US$28 million, helped by Presence and roughly US$400,000 of benefit from a resolved bankruptcy. That hits the margin milestone on paper. Management, though, now plays down further NIM expansion in this rate cycle, which tempers how repeatable this quarter looks.
Bear Case On Funding Costs And Merger Risk Gets Reframed
Skeptics worry that funding and M&A could undercut Norwood Financial’s profitability story.
"Norwood’s large base of municipal and specialized deposits that are closely tied to market rates could prove less rate sensitive on the way down than management expects, keeping funding costs elevated and pressuring net interest margin and profitability."
Retail CD costs eased through Q3 and NIM printed at 4.01%, so funding pressure did not dominate this quarter. Presence integration and core conversion are now complete, with merger expenses largely behind the bank and operating leverage improving. The near term data point more to execution progress than to merger drag or runaway deposit costs.
The price and this Narrative do not agree. → Uncover what this Narrative says Norwood Financial is actually worth.
Hunt Quiet Disconnects In Plain Sight
Norwood Financial recently reported results that highlighted steady fundamentals despite a relatively muted share price move. The real opportunity could be identifying stocks that the market may not have fully repriced yet based on current information.
- Company 1 - 37% below our estimate - expand a manufacturing and supply chain buildout that channels demand toward film and service offerings.
- Company 2 - 32% below our estimate - sell processing platforms and a software stack that data centers use as AI workloads reshape system needs.
- Company 3 - 44% below our estimate - convert a large construction backlog and mega-project pipeline into cash while addressing key legal disputes.
Three companies from the same screener. Open every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com