
3 Eurozone Utility Stocks Investors Are Watching As Energy Prices Pressure The ECB
Energy prices are again putting pressure on the ECB, and that is pulling regulated utilities and grid operators into the spotlight as investors reassess where resilience might come from if borrowing costs rise. With inflation risks back in focus and growth worries circling, steady cash flows and policy-linked revenues can start to look more interesting. This article walks through 3 Eurozone utilities stocks exposed to these themes and explains why they may matter for your watchlist.
The stocks in the list below are just a starting sample. The full screen surfaced 18 more Eurozone utilities and energy infrastructure companies with equally compelling narratives that are not covered here.
If you want to identify potential power grid, pipeline and regulated utility opportunities that match your own risk and income profile, head straight to the Eurozone Regulated Utilities and Energy Infrastructure screener to filter, analyze and focus on the highest conviction ideas.
Terna (BIT:TRN)
Overview: Terna operates Italy’s high voltage electricity transmission grid, managing and developing the network that keeps power flowing reliably across the country.
Operations: Terna generates about €3.3b from regulated activities and €905m from non regulated operations, primarily within its electricity infrastructure business.
Market Cap: €19.1b
Terna matters for this screener because it is the pure grid backbone of Italy, with regulated revenues that can help steady portfolios when energy prices and interest rates start pulling markets around.
"Ongoing and accelerating investments in grid modernization, digitalization and resilience remain visible through Terna’s H1 2026 CapEx of €1.6b, with about €1.5b in regulated activities and 92% of the 2024–28 plan already under awarded contracts. These dynamics are linked to the evolution of the regulated asset base and the corresponding regulated revenue and EBITDA."
What happens to that regulated income stream if a single key regulatory assumption on allowed returns or incentives shifts even modestly?
Small tweaks to those assumptions can shift the whole grid story, so it is worth reading the full narrative for Terna to see how that risk and upside really balance.

E.ON (XTRA:EOAN)
Overview: E.ON is a large Essen based utility that runs regulated power and gas networks while supplying electricity and energy solutions across Europe.
Operations: E.ON generates most of its revenue from Energy Networks and Energy Retail in Germany and the United Kingdom, with sizable contributions from Energy Infrastructure Solutions and other European markets.
Market Cap: €49.5b
Where Terna offers a pure grid play, E.ON brings a broader Eurozone regulated networks and supply mix. This ties directly into the screener’s focus on stable infrastructure cash flows when energy prices and interest rates start to bite.
"Rising connection requests for renewables, batteries, data centers, EVs and heat pumps, alongside EU electrification targets that point to a higher share of electricity in final energy use by 2040, can support sustained growth in E.ON’s regulated grid investment base and long term network revenue."
What really matters now is how one unresolved regulatory decision shapes the balance between that grid build out and future earnings resilience.
That unresolved call is exactly what the full narrative for E.ON unpacks, showing where regulation risk could be masking E.ON’s long term earnings potential.
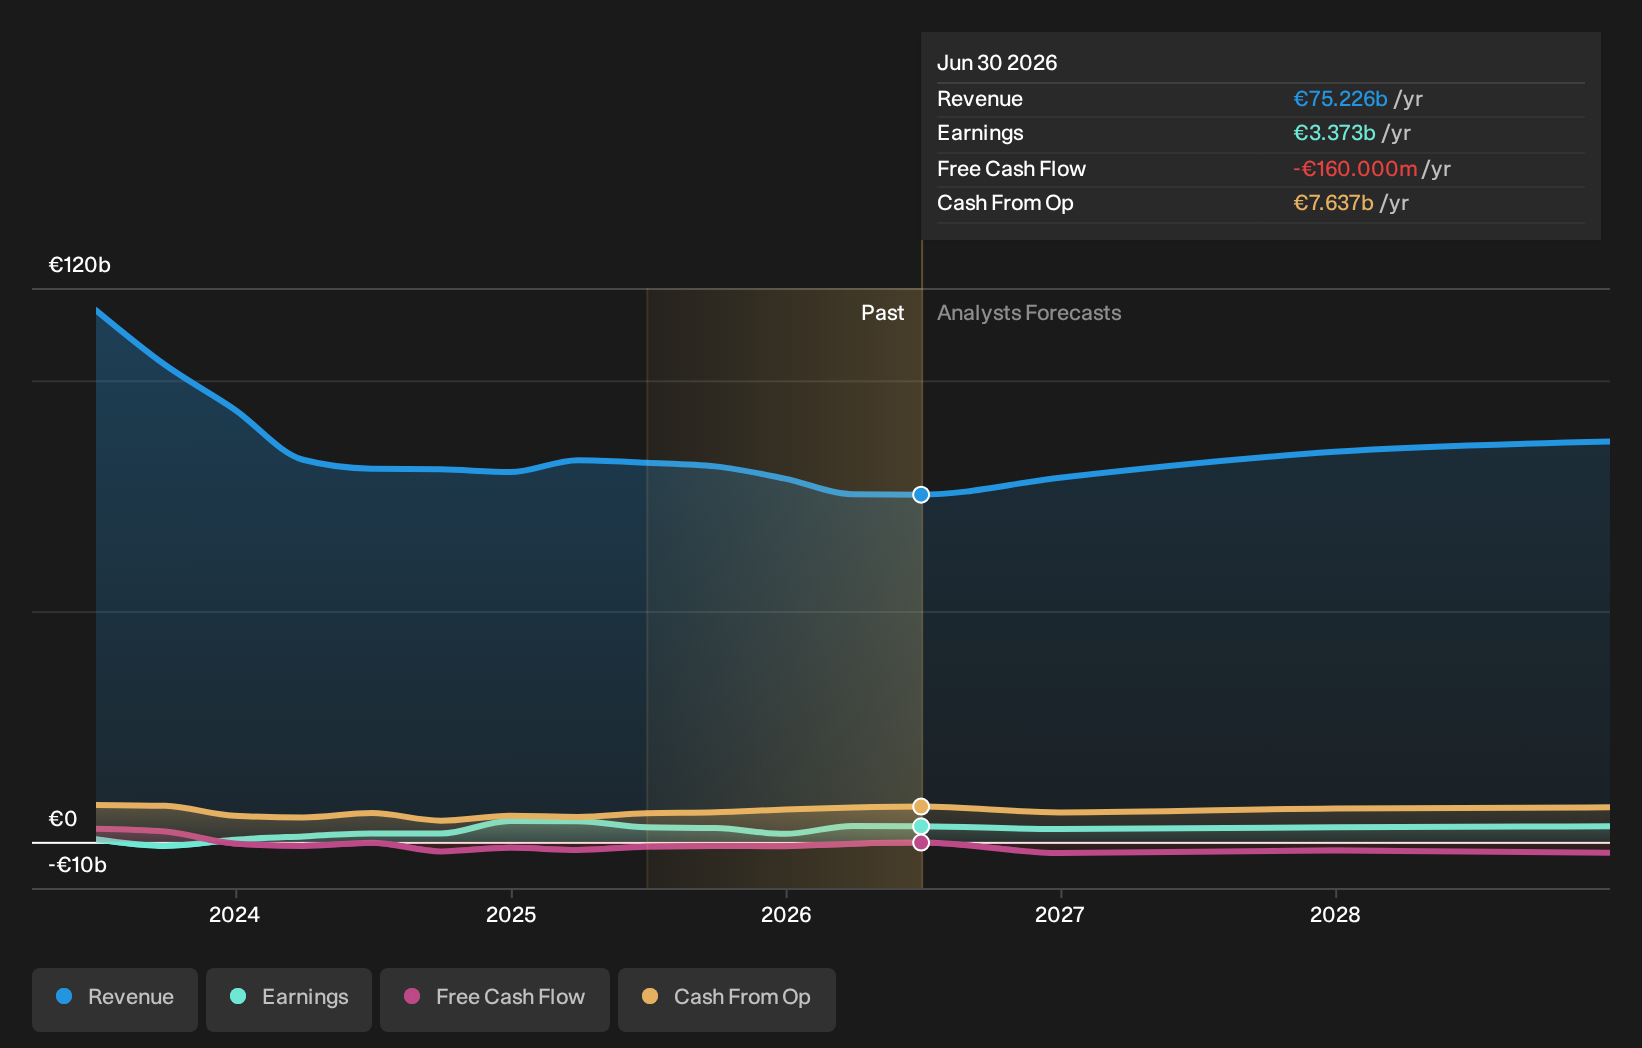
Redeia Corporación (BME:RED)
Overview: Redeia Corporación runs Spain’s high voltage electricity transmission grid under a regulated framework, earning tariff based revenue that ties directly into the Eurozone utilities and energy infrastructure theme.
Market Cap: €8.3b
Redeia Corporación is the pure Spanish grid operator in this screen. When the ECB worries about energy driven inflation and rate volatility, this kind of regulated, tariff based backbone is exactly what many investors look at for steadier earnings and cash flows.
"Acceleration of Redeia Corporación’s electricity transmission capex, with more than €1.5b invested in 2025 and management expecting 2026 TSO investment to reach and probably exceed that level, supports continued growth in the regulated asset base and therefore in future regulated revenue."
What happens to that earning power if a single regulatory or funding assumption around this capex heavy plan shifts against expectations?
If that risk starts to bite, the full narrative for Redeia Corporación shows how Redeia Corporación’s capex plan could still translate into accelerating grid earnings power.

Seeking Alternatives Before Momentum Flies
Fresh opportunities can move from quiet to fully priced quickly. Some ideas are already building breakout momentum under the radar for now. Scan them before the crowd and review them promptly.
- Find income workhorses with sturdy payouts and resilient balance sheets by scanning the 229 dividend fortresses while yields still look compelling and before prices start moving higher.
- Track next wave infrastructure enablers powering AI data centers and electrification, then sort through the curated 43 power grid technology and infrastructure stocks while it still appears under followed.
- Identify early movers at the edge of computing and sensing, then filter the hand picked 25 quantum computing stocks before momentum traders increase their interest.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com