
EPR Properties (EPR) Stock Climbs As Q3 Results Spotlight Interest Coverage Risk
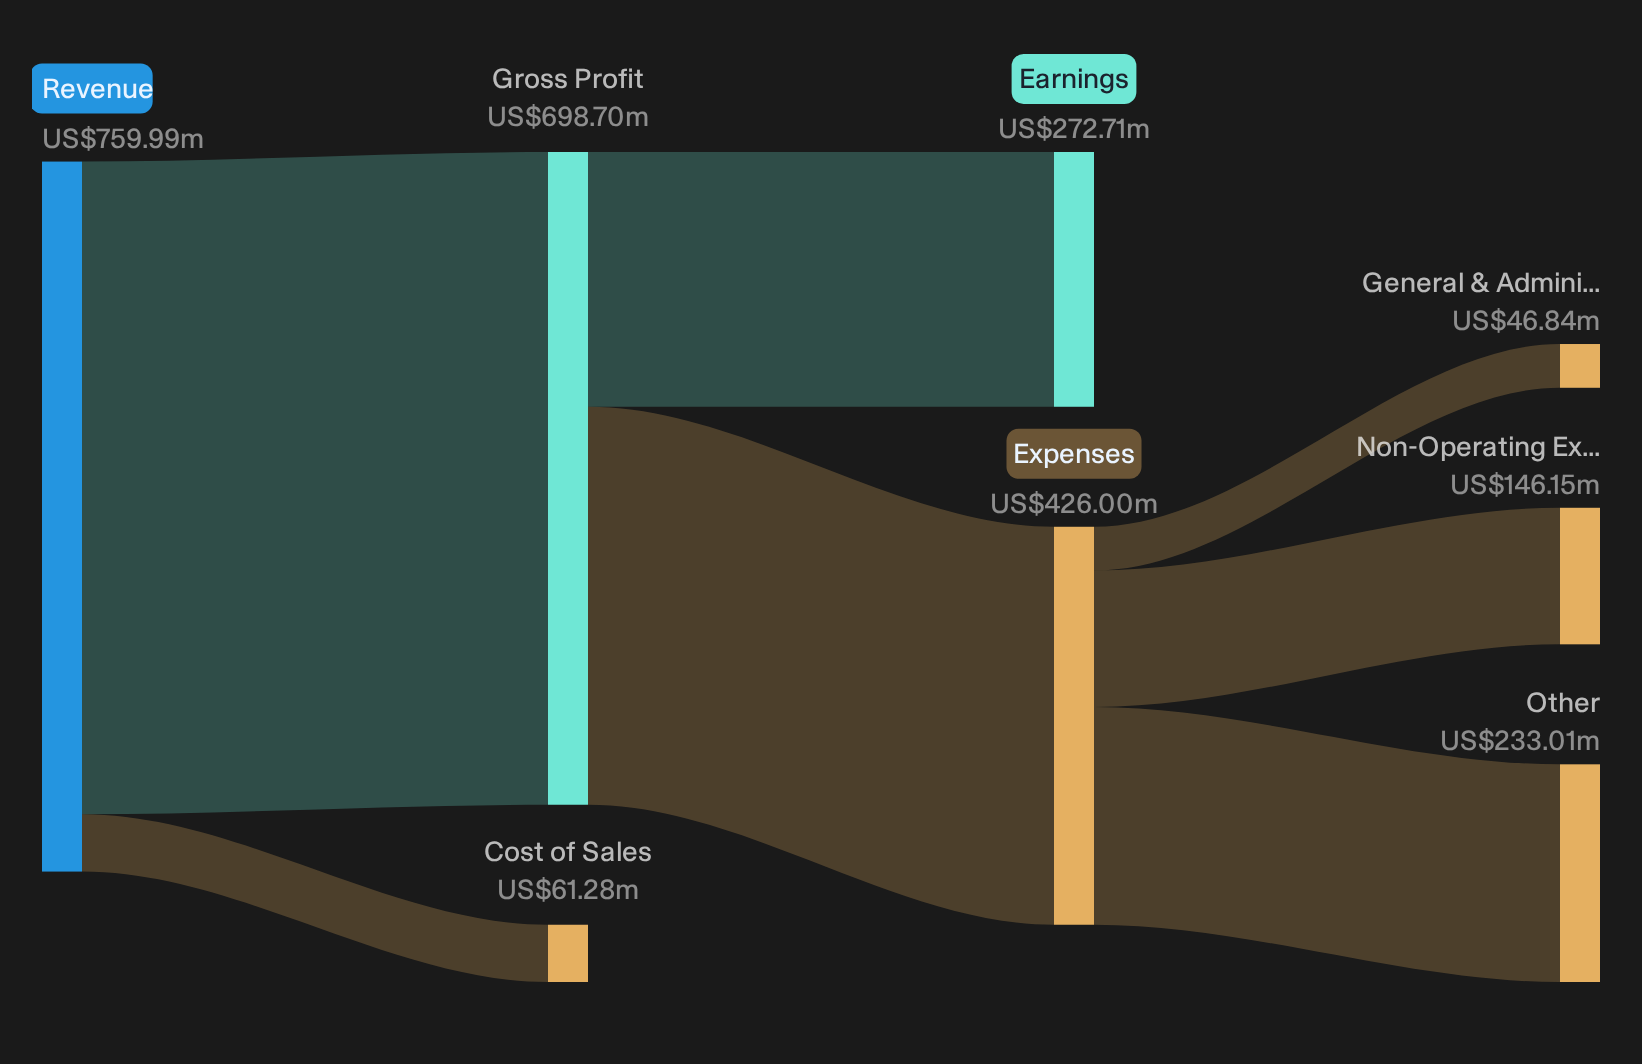
EPR Properties stock jumped 5.1% to US$58.34 after its Q3 2026 release, a strong move for a real estate investment trust that usually trades on income stability rather than momentum. The headline was simple enough. Funds From Operations, the cash flow metric that really matters for this sector, stayed firmly in nine figure territory across the year and sat alongside trailing net income of US$272.7 million.
Short term traders are reacting to the pop. Longer horizon investors are already asking a different question: Does this level of earnings power justify a P/E of 16.4 against peers while interest coverage remains a clear pressure point?
Love EPR Properties’ steady cash generation but worried about interest coverage risk in a higher rate world? Check out our list of solid balance sheet and fundamentals stocks (22 results) for ideas that combine dependable cash flow with stronger debt cushions.
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$204.1 million vs. US$185.1 million (up roughly 10%)
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): US$94.1 million vs. US$60.6 million (up roughly 55%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.23 vs. US$0.80 (up roughly 54%)
- Funds From Operations (FFO, Q3 2026 vs. Q3 2025): US$95.7 million vs. US$95.7 million (stable year on year)
Prefer clean charts to a wall of earnings figures and footnotes? View EPR Properties’ valuation, balance sheet strength and recent results in our interactive company report for EPR Properties.
EPR Properties: Testing The Experiential Pivot
The bullish story leans heavily on EPR Properties turning theaters into a smaller slice of a broader experiential mix while keeping the balance sheet ready to fund that shift.
"The main thing that has to go right is that EPR Properties continues to redeploy capital away from theaters into a broader mix of experiential properties while maintaining strong rent coverage, conservative leverage and access to attractively priced funding for elevated investment activity."
Q3 shows that program in motion rather than on paper. Full year FFO guidance is higher, investment spending guidance of US$600m to US$700m is reaffirmed, and an amended credit facility has lowered borrowing costs and extended maturities. That matches the funding and deployment goals in the thesis.
Theater And Discretionary Risk Under The Microscope
The bear story centers on whether EPR Properties is still too exposed to in person entertainment if consumer habits or the economy weaken.
"EPR Properties still has meaningful exposure to theaters and other in person entertainment venues, and the evidence focuses on current box office and food and beverage economics without showing how these venues might perform if consumer time and spending shift further toward at home digital options."
Recent quarters show earnings power intact, with Q3 FFO firmly above US$100m and rent coverage around 2.0x across a 99% leased portfolio. That supports the idea that tenants are currently paying their bills. It does not yet reveal any hit from a shift to at home entertainment or weaker discretionary demand.
The price and this Narrative do not agree. → Uncover what this Narrative says EPR Properties is actually worth.
Hunt For Quiet Earnings Power
EPR Properties just showed how consistent earnings can still leave investors debating valuation today. The real opportunity sits in finding companies that could be undervalued before the crowd starts paying attention.
- Company 1 - 26% below our estimate - expands a low cost digital banking model as customer counts, revenue per user and efficiency metrics all climb together.
- Company 2 - 37% below our estimate - builds protective films and services while pouring fresh capital into manufacturing and higher margin installation and dealership channels.
- Company 3 - 16% below our estimate - ramps optical manufacturing capacity as AI heavy data center customers shift more complex photonics and packaging work its way.
Those are three of them. See every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com