
Coca Cola Media Win Has The WPP Stock Case Changed?
- Coca-Cola recently confirmed that WPP Open X remains its media partner across most global markets outside North America, while Omnicom takes on media duties in that region and Dentsu keeps Japan and South Korea.
- Retaining Coca-Cola’s media remit across more than 200 countries reinforces WPP’s role in integrated, data and AI driven marketing programmes at global scale.
- We will now look at how WPP’s investment narrative could shift given Coca-Cola’s renewed global media commitment to WPP Open X.
WPP Investment Narrative Recap
To own WPP, you need to believe its Elevate28 cost work, AI platforms like WPP Open, and integrated media plus production model can stabilise like for like net sales after recent declines and lift margins from current loss making levels. The renewed Coca Cola remit supports that broader thesis but does not, on its own, change the near term pressure on organic revenue.
The key short term swing factor remains whether cost savings arrive in line with the £500m gross annualised target, while incentives and growth investment stay disciplined. The main risk is that weak client spending, pricing pressure in production and interest costs, which are not well covered by earnings, keep profitability under strain.
The executive move that most closely ties into this Coca Cola outcome is WPP Media’s appointment of Prachi Narayan as Head of Partnerships at Media Futures Group, the bespoke global agency solution for Google. That hire focuses on deepening a large platform relationship in media and content, which sits close to the same AI driven, integrated marketing pitch that underpinned the Coca Cola renewal.
For you as a shareholder, this matters less as a headline change and more as an execution signal. WPP is pushing senior talent into roles that sit directly on top of key data, creator and retail media budgets. At the same time, it is promoting Leanne Smith into a Chief Data Privacy Officer role across CMI Media Group and Compas, which indicates operational focus on compliant, measurable media as a potential support for future catalysts.
What Coca-Cola’s Vote of Confidence Meets in the Numbers
WPP's narrative projects £8.9b revenue and £292.7m earnings by 2029. This sits against analysts assuming a 12.6% yearly revenue decline and an earnings swing of about £532.7m from a £240.0m loss today.
Uncover why WPP's fair value indicates a 4% potential downside to its current price, which leaves little room for error.
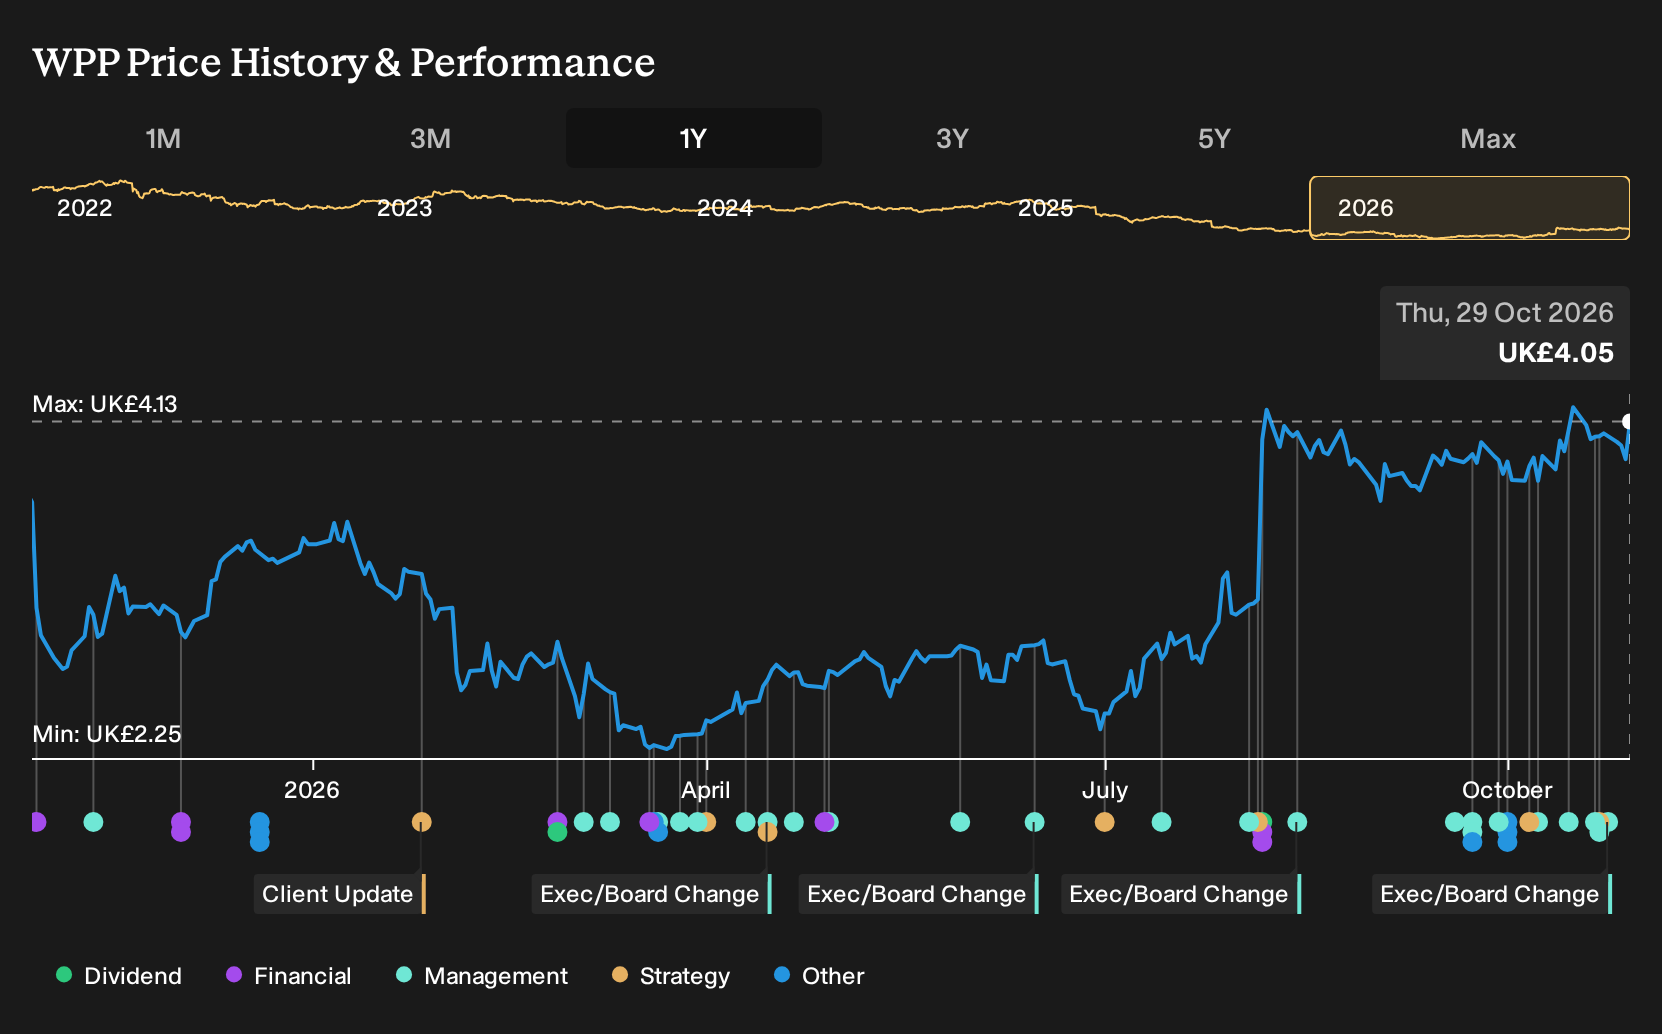
Exploring Other Perspectives
One alternate angle treats Coca-Cola’s renewed commitment and the Prachi Narayan hire as fuel for the bullish revenue story. Before this update, the most optimistic analysts were already pencilling in about £9.3b of revenue and £820.4m of earnings by 2029. That is a very different read on WPP’s potential and a reminder that you can weigh several sharply contrasting forecasts for yourself.
Explore 4 other WPP fair value estimates, including one that suggests potential upside of up to 69% from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your WPP research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for WPP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate WPP's overall financial health at a glance.
Looking for more WPP-like investment ideas?
If Coca-Cola reaffirming WPP has you thinking about concentration risk and where else you might find solid partners, it can help to widen the lens and compare this story with other businesses that match your preferred mix of quality, value and resilience.
- For investors who care most about quality at a sensible entry point, scan a curated 10 high quality undervalued stocks that combine healthier fundamentals with prices that may not fully reflect them.
- If capital protection and steadier profiles matter more to you than chasing every rally, review a focused 5 resilient stocks with low risk scores built around stronger balance sheets and lower risk scores.
- When you want staying power backed by income, especially in uncertain markets, shortlist a hand picked 5 dividend fortresses that pair higher yields with attention to durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com