
Stagwell (STGW) Stock Leans On Margin Gains In Q3 Earnings
Stagwell came into this Q3 2026 print with a stock that had already been grinding higher in recent weeks. Then the release hit and the shares jumped another 12.7% to US$9.95 in regular trading, a sharp move for an advertising and marketing group.
The reputation is that of a leveraged, higher risk agency roll up, but the numbers tell a different story. Net revenue reached US$664m and adjusted earnings before interest, tax, depreciation and amortisation climbed to US$145m with a 21.8% margin. Free cash flow also strengthened. The gap between that thesis and these results is what traders reacted to today.
Impressed by Stagwell’s higher margin profile but still wary of leverage and execution risk in a complex agency roll up? Consider comparing this setup with our list of solid balance sheet and fundamentals stocks (22 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$816.0m vs. US$743.0m (up about 10%)
- Net Income, excl. extra items (Q3 2026 vs Q3 2025): US$18.1m vs. US$24.6m (declined about 26%)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.07 vs. US$0.10 (fell about 23%)
- Adjusted EBITDA Margin (Q3 2026 vs Q3 2025): 21.8% vs. roughly 18.9% (expanded by about 290 basis points)
Prefer clean visuals instead of another wall of numbers and footnotes? See Stagwell’s full financial picture, including how analysts are modelling the business, in the interactive company report for Stagwell.
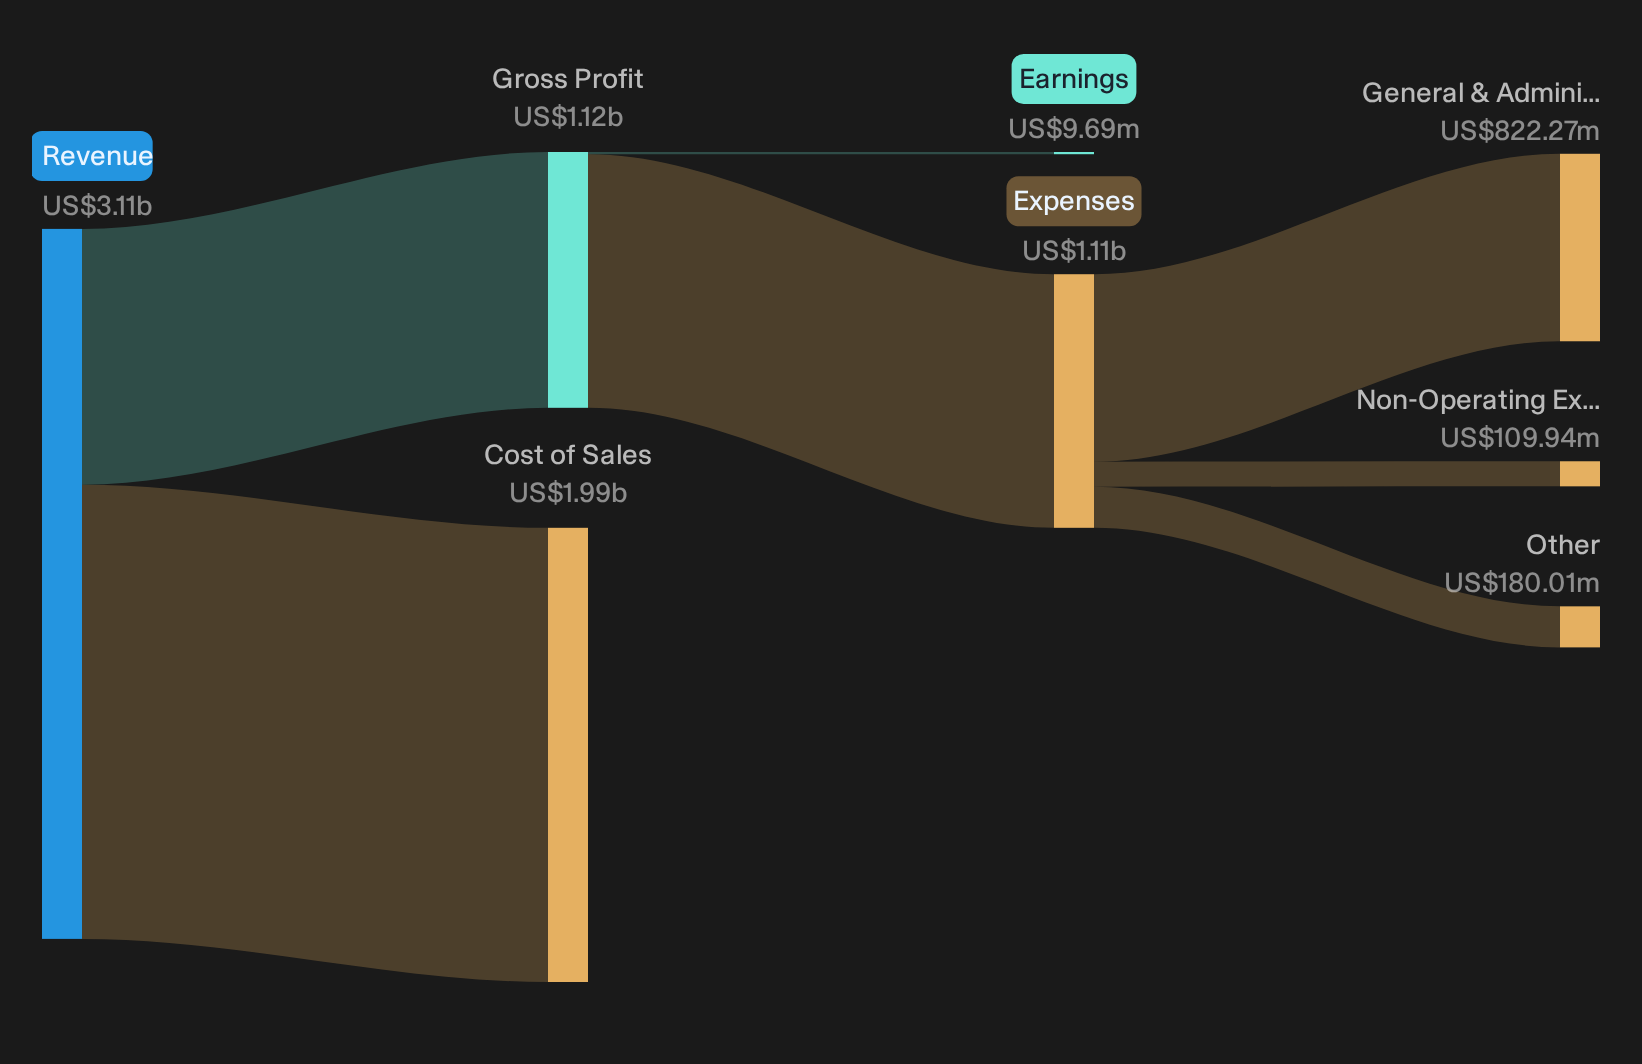
Stagwell’s Bull Story: Contracts, Cloud And Cash
Optimists argue Stagwell can turn its contract wins and software traction into a richer cash mix rather than just higher activity.
"The main thing that has to go right is that Stagwell converts its current momentum in Marketing Cloud, digital transformation, political and government contracts into durable, higher margin cash generation while keeping execution on cost savings on track."
Q3 shows real progress toward that goal. Marketing Cloud net revenue more than doubled, Digital Transformation grew strongly, and Communications benefited from political and advocacy work. Adjusted EBITDA margin reached 21.8% while YTD free cash flow improved and net leverage fell to 2.7x. Execution on cost programs is clearly feeding through, even as GAAP profitability remains a separate hurdle.
Stress Testing Stagwell’s Risk Story On Recurring Revenue
There is also a clear worry that episodic wins and a complex footprint could leave Stagwell exposed when cycles turn.
"The bullish narrative assumes that new public sector and political work becomes a recurring and higher margin stream. However, the recent drag from a stronger US dollar on international results shows how external factors can dilute reported performance."
Q3 partly validates that concern. Political and advocacy demand helped Communications, and federal awards, including exposure to a large U.S. Central Command contract, deepen the public sector foothold. Yet Media and Commerce saw organic decline linked to a Middle East pause and currency was a headwind. Net income excluding extra items fell and GAAP profitability has not yet turned, so the recurring, higher margin story is still unproven.
The price and this Narrative do not agree. → Uncover what this Narrative says Stagwell is actually worth.
Hunt For Mispriced Cash Engines
Stagwell just reminded investors how quickly a narrative can shift once fresh numbers hit the tape. The real opportunity is finding stocks that could be undervalued before the market quietly closes that gap.
- Company 1 - 43% below our estimate - sells large LED systems as more venues and transport hubs adopt software rich, higher margin displays.
- Company 2 - 40% below our estimate - supplies tracking and control hardware as utility scale solar projects add storage and non tracker equipment.
- Company 3 - 32% below our estimate - sells AI chips and software as data centre operators retool capacity for higher power, GPU focused racks.
That is three of the list. See the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com