
Cyberattack Disruption Might Change The Case For Investing In Boston Scientific (BSX)
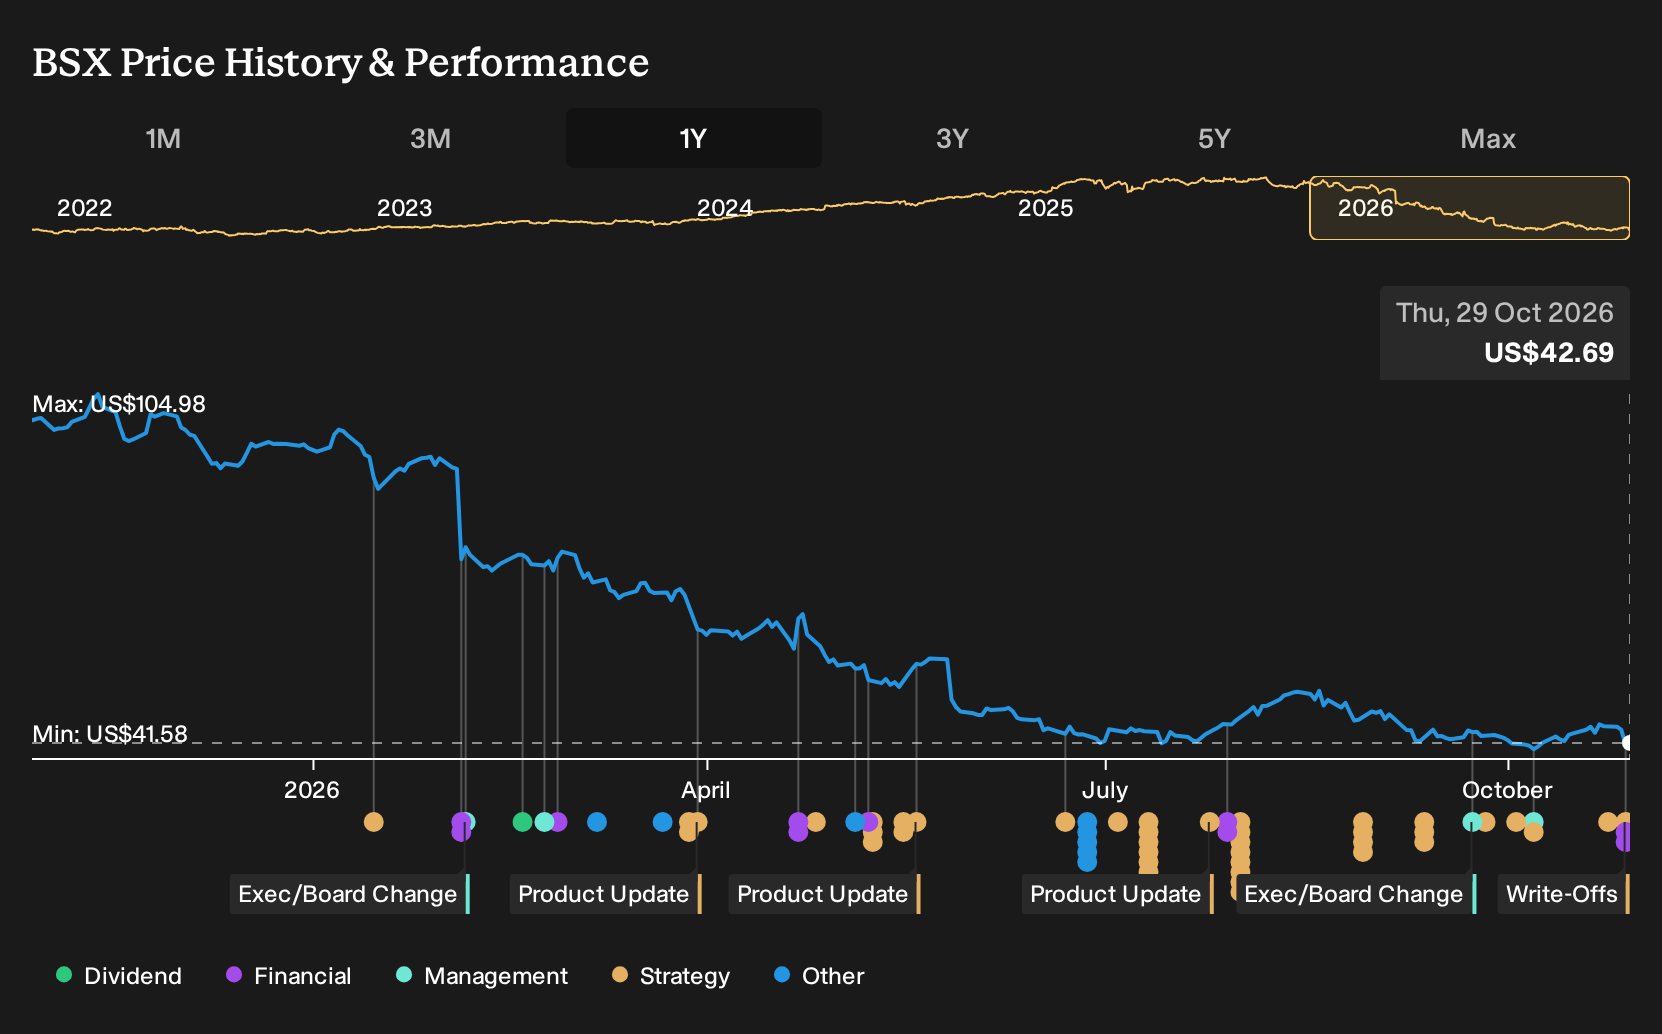
- Boston Scientific reported Q3 2026 results with US$5.14b in sales and US$582m in net income, while also recording US$39m of goodwill and intangible asset impairment charges. The company issued guidance that points to a 1% to 3% decline in Q4 2026 net sales after a cybersecurity incident disrupted operations.
- The firm is dealing with both operational strain from the cyberattack and product specific issues, including weakness in WATCHMAN and electrophysiology lines and a Class II recall of certain NaviFlex LW Pusher and Advx pancreatic stent lots. These challenges together increase execution risk around its existing restructuring and product pipeline plans.
- Next, the focus will be on how this weaker guidance after the cyber incident may reshape the Boston Scientific investment narrative.
Boston Scientific Investment Narrative Recap
To own Boston Scientific, an investor has to believe the broader portfolio and restructuring can absorb near term strain in electrophysiology, WATCHMAN and cyber recovery. The current story is about restoring operations after the cyberattack while keeping MedSurg and interventional cardiology moving. Management is signalling a temporary Q4 sales step back, not a reset to the business model.
The key short term catalyst is execution on the restructuring and cyber remediation so that the 2026 full year guidance around roughly mid single digit sales growth remains credible. The biggest risk is that EP and WATCHMAN softness, combined with operational disruptions, lingers and keeps pressure on mix, margins and earnings longer than intended.
The most relevant recent update is Boston Scientific’s new guidance that Q4 2026 net sales are expected to decline 1% to 3% year on year, while full year 2026 net sales are still guided to grow about 4.25% on a reported basis. That contrast shows how management views the cyber incident as a sharp but contained setback.
For you as a shareholder, the question becomes whether the current weakness in electrophysiology, WATCHMAN and the NaviFlex pancreatic stent recall stays ring fenced or spills into the broader portfolio. If the firm keeps most businesses growing while working through the recall and cyber issues, the planned cost savings, product launches and Penumbra integration remain the main medium term levers.
Boston Scientific’s analyst narrative points to revenues of US$24.4b and earnings of US$4.4b by 2029, based on forecast revenue growth of 5.1% a year and an earnings increase of about US$0.7b from current earnings of US$3.7b.
Uncover why Boston Scientific's fair value indicates a 35% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Not every analyst sees Boston Scientific’s restructuring as the main story. The most pessimistic group worries more about margin pressure. They were already modelling revenue of about US$23.8b and earnings around US$4.1b by 2029 before this cyber and recall news. Their stance could shift again as the full impact becomes clearer. It can be useful to compare several viewpoints before deciding how you feel about the stock.
Explore 6 other Boston Scientific fair value estimates, including one that suggests it could be worth just $44.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own research and judgment.
- A great starting point for your Boston Scientific research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Boston Scientific. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Boston Scientific's overall financial health at a glance.
Looking For More Ideas Beyond Boston Scientific?
Once you have a view on Boston Scientific, it can help to widen the lens and compare it with other healthcare and medical device stocks that fit different risk and income profiles. The Simply Wall St Screener lets you filter by balance sheet strength, valuation and income potential so you can build a watchlist that truly matches your own goals.
- For investors who care most about stability and capital preservation, focus on sturdier balance sheets and measured risk using our 30 resilient stocks with low risk scores.
- If you are hunting for quality businesses that the market might be underpricing, scan for potential value opportunities with the 30 high quality undervalued stocks.
- When you want a blend of income and resilience, filter for reliable payers with stronger yield profiles through the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com