
Ford (F) Stock Rallies On Q3 Earnings As Recall Risks Persist
Ford Motor just posted Q3 2026 earnings, and the first verdict came from the tape. The stock closed at US$12.36, up 3.4% on the day, a sharp move for a mature automaker that has been grinding through a tough 90 day stretch.
The market is cheering a clean headline. Adjusted earnings per share landed at about US$0.51 and adjusted earnings before interest and taxes reached US$2.7b, with management lifting the low end of full year adjusted EBIT guidance. The emotional pop in the share price suggests a relief rally, while the underlying numbers point to a more complicated story about profits, capital intensity and patience.
Love the clean Ford Motor earnings headline but worried about capital intensity and the patience required for a turnaround in autos? Compare the current move with a curated list of sturdier balance sheets and steadier cash generators in our list of solid balance sheet and fundamentals stocks (23 results).
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$49,526m vs. US$50,534m (slight decline year on year)
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): US$2,049m vs. US$2,447m (profit lower than prior year)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.51 vs. US$0.61 (per share earnings down on the prior period)
- Trailing 12 Month Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025 TTM): loss of US$7,794m vs. loss of US$8,182m (trailing loss narrowed slightly)
Earnings can look tidy for a single quarter while the underlying cash engine tells a different story, and valuation focused investors usually care more about the cash coming in than the accounting result.
When you look at Ford Motor's cash flows on their own and map them against the current share price, the stock could be a clear 16% overvalued.
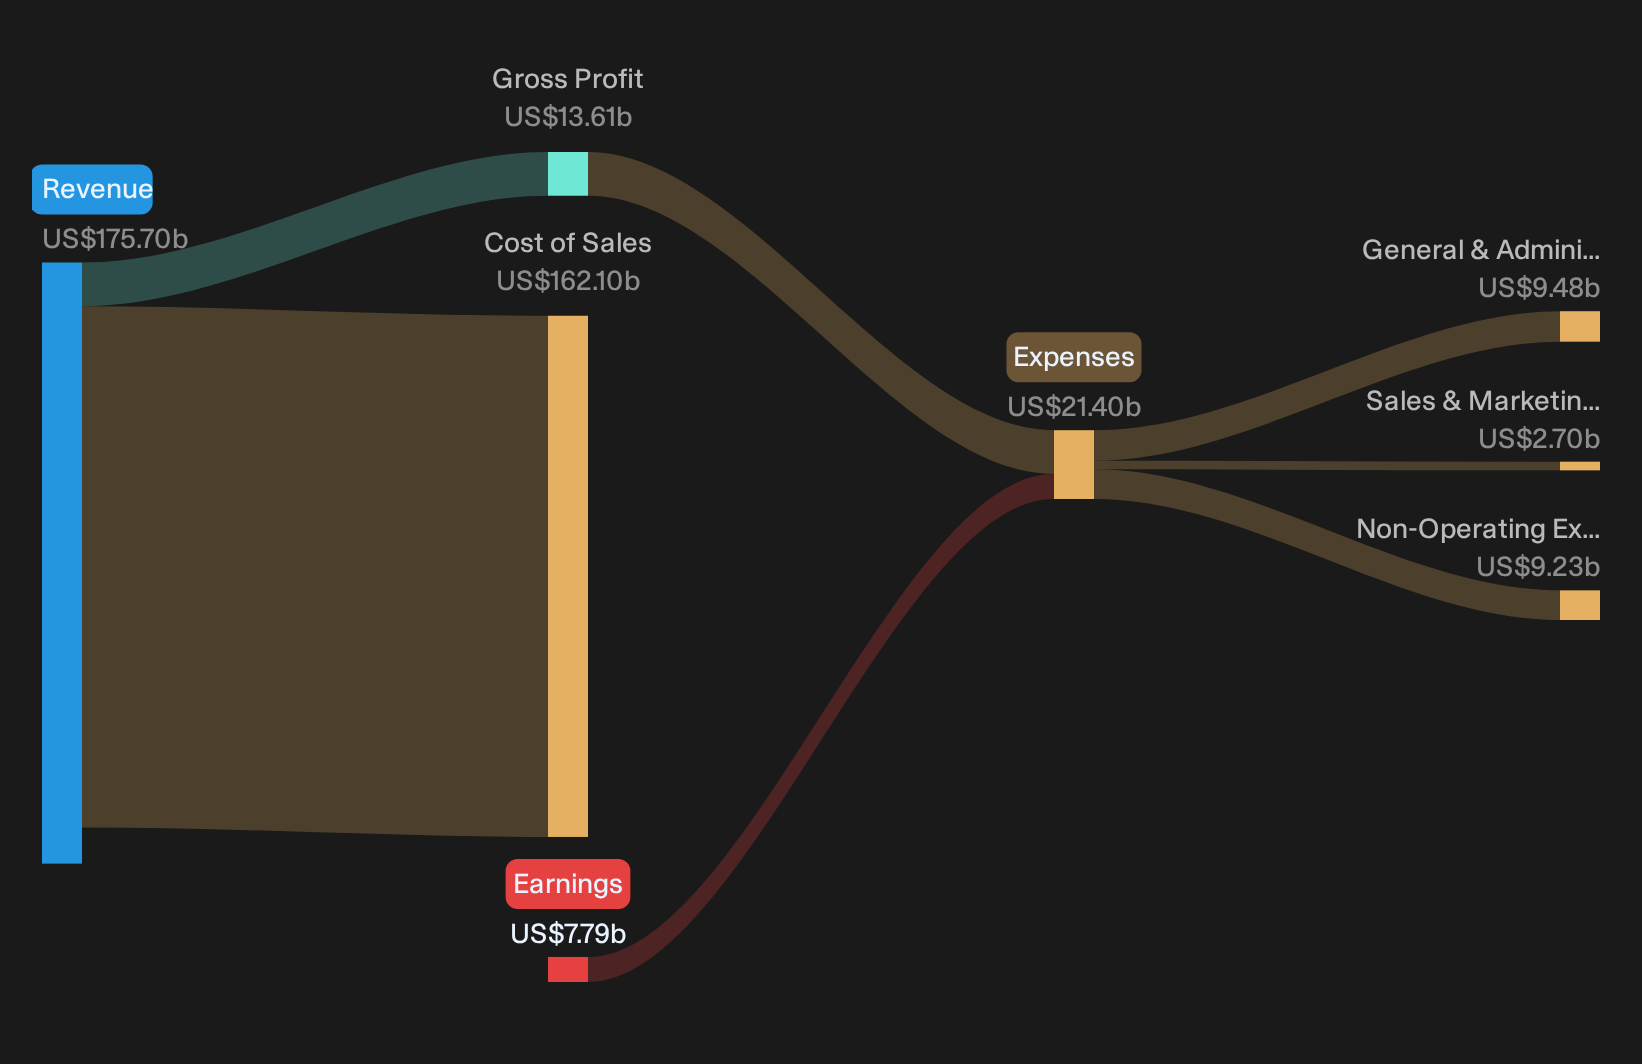
Evaluating Ford’s Software, Energy And Quality Milestones
The upbeat story on Ford Motor rests on newer profit engines doing more of the heavy lifting over time.
"Bullish analysts expect Ford Motor to build on its connected vehicle base, high-margin software subscriptions, and energy storage initiatives so that software, services, and EV-adjacent businesses become a larger profit driver alongside trucks and utilities."
Q3 gives that view some concrete wins. Software and parts reached record revenue and now contribute about 10% of company sales at strong margins. Management also confirmed Ford Energy is meeting factory milestones and has contracts plus late stage negotiations that already cover more than 80% of planned 2028 capacity.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Ford’s Cost Squeeze: Bear Worries Meet Mixed Evidence
Bearish commentary argues that Ford Motor’s quality problems could quietly eat the very cost savings that are supposed to protect margins.
"Yet the recent recall of more than 223,000 F 150 trucks and the continued recall of roughly 12 million vehicles this year show that defect risk remains elevated, which can absorb those planned savings and weigh on net margins."
Q3 adjusted EBIT of US$2.7b and a higher full year target show the cost program is still holding up numerically. At the same time, the large F 150 recalls are real and ongoing. Those actions validate the risk that warranty and repair bills could claw back some of the planned US$1b in 2026 material and warranty cuts, even as mix and software help keep guidance intact for now.
Hunt Quiet Setups Before They Move
Ford Motor just showed how one quarter can shift sentiment without settling every long term question. The real opportunity is spotting stocks that could be undervalued before fresh information resets expectations.
- Company 1 - 31% below our estimate - uses long term optical and solar supply deals so large booked demand can feed a margin focused capacity plan.
- Company 2 - 32% below our estimate - supplies high end AI compute clusters that a headline model provider now relies on to spread workloads across multiple clouds.
- Company 3 - 15% below our estimate - builds power and communications projects that sit directly inside hyperscale data center rollouts, backed by a swelling backlog and no long term debt.
Those are three of them. See every one of the 30 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com