
How Earnings Momentum At Trimble Stock Has Changed Its Investment Story
- Trimble is heading into its next earnings release with analysts pointing to expected quarterly EPS of $0.86 on projected revenue of $965.9 million, supported by prior quarters where reported results came in above consensus estimates.
- The focus now sits on whether Trimble’s track record of outperforming forecasts and its positive Earnings ESP of 1.16% can continue to reinforce confidence in its subscription heavy workflow solutions across construction, engineering and transportation.
- We will look at how Trimble's investment narrative is shaped by this earnings momentum and the positive Earnings ESP signal.
Scan other workflow heavy tech stocks that are showing earnings momentum similar to Trimble with our hand picked 18 high quality undiscovered gems for your next round of research.
Trimble Investment Narrative Recap
To own Trimble, you need to be comfortable with a software heavy, subscription driven workflow story that is still transitioning away from hardware and is not yet profitable on a net income basis. The near term swing factor is execution on connected, AI enabled tools that can keep recurring revenue and margins moving in the right direction while customers adopt more bundled offerings.
The biggest operational risk right now sits in product transitions and controls. The Field Systems refresh is already a drag on reported ARR growth, and any further delay in customer take up could blur the progress Trimble makes elsewhere. Ongoing work to fix governance and accounting weaknesses also remains a key watch item for investors.
The most relevant data point for this earnings focused setup is Trimble’s recent history of beating EPS estimates and carrying a positive Earnings ESP into the November 4, 2026 release. That track record matters because it shapes how much weight investors put on the current guidance around margins and recurring software scale.
If Trimble again reports EPS ahead of the US$0.86 expectation on revenue around US$965.9 million, it would reinforce the idea that execution on connected workflows and subscriptions is tracking to plan. A miss, or softer commentary around Field Systems ARR and the internal controls remediation, would instead refocus attention on the transition risks rather than the catalysts.
Trimble Consensus Forecasts At A Glance
Trimble's narrative includes analyst projections of US$4.8b revenue and US$1.6b earnings by 2029. Analysts are assuming revenue growth of 7.9% per year, and this setup implies an earnings increase of about US$1.7b from a loss of US$104.7m today to the US$1.6b consensus level.
Discover why Trimble's fair value suggests a 23% potential upside to its current price before the market closes the gap.
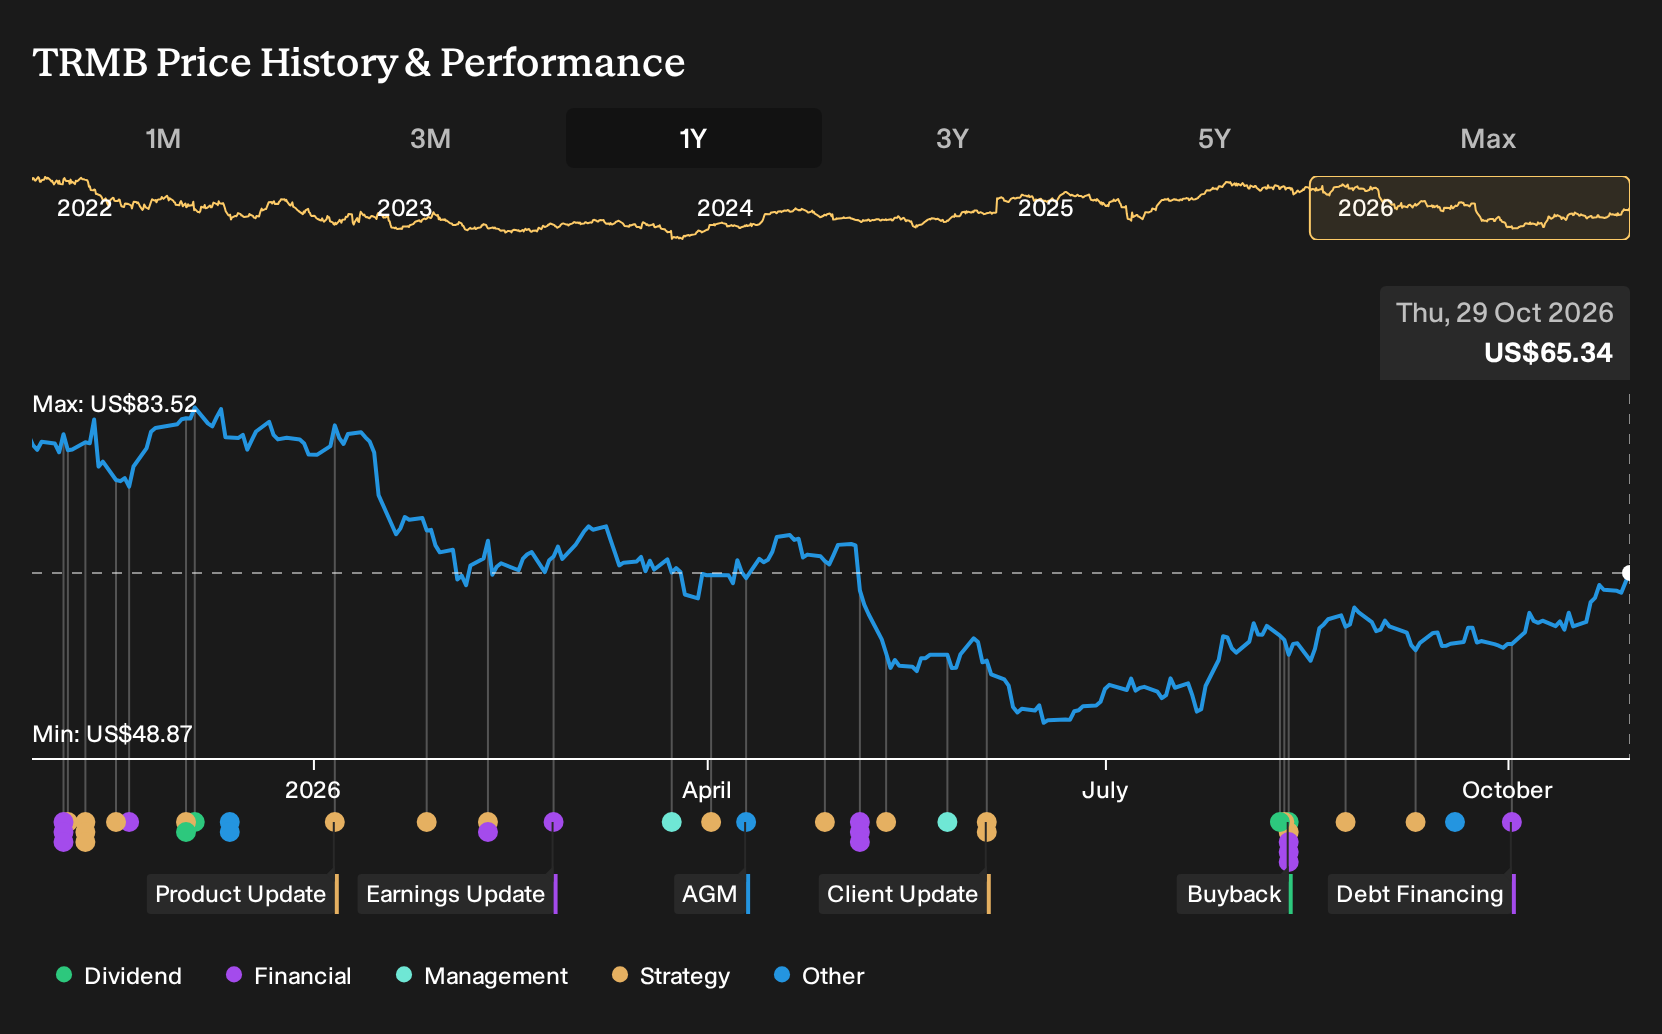
Exploring Other Perspectives
Not every analyst reads Trimble the same way. The most cautious forecasts before this news pencilled in about US$4.8b of revenue and roughly US$1.3b of earnings by 2029, viewing Field Systems drag as the key risk. Those views are far more guarded than the US$1.6b earnings consensus, so use them as a prompt to test your own assumptions.
Explore 2 other Trimble fair value estimates, including one that suggests it could be worth just $80.18!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Trimble research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Trimble. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trimble's overall financial health at a glance.
Looking For More Investment Ideas Beyond Trimble?
Once you have a view on Trimble, it can help to widen the lens and compare it with other businesses that share some of the qualities you care about most, whether that is value, balance sheet strength, or lower perceived risk.
- If you want potential value opportunities backed by solid fundamentals, scan our 30 high quality undervalued stocks that filter for quality alongside attractive pricing.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (23 results) and see which businesses pair healthier finances with consistent fundamentals.
- If capital preservation is a priority, narrow your watchlist with a 30 resilient stocks with low risk scores that highlights companies scoring better on our risk metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com