
O'Reilly Automotive (ORLY) Stock Price Slips As Q3 Results Meet Valuation Doubts
O'Reilly Automotive just reported Q3 2026 and the stock slipped about 2.6% on the day. That move suggests investors are focusing on the share price more than the story beneath it. Headline numbers were solid for an auto parts retailer, with comparable store sales up 7.2% and diluted earnings per share at roughly US$0.97 for the quarter.
The key driver of sentiment was a clash between those operating trends and concern about valuation and leverage. The market treated a strong same store performance as routine and instead reacted to a premium P/E and a balance sheet relying more on debt to fund heavy buybacks.
Love O'Reilly Automotive's steady same store sales but uneasy about a premium P/E backed by rising leverage? Check out our screener of list of solid balance sheet and fundamentals stocks (23 results).
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs Q3 2025): US$5,121.29m vs. US$4,705.70m (up about 8.8%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): US$785.62m vs. US$725.90m (up about 8.2%)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.97 vs. US$0.86 (up about 18.0%)
- Same Store Sales Growth (Q3 2026 vs Q3 2025): 7.2% vs. 5.6% (faster comparable store growth)
O'Reilly is leaning on record debt to fund huge buybacks. Ask Charlie what O'Reilly's buybacks mean for future returns.
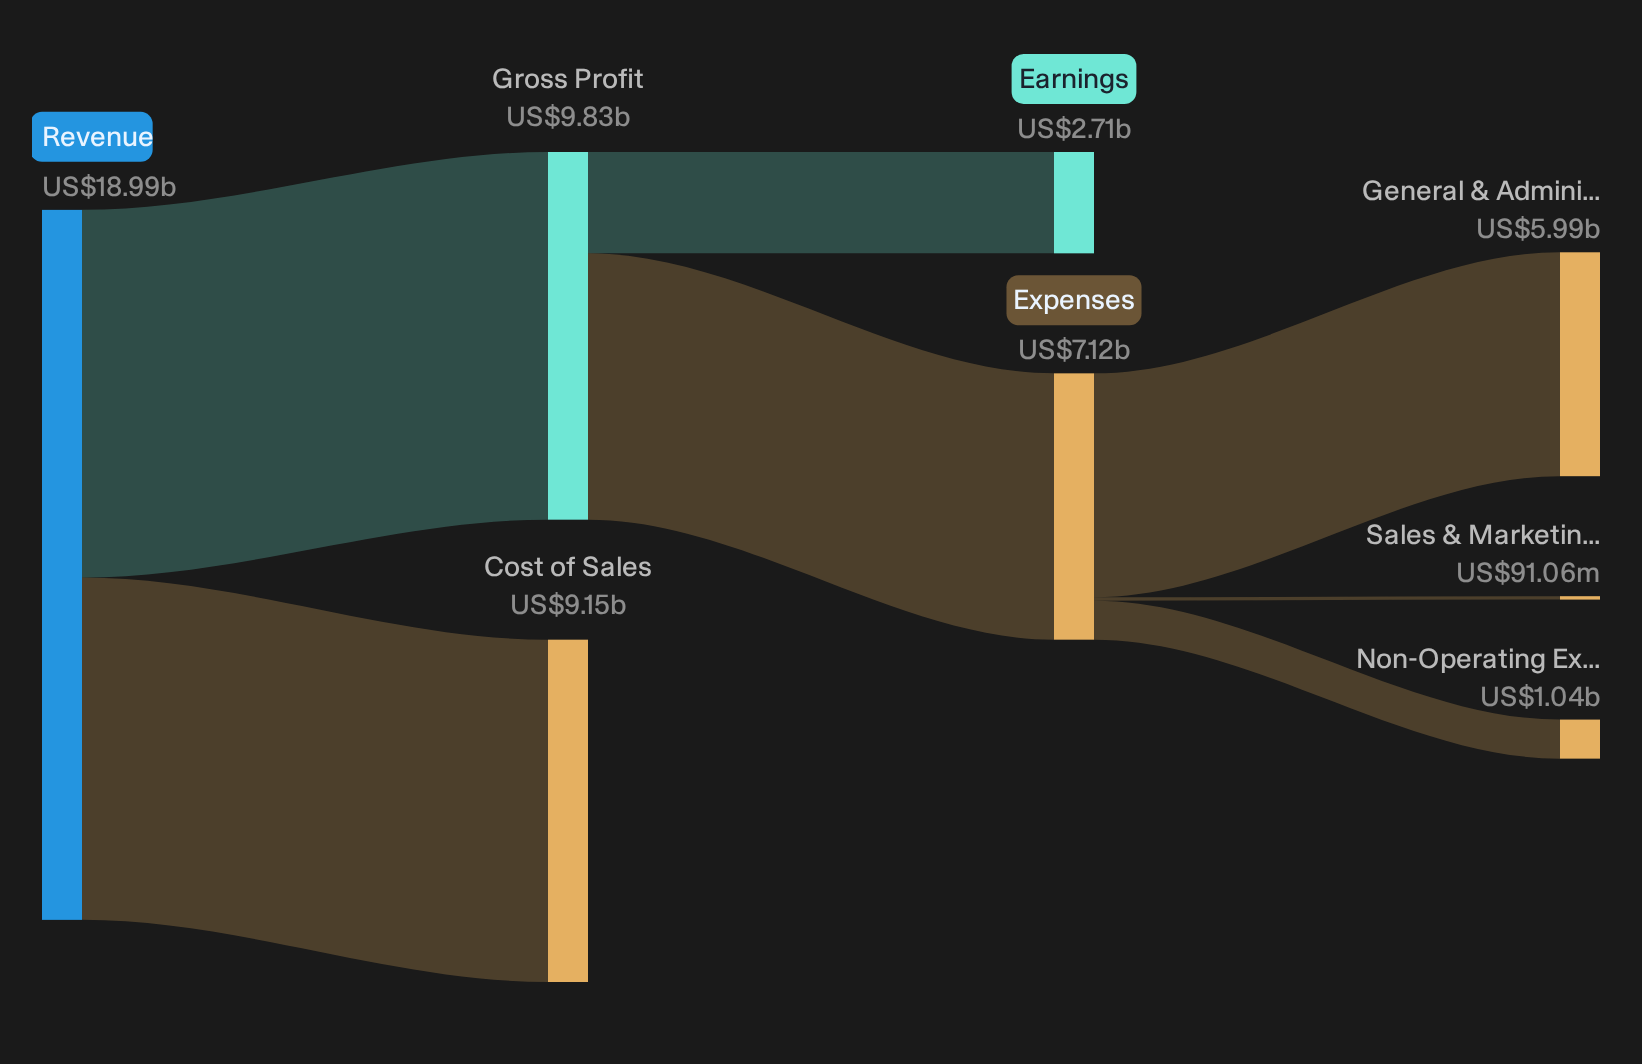
O'Reilly Cash Engine Backs The Bullish Story
Bulls argue that O'Reilly Automotive wins if higher margin professional sales and disciplined costs do the heavy lifting. That ambition is clear.
"The main thing that has to go right is that O'Reilly Automotive continues to grow its higher contribution professional segment while maintaining gross margin stability through private label strength, supply chain flexibility and controlled SG&A per store growth."
Q3 hits several checkpoints. Professional comps ran around 10% with both ticket and transactions contributing. Gross margin improved year on year, helped by a tariff refund plus ongoing acquisition cost gains, and full year margin guidance inched up. SG&A per store is running 4.5% to 5%, yet still leveraged slightly in Q3.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
O'Reilly Bear Case Tests Capital And Deal Strain
Bearish investors worry that O'Reilly Automotive is stretching the balance sheet just as large projects and potential deals ramp up.
"Heavy reliance on private label products for more than 50% of revenue and large distribution investments such as the new Atlanta facility are intended to sustain margin and availability. Yet any slowdown in professional or DIY demand relative to this larger cost base could turn these growth projects into a source of operating deleverage that weighs on gross margin and operating margin."
Q3 results do not show that stress yet. Comps are 7.2% and full year operating margin guidance is higher, helped by a tariff refund. The real miss for this bear story is timing. The new Atlanta facility and any NAPA integration have not hit full scale, while leverage has already moved to 2.26x with US$1.6b of fresh notes and US$3.7b of buybacks year to date. The risk flagged in the quote is not disproved; it just has not been triggered in these numbers.
Hunt For Quiet Mispricings
O'Reilly Automotive just showed how a solid quarter can still leave investors debating valuation and balance sheet risk. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 38% below our estimate - uses an asset light agent network and AI tools to grow higher value freight while tightening carrier vetting.
- Company 2 - 21% below our estimate - leans on increased adoption of surgical robotics and Smart Care services to expand procedure coverage and improve manufacturing efficiency.
- Company 3 - 36% below our estimate - expands high horsepower engine capacity and focuses on data center power contracts while redirecting capital toward core power systems projects.
That is three of the list. See all 30 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com