
Will Casap AI Tie Up Change Experian's (LSE:EXPN) Narrative
- Casap recently closed a $56 million Series B round that included Experian and Synchrony, with Experian working with Casap to test AI agents for fraud detection and dispute handling.
- Experian Health’s 2026 State of Claims report shows providers facing persistent claim denials and growing complexity, while most see AI and automation as central to fixing operational friction.
- We will look at how Experian’s investment narrative around scaled AI platforms is affected by its Casap collaboration on fraud signals.
Scan how Experian’s AI push compares with other data‑focused players by reviewing a curated set of 38 profitable AI stocks that aren't just burning cash that pair automation themes with actual earnings power.
Experian Investment Narrative Recap
To own Experian, you need to believe its data and AI platforms can keep turning a huge information footprint into steadier earnings, even as older revenue streams fade. The short term focus sits on scaling agentic tools like Ascend and RiskOS, and dual run cloud costs are described as having already peaked in FY26, which supports the margin story.
The biggest nearer term risk still looks operational. Large North America data breach contracts are being wound down through FY27, and U.S. mortgage rule changes could trim bureau volumes. The Casap collaboration is directionally helpful for fraud and credit workloads but does not fundamentally change those headwinds yet.
The Casap funding round and Experian’s role in testing AI agents for fraud and disputes fits directly into the firm’s wider AI platform push. It aligns with products such as Agent Trust and Model Risk Manager and supports the idea that more of Experian’s decisioning can sit in automated workflows rather than batch style reports.
For catalysts, the key angle is how additional fraud and consumer intent signals from Casap could feed into credit, consumer services and Experian Health. If those richer datasets integrate cleanly into Ascend or RiskOS and contribute to higher client usage, they could help offset pressure from winding down breach contracts and any future mortgage rule changes.
Experian's narrative projects US$10.6b revenue and US$2.0b earnings by 2029. This projection is based on analysts using a 7.9% yearly revenue growth rate and an earnings increase of about US$500m from US$1.5b today.
Discover why Experian's fair value indicates a 25% potential upside to its current price that may not last much longer.
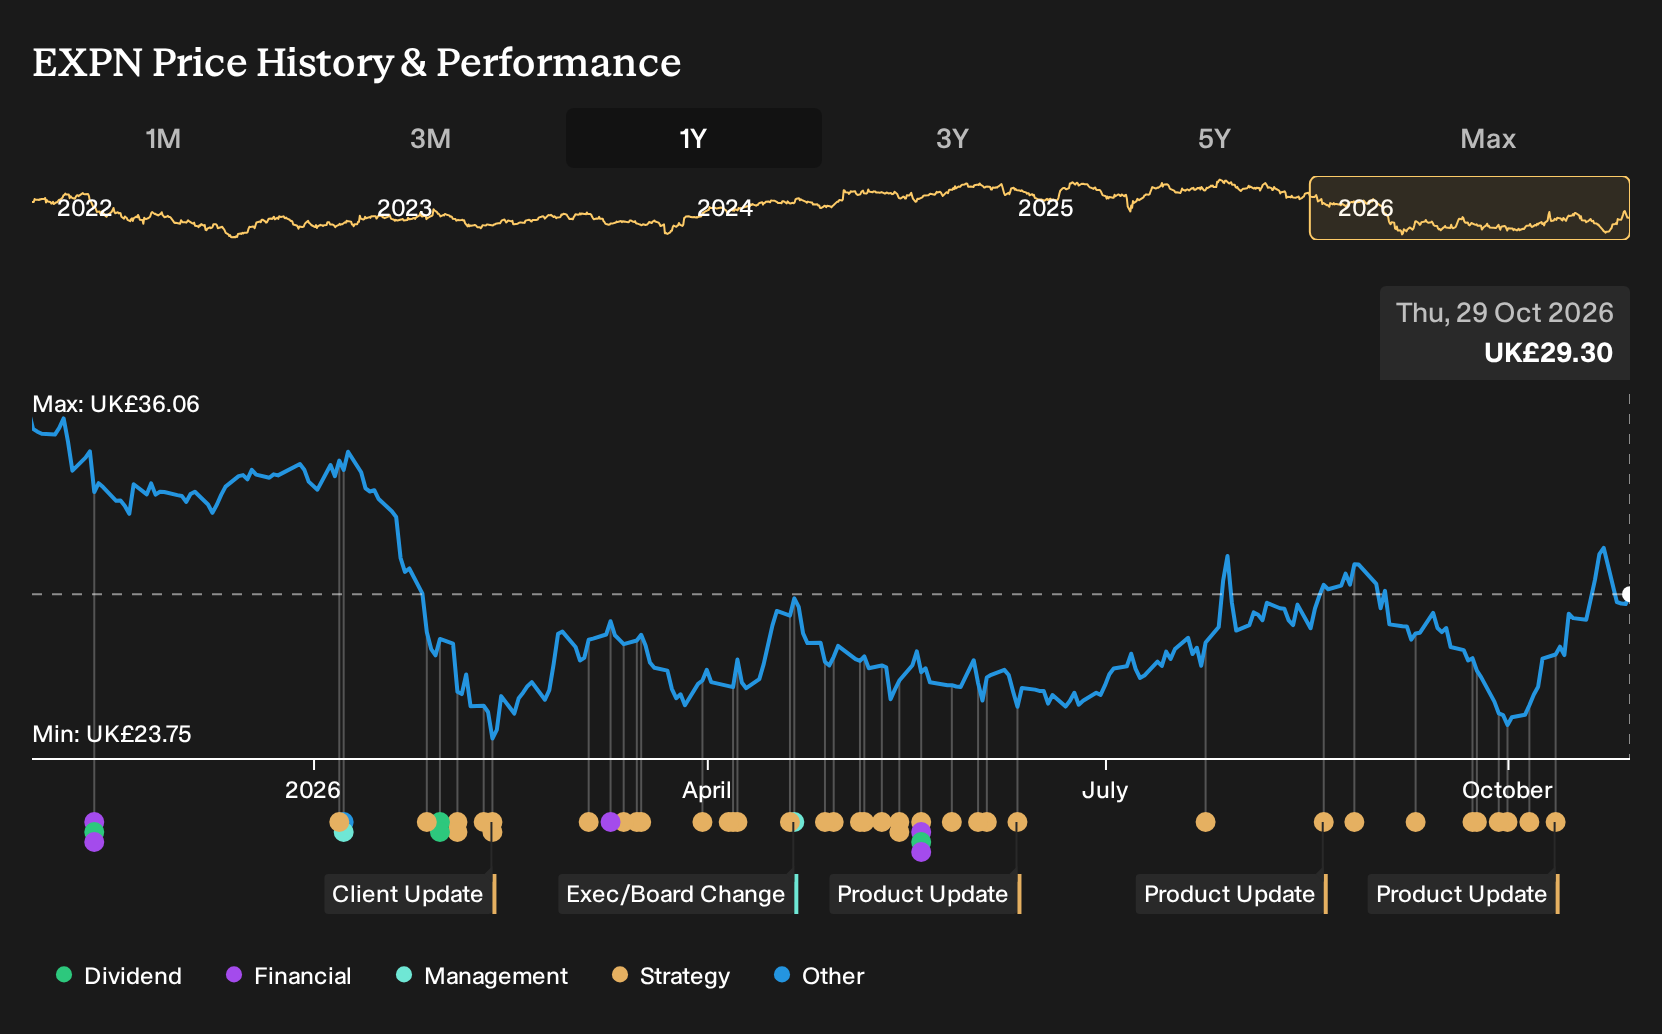
Exploring Other Perspectives
One alternate view on Experian focuses heavily on cost risk. The most cautious analysts worry that increased AI R&D and cloud spending could weigh on profitability, even with Casap style projects. Before this funding news, they were estimating about US$10.3b in revenue and US$2.1b in earnings for 2029, with a much lower implied P/E. That gap shows how widely opinions can differ, so it makes sense to explore several viewpoints before deciding where you stand.
Explore 4 other Experian fair value estimates, including one that suggests it could be worth just £33.12.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Experian research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Experian. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Experian's overall financial health at a glance.
Looking for more Experian style investment ideas?
If the Experian story has you thinking about where else data, quality and resilience might intersect, the Simply Wall St Screener can help you cast a wider net across the market in a structured way.
- If you prefer resilience over drama and want businesses with steadier profiles, low volatility and stronger fundamentals, start with our 5 resilient stocks with low risk scores that focuses on durability first.
- If balance sheet strength is your priority and you want companies with cleaner debt profiles and healthier liquidity metrics, filter for candidates using the list of solid balance sheet and fundamentals (10 results) to narrow the field.
- If you are hunting for quality that is not already crowded and looking for businesses with solid fundamentals that the market may not be paying full attention to, scan through our 5 high quality undiscovered gems to spot under-the-radar options.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com