
Should Earnings Beat Require Action From IDEX Stock Investors?
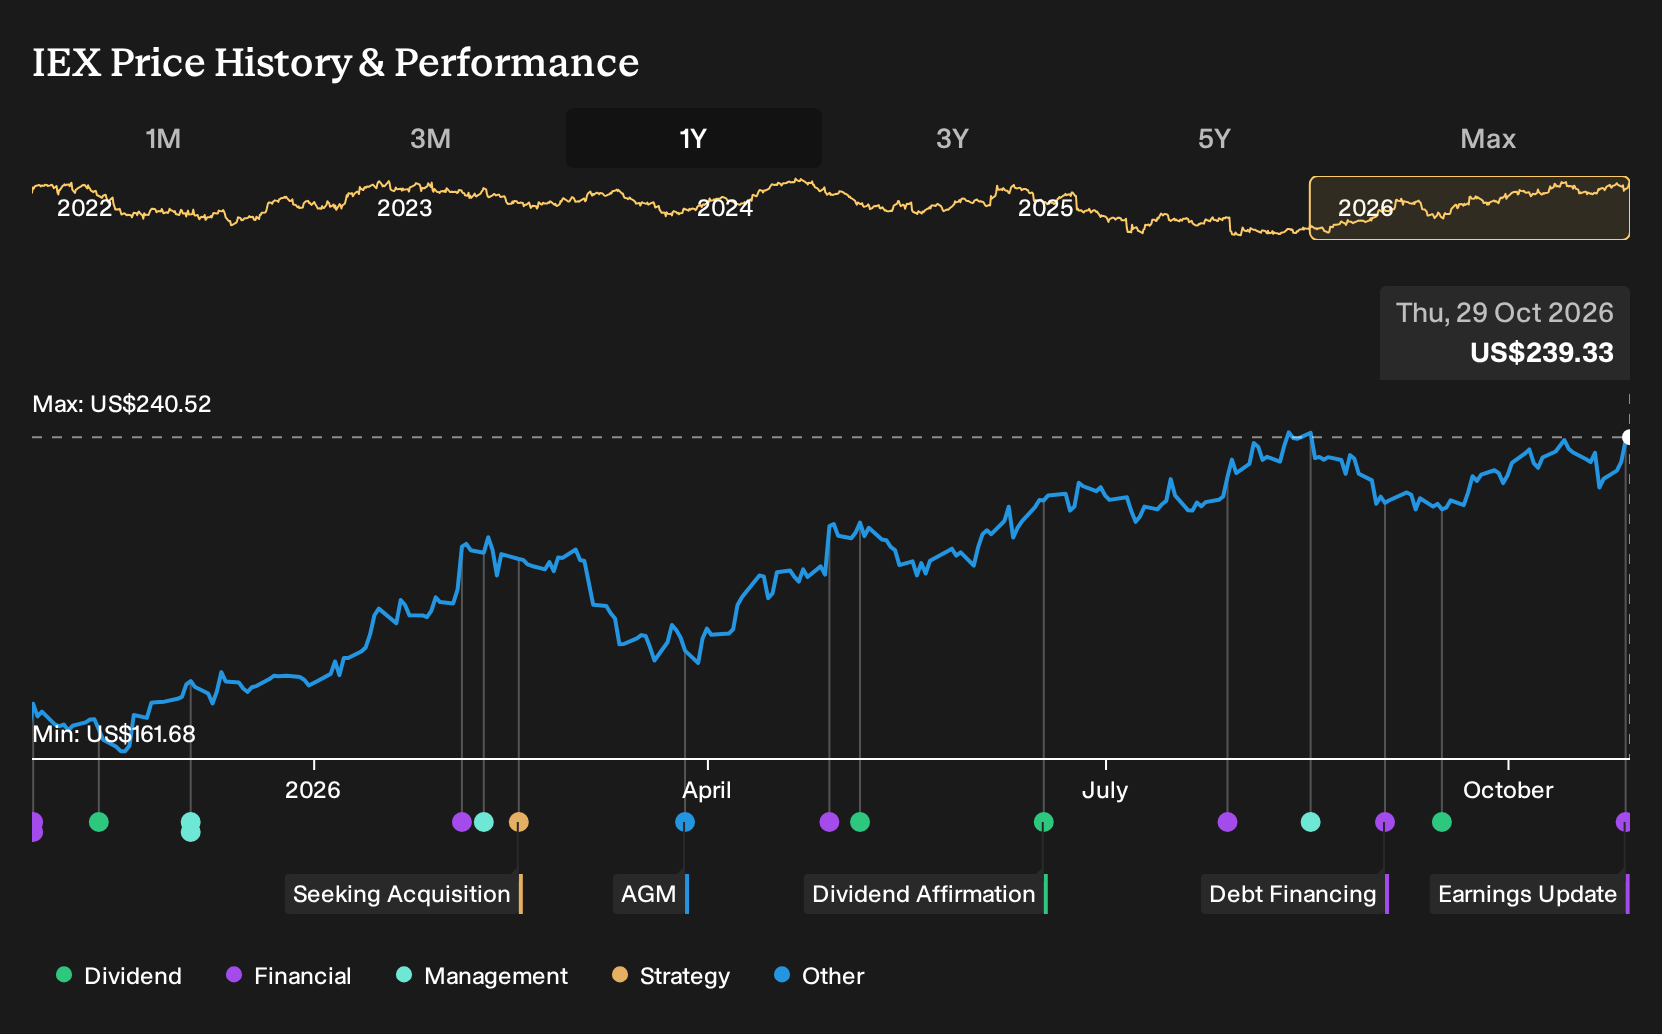
- IDEX Corporation reported Q3 2026 sales of US$951.7 million and net income of US$144.1 million, with adjusted EPS above analyst expectations and management lifting full year guidance.
- Health & Science Technologies remained the engine, delivering double digit segment expansion and strong orders that supported record quarterly sales and higher adjusted profitability.
- The next area of focus will be how IDEX's raised full year outlook reshapes the existing investment narrative built around growth led by the Health & Science Technologies segment.
Scan how IDEX’s earnings beat compares with other industrials showing strong fundamentals and potential momentum by reviewing the curated list of solid balance sheet and fundamentals (23 results).
IDEX Investment Narrative Recap
To own IDEX, you need to be comfortable with a story built around higher value niches like data centers, semiconductors, and Health & Science Technologies driving the mix. The recent Q3 beat, record sales, and raised guidance support that narrative in the near term. The key short term catalyst is execution on this HST led backlog and capital spend, turning strong orders into sustained revenue and margin resilience.
The biggest near term risk is that policy or geopolitical shocks cool the current order strength and disrupt supply chains, especially after a period of higher capital spending and record backlog. If that happens, the shift toward higher value markets and the 8020 focus might not fully offset pressure in older segments. That could leave margins and earnings below what many investors are implicitly baking in.
The most relevant announcement is management lifting full year 2026 adjusted EPS guidance after Q3 2026 results, with adjusted EPS of US$2.33 versus US$1.95 GAAP, sales of US$951.7 million, and net income of US$144.1 million. That change speaks directly to how leadership sees the current run rate of demand and cost discipline across segments, especially Health & Science Technologies.
For you, the raised outlook ties back to the existing catalysts: record backlog above US$1b, strong HST orders in areas like data centers and semiconductors, and increased capex aimed at higher returning projects. It also sharpens the risk reward trade off. If orders slow or legacy pressures persist, the gap between the upgraded guidance and actual delivery would become the pressure point to watch most closely.
IDEX's analyst narrative points to forecast revenues of US$4.4b and earnings of US$781.0 million by 2029, based on assumed annual revenue growth of 6.7% and an earnings increase of about US$261.5 million from current earnings of US$519.5 million.
Uncover how IDEX's fair value indicates a 7% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$255.93 and US$282.73, which already shows how retail views on IDEX can spread out, even in a tiny sample. Compare those pre-earnings views with the raised 2026 guidance and policy risks, then explore more Community opinions before forming your own stance.
Explore another IDEX fair value estimate, including one that suggests it could be worth just $255.93.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and instincts.
- A great starting point for your IDEX research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for IDEX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IDEX's overall financial health at a glance.
Looking for more investment ideas beyond IDEX?
If you like the structure behind IDEX but want a wider bench of opportunities, a focused stock list can help you quickly spot setups that fit your own risk and return preferences.
- If capital protection is front of mind, start with companies that pair resilient balance sheets with healthier fundamentals through the 30 resilient stocks with low risk scores.
- For income oriented investors, scan for businesses targeting higher yields and robust payout profiles using the 7 dividend fortresses.
- If you want potential mispricing on your side, review a curated group of quality stocks that screen as attractively valued via the 30 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com