
Is Earnings Optimism Altering The Investment Case For Global Payments Stock?
- Analysts recently turned more optimistic on Global Payments ahead of its September 2026 quarter results, which are expected to show higher earnings and revenue, with an Earnings ESP of 1.25% cited as a key indicator before the report on 5 November 2026.
- The shift in expectations highlights how closely investors are watching Global Payments’ ability to convert its payment technology and software model into stronger profitability and scale.
- We will now explore how Global Payments’ investment narrative could be influenced by rising confidence in its near term earnings power.
Scan how Global Payments fits into the wider fintech earnings story by comparing it with 30 high quality undervalued stocks that also pair payment-driven revenue models with stronger balance sheets and cash flows.
Global Payments Investment Narrative Recap
To own Global Payments, you need to believe its payment technology, software and AI tools can steadily turn transaction volume into durable cash generation, even as the Worldpay deal reshapes the group. The near term story hinges on whether earnings quality cleans up from past one off items and margins stabilize after the recent reset.
The upcoming September 2026 quarter is the key near term checkpoint. Stronger EPS on higher sales would support the thesis that integration work, Genius rollout and AI products are tracking to plan. The biggest risk remains execution on Worldpay synergies and higher funding and compliance costs, which could keep profitability and interest coverage under pressure.
There have been no fresh operational announcements tied directly to this earnings setup, so the most relevant reference point is still management’s previously reiterated Worldpay synergy targets and capital return goals. Those plans anchor how investors frame Global Payments today and shape what they listen for on November’s call.
Your focus should stay on whether management talks to progress on the US$600m cost and US$200m revenue synergy run rate by 2028, and whether free cash flow conversion is still expected above 90% for 2026. Any change to that cadence, or to the timing of travel related headwinds easing, will likely matter more than a single quarter’s headline beat or miss.
What Analysts Are Baking Into Global Payments' 2029 Story
Forecasts around Global Payments now hang on a fairly specific 2029 setup. Analysts are pencilling in US$13.9b of revenue and US$2.1b of earnings by that year, underpinned by an assumed 10.8% annual increase in sales and a move in profit margins from 4.8% today to 15.2% over roughly three years. That path implies a material lift in earnings power relative to current levels, even as the Worldpay integration, higher compliance spend and funding costs remain key swing factors for how much of that profit actually shows up in the income statement.
Global Payments' narrative projects US$13.9b revenue and US$2.1b earnings by 2029. This requires 10.8% yearly revenue growth and an earnings increase of about US$1.6b from US$494.2m today.
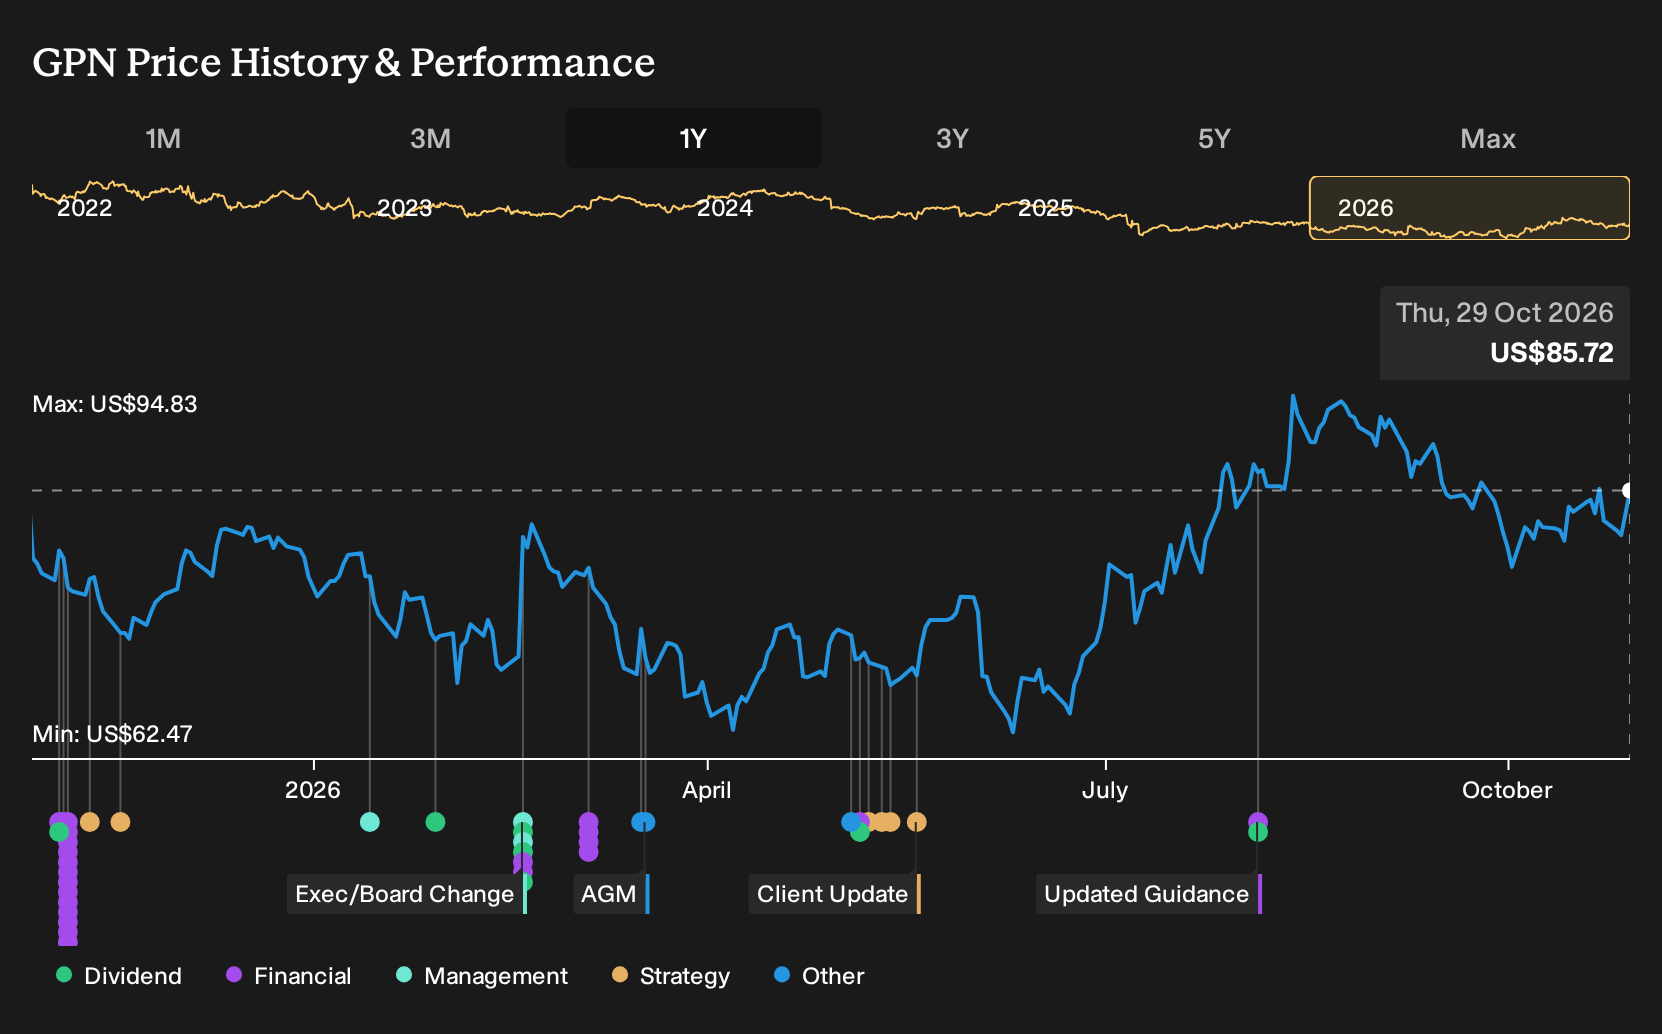
Consensus numbers also assume a changing capital structure for shareholders. Analyst models point to share count expanding by roughly 7% per year over the next three years. This means part of the earnings ramp first has to offset dilution before it can add to earnings per share. Against that backdrop, the current US$81.08 share price is being measured against a US$105.00 average target. The market is being asked to accept a P/E that could compress from 43.4x today to 20.9x on those 2029 earnings while still sitting above the 16.9x multiple used for the wider US diversified financial peer group.
Uncover why Global Payments' fair value indicates a 22% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One bullish twist on Global Payments focuses on the upside from Worldpay synergies. The most optimistic analysts were pencilling in about US$14.8b of revenue and US$4.4b of earnings by 2029 before this earnings ESP news, far above consensus, so investors can use this quarter’s update to test which storyline they find more convincing.
Explore 3 other Global Payments fair value estimates, including one that suggests potential upside of as much as 180% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Global Payments research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Global Payments. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Global Payments' overall financial health at a glance.
Looking For More Global Payments Investment Ideas?
If the Global Payments story has you rethinking where earnings quality and balance sheet strength really matter, it can help to scan a wider field of opportunities using the Simply Wall St Screener.
- For investors who care most about durable businesses with strong finances, start with a curated list of solid balance sheet and fundamentals (23 results) that can handle tougher conditions without leaning heavily on new capital.
- If smoother ride potential matters more than big swings, sort through a focused 30 resilient stocks with low risk scores that screens for resilience across key fundamentals and risk indicators.
- Those hunting for overlooked opportunities can survey a targeted 18 high quality undiscovered gems where solid fundamentals have not yet attracted widespread attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com