
3 Eurozone Financial Stocks Investors May Reprice If ECB Rate Signals Change
Eurozone banking stocks sit in the crosshairs as the ECB scrambles to replace Christine Lagarde while inflation refuses to quietly fade. Policy uncertainty can punish the unprepared and reward investors who understand which businesses might benefit from different interest rate paths. This article walks through three Eurozone financials that appear particularly exposed to the current ECB leadership race and explains why each could matter for portfolio decisions.
The stocks covered below are only a starter set, and the full Eurozone Banks and Financials screen surfaced another 20 listed institutions with equally compelling stories that are not unpacked in this article. If you want to identify where your strongest ideas might sit right now, head straight to the Eurozone Banks and Financials screener to filter and analyze the wider universe of candidates.
CrediaBank (ATSE:CREDIA)
CrediaBank plugs directly into the Eurozone Banks and Financials theme as a Greece based lender whose earnings are closely linked to ECB policy and peripheral spreads, while still looking like a straightforward everyday bank for consumers and businesses.
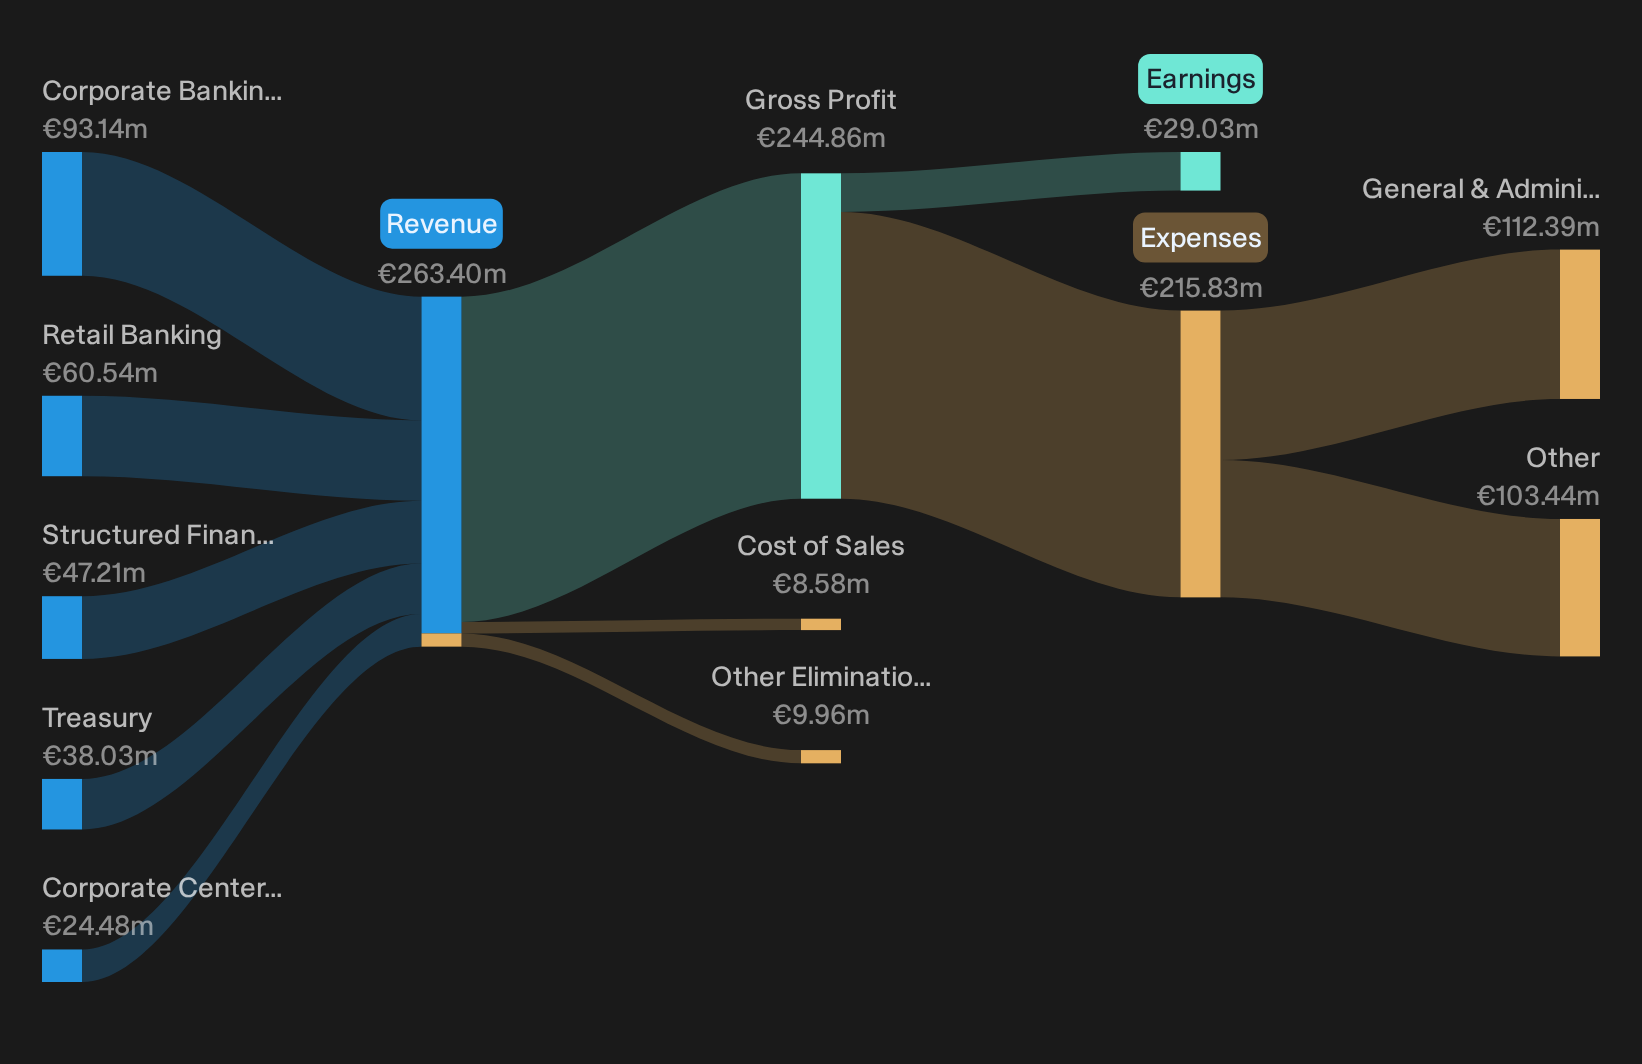
CrediaBank runs a largely domestic franchise across Greece, earning about €93 million from corporate banking, €61 million from retail clients, €47 million from structured financing and €38 million from its treasury arm, with a market value of roughly €2.1b.
"The rapid shift in CrediaBank’s revenue mix toward fees, with fee income already at €11 million in Q1 2026 and 18% of recurring operating income, creates room for future product launches in brokerage, wealth management and bancassurance that could lift non interest revenue and smooth net margins."
The real tension for margins and growth now rests on how one less visible policy driven pressure eventually feeds through to that evolving fee engine.
That pressure point is exactly where CrediaBank’s story gets interesting. Go straight to the full narrative for CrediaBank to see how those fee engines and rate risks really interact.
Assicurazioni Generali (BIT:G)
Assicurazioni Generali brings the Eurozone Banks and Financials theme into the insurance and asset management space, giving you an Italy based heavyweight whose returns are closely tied to ECB rate signals, sovereign spreads and how efficiently it turns premiums and fees into profit.
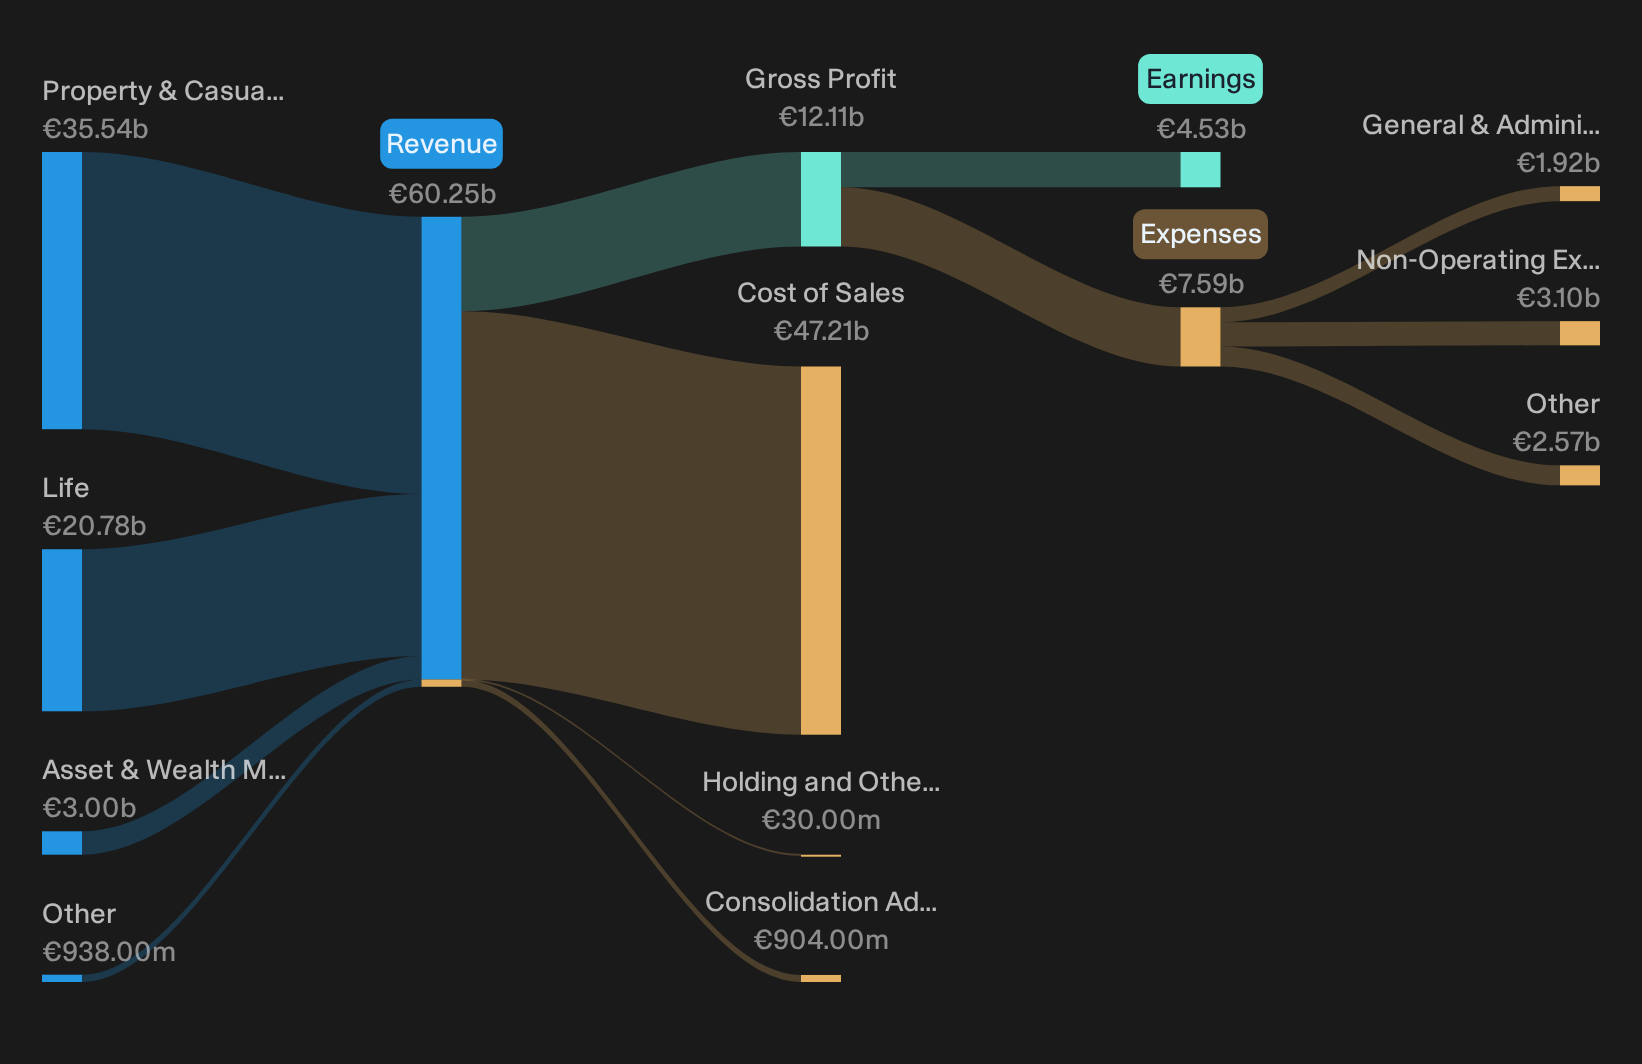
Assicurazioni Generali runs a broad insurance and investment toolkit, earning about €35.5b from Property & Casualty, €20.8b from Life and €3.0b from Asset & Wealth Management, with a small loss in Holding and Other and a market value near €64.2b.
"As Assicurazioni Generali pushes group wide AI and data projects towards a raised efficiency target of more than €350m by 2027, any shortfall in actually capturing these savings could leave the higher P&C acquisition cost ratio and acknowledged expense pressure largely intact. That in turn would cap improvements in the expense ratio and net margins."
What really matters now is how one unresolved pressure point in this plan reshapes the balance between steady payouts and future earnings power.
That trade off between today’s payouts and tomorrow’s earning power is exactly what the full narrative for Assicurazioni Generali unpacks, highlighting where expense pressure could be masking upside.
Bank of Ireland Group (ISE:BIRG)
Bank of Ireland Group plugs directly into the Eurozone Banks and Financials theme as a large Dublin based lender and insurer, earning about €2.1b from Retail Ireland, €1.2b from Corporate and Commercial, €545 million from Retail UK and €422 million from Wealth and Insurance, with a market value near €17.7b.
For investors who want direct ECB policy exposure through a mainstream Eurozone lender, Bank of Ireland Group offers that connection through everyday mortgages, business finance and wealth products rather than complex trading books. This makes the next phase of its fee story especially important.
"The bank anticipates a significant rise in assets under management (AUM) especially in its Wealth and Insurance business, with expectations for 30% growth in AUM over the next three years, which should boost fee income and earnings due to the capital-light nature of this income stream."
What happens to those longer term earnings targets if a single policy driven assumption around that profit mix quietly starts to shift?
If that assumption is starting to quietly shift, the full narrative for Bank of Ireland Group shows how Bank of Ireland Group’s fee engine could decouple from policy and re rate faster.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. Breakout stories gain momentum while slower money gets caught reacting late. Use curated stock lists to find under the radar opportunities while it matters, then act now.
- Spot under followed income opportunities and use the 228 dividend fortresses to focus on listed businesses aiming to pair strong payouts with balance sheets that look built to withstand stress.
- Track where early AI profits are already showing up and run through the 38 profitable AI stocks that aren't just burning cash to narrow in on cash generative players rather than hype driven stories.
- Position ahead of potential infrastructure spending shifts and scan the 43 power grid technology and infrastructure stocks to concentrate on companies tied to grid upgrades, transmission assets and critical hardware.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com