
Will Revenue Growth Change Lisi Stock's Narrative For Lisi (ENXTPA:FII)
- Lisi S.A. reported third quarter 2026 revenue of €473.2 million and nine month revenue of €1,416.0 million, compared with €419.5 million and €1,311.2 million a year earlier.
- The latest top line figures highlight that Lisi S.A. is adding scale across its operations, which increases the emphasis on cost discipline, pricing power and order quality rather than just headline volume.
- This section examines how Lisi S.A.'s higher third quarter revenue influences the investment narrative and the longer term business story.
Compare Lisi's latest revenue momentum with a handpicked 195 high quality undervalued stocks that also pairs growing top lines with disciplined balance sheets.
What Is Lisi's Investment Narrative?
The big picture for a shareholder in Lisi is fairly simple. You need to believe this is an industrial group that can convert its aerospace and automotive exposure into consistent cash generation through cycles, helped by disciplined execution rather than sheer volume. The third quarter revenue of €473.2 million and nine month figure of €1,416.0 million fit that story by reinforcing that demand is there, which keeps attention firmly on pricing, cost control and capital spending.
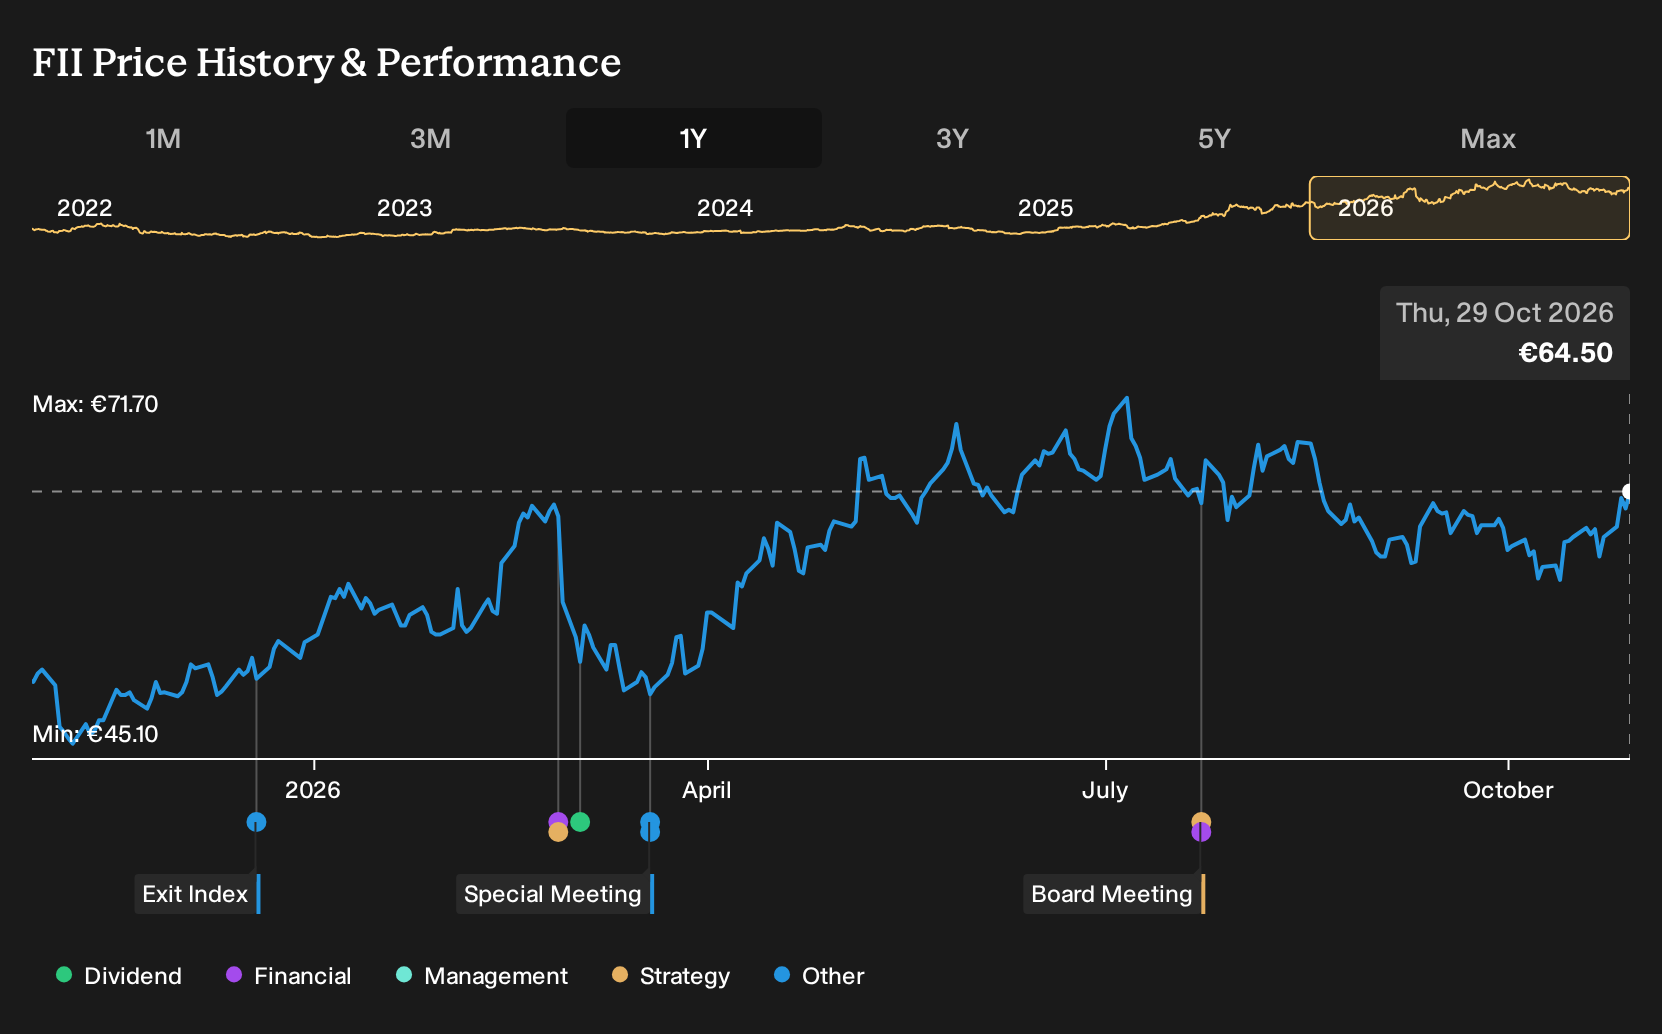
In the short term, the latest trading statement speaks directly to the key catalysts. Earnings have been growing quickly, forecasts imply further profit expansion and the stock has already delivered a 1 year total return of 28.69%. Against that, a P/E of 31.5x and reliance on higher risk funding sources leave little room for operational missteps. Large one off items in recent financials also matter more when expectations are high.
Even so, there is a quieter issue around Lisi that only really comes into focus when you look closely at ...
There's only one way to know the right time to buy, sell or hold Lisi. Head to Simply Wall St's company report for the latest analysis of Lisi's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between €76.14 and €84.54, which already shows how far opinions on Lisi can stretch. These views were formed before the latest revenue update, so treat them as a pre event snapshot and use them as a springboard to test your own assumptions about the stock.
Explore another Lisi fair value estimate, including one that suggests it could be worth just €76.14.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Lisi research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lisi. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lisi's overall financial health at a glance.
Looking For More Ideas Beyond Lisi?
If you want to stress test your thesis on Lisi and see how it stacks up against other opportunities, the Simply Wall St Screener can surface companies that share similar qualities or offer a different risk and return profile.
- For investors who care most about robust finances and durable balance sheets, start with a list of solid balance sheet and fundamentals (207 results) that can handle tougher conditions.
- If capital preservation sits high on your list, scan a 228 resilient stocks with low risk scores that aims to keep volatility in check.
- When you want to widen the opportunity set and look for under-followed stories, a 607 high quality undiscovered gems can help you spot candidates that the crowd may be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com