
Does Earnings Beat Change The Bull Case For InterDigital Stock (IDCC)?
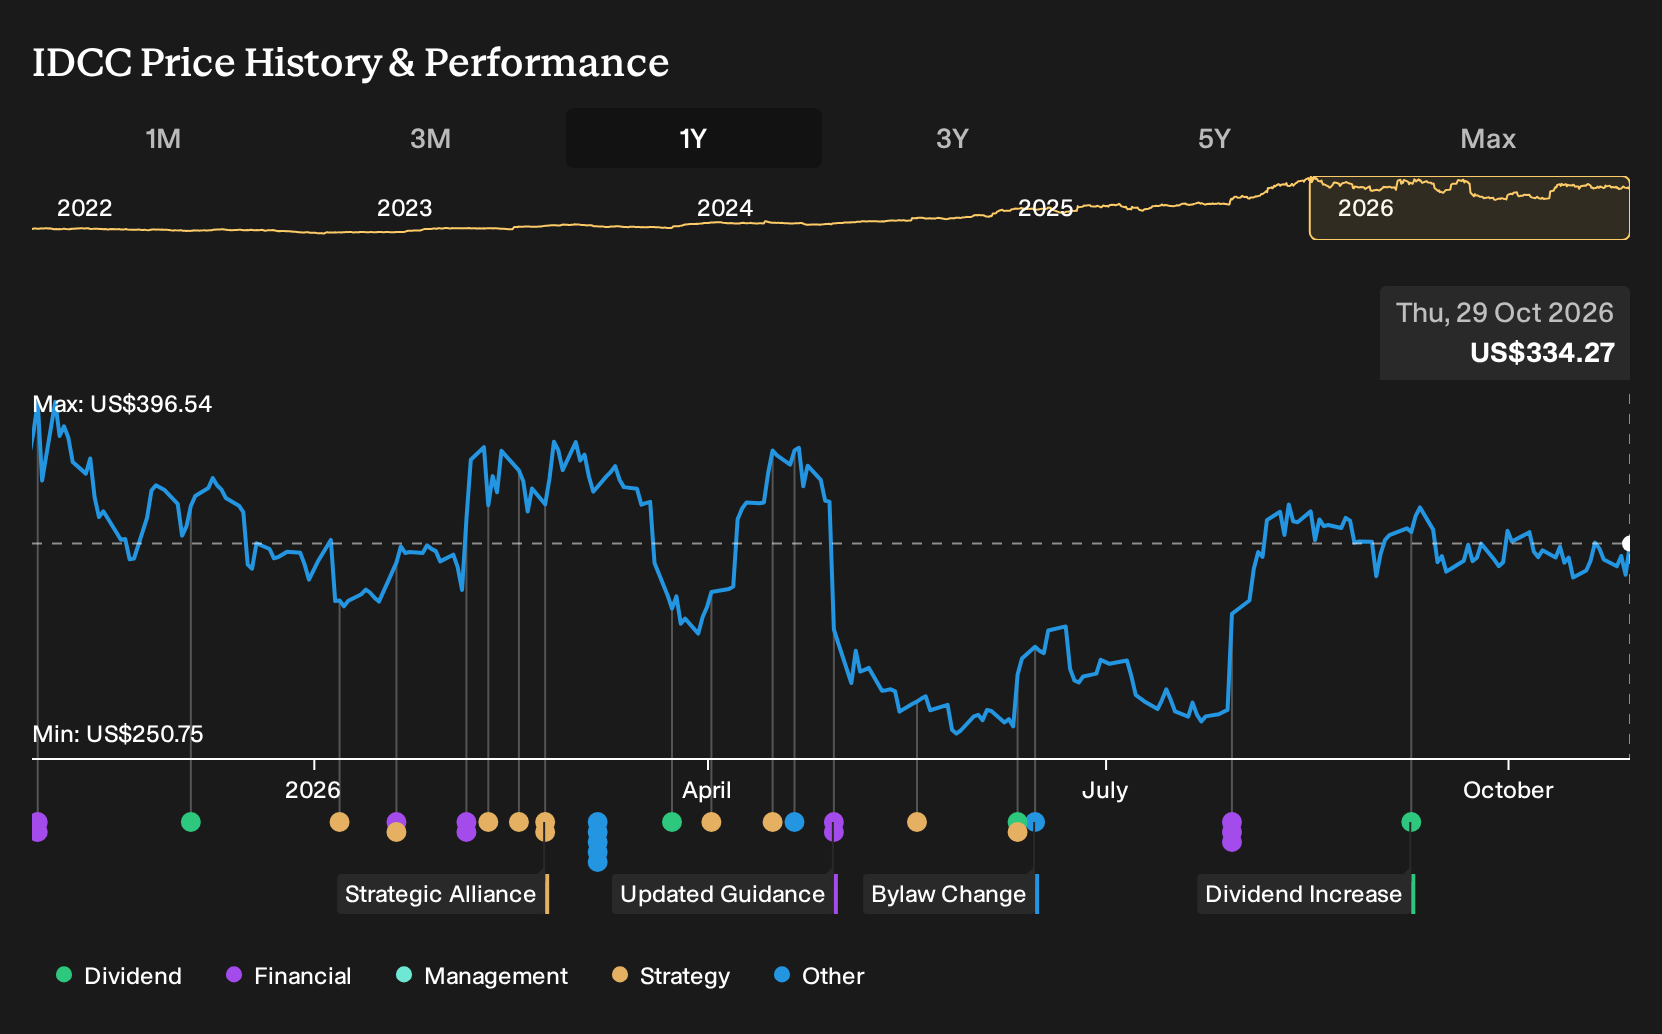
- InterDigital reported third quarter 2026 revenue of US$193.43 million and net income of US$80.23 million, raised full year 2026 guidance, and highlighted licensing traction with PC and IoT partners alongside patent enforcement wins against large media and device companies.
- The mix of stronger earnings, a higher dividend, and raised guidance based on contracted revenue shows InterDigital leaning on long duration licensing economics rather than one off settlements.
- We will examine how InterDigital's raised full year guidance, grounded in contracted revenue, reshapes the existing investment narrative around ARR.
InterDigital Investment Narrative Recap
To own InterDigital, you need to believe its licensing engine across wireless, video and connected devices keeps converting patents into long contracts and recurring cash. The latest quarter supports that view, with Q3 2026 revenue of US$193.43 million and net income of US$80.23 million, alongside higher full year guidance grounded in contracted revenue.
The near term swing factor is still how fast large streaming and cloud groups, including Amazon, translate into fully priced, long term agreements. The biggest operational risk is that enforcement and arbitration costs stay heavy or outcomes on major licenses land below expectations, which could squeeze margins and limit capital returns.
The most relevant fresh data point is the raised full year 2026 outlook, now calling for revenue of US$813 million to US$819 million and diluted EPS of US$8.93 to US$9.16. Management tied this upgrade to revenue already under contract, which matters if you care about visibility more than one off wins.
That contracted base interacts directly with the key catalysts investors watch for InterDigital. Progress on streaming and cloud licensing, plus newer IoT and automotive deals, now feeds into quantified guidance rather than just pipeline commentary. The trade off is that enforcement heavy growth can keep operating expenses elevated while these programs mature.
What The Current Forecasts Assume For InterDigital
InterDigital's narrative projects US$883.6 million revenue and US$371.6 million earnings by 2029. This implies 3.9% yearly revenue growth and an earnings increase of about US$69.4 million from US$302.2 million today.
Uncover why InterDigital's fair value indicates a 38% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
Some of the highest InterDigital analysts lean hard into arbitration as a catalyst. Before this earnings beat, they were modeling about US$983.5 million of revenue and US$421.7 million of earnings by 2029. You can see how different that optimism is from consensus, and the new Q3 data may push both narratives to evolve.
Explore 3 other InterDigital fair value estimates, including one that suggests as much as 38% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your InterDigital research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for InterDigital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate InterDigital's overall financial health at a glance.
Looking For More Investment Ideas Beyond InterDigital?
If InterDigital's contracted revenue profile appeals to you, it makes sense to compare it with other businesses that share similar traits in quality, resilience, or income potential. The Simply Wall St Screener lets you quickly filter for those kinds of opportunities without getting lost in thousands of tickers.
- For investors who care most about quality at a reasonable entry point, check out 30 high quality undervalued stocks which already combine stronger fundamentals with a price that still looks restrained.
- If capital preservation is higher on your list than headline growth, filter for 30 resilient stocks with low risk scores which score well on balance sheet strength and earnings stability.
- When you want ideas the market may not be paying full attention to yet, start with 18 high quality undiscovered gems which pair sturdy financial profiles with relatively low visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com