
Learn Why The Bull Case For TF1 (ENXTPA:TFI) Could Change Following Earnings Decline
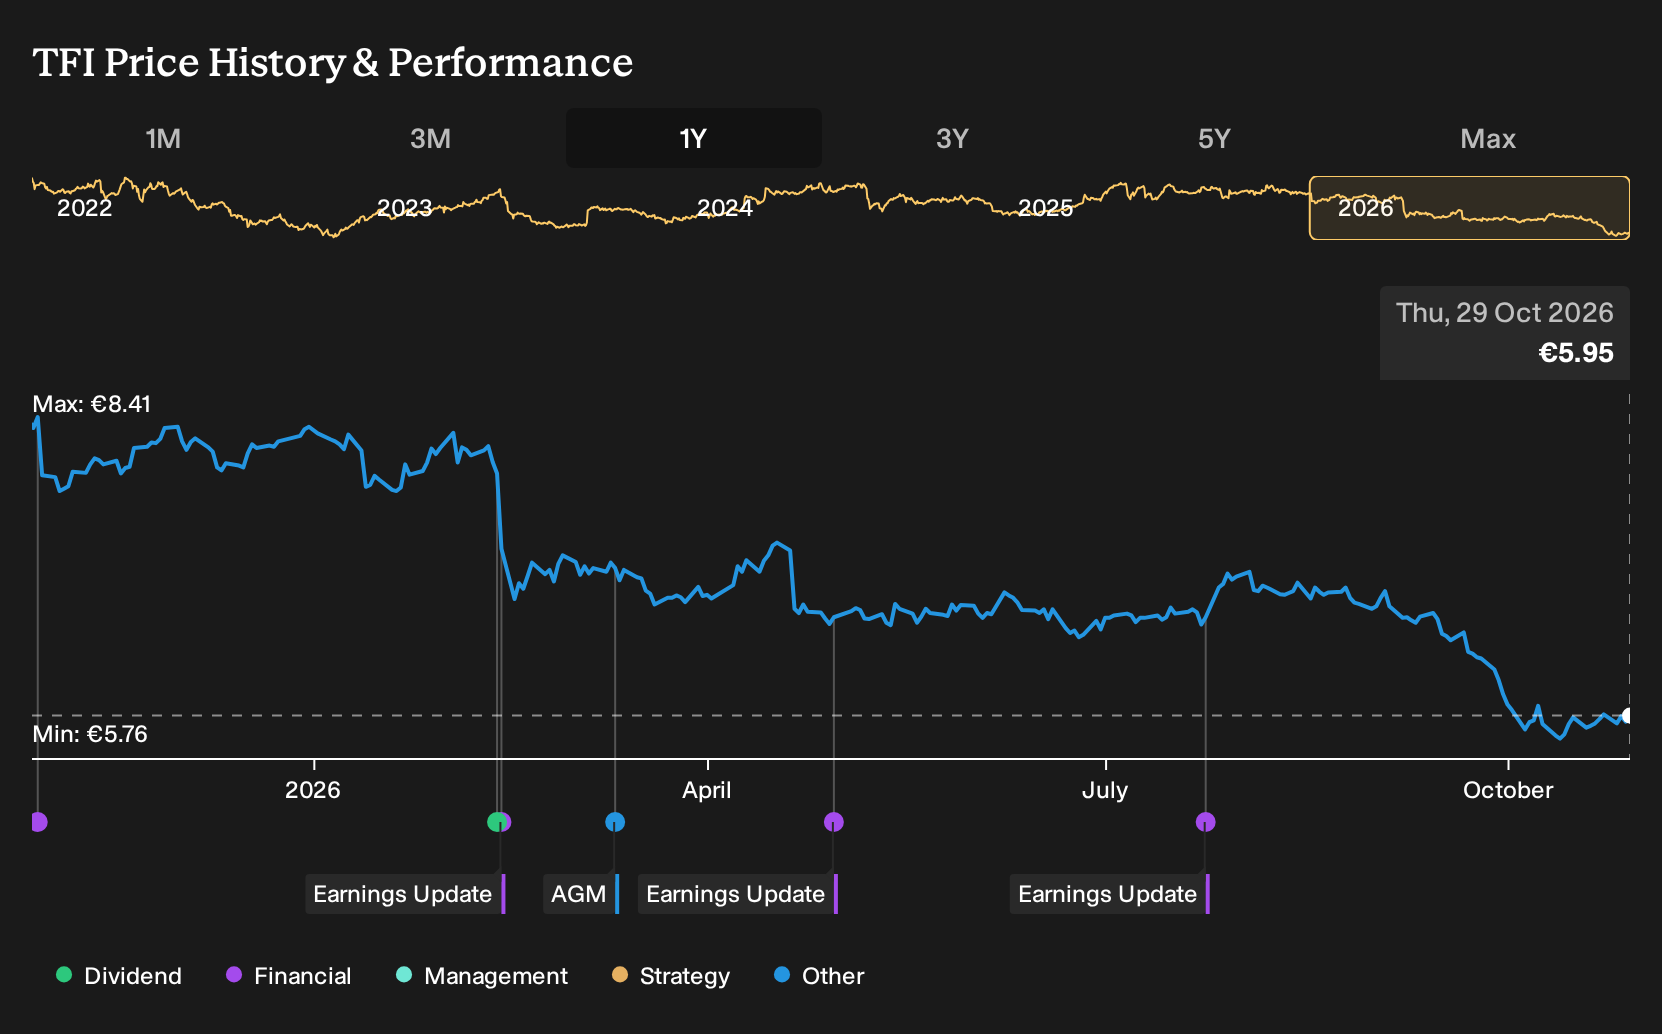
- TF1 SA reported third quarter 2026 sales of €460.9 million and net income of €20.5 million, with nine month sales of €1,454.3 million and earnings of €71.2 million, all below the prior year.
- The compression in basic earnings per share from continuing operations to €0.10 for the quarter and €0.34 for nine months highlights pressure on TF1's profitability, even as the company pursues its TF1+ and broader digital ambitions.
- We will now look at how TF1's weaker earnings and revenue profile may influence the investment narrative built around its TF1+ expansion.
See how TF1's earnings setback compares with peers by checking a curated list of resilient broadcasters and media groups in the 229 resilient stocks with low risk scores.
TF1 Investment Narrative Recap
To stay invested in TF1, you need to believe the shift from French linear TV advertising toward TF1+ and broader digital formats can offset pressure on legacy channels. The latest quarter makes that belief harder to hold, with weaker sales, lower net income and thinner basic EPS all pointing to profitability strain.
The key short term catalyst still sits in execution on TF1+ audience, ad loads and micro payments. That driver is intact, but the recent numbers underline how much room there is for performance to disappoint if advertising conditions stay soft or content costs do not adjust quickly enough. The earnings miss looks operationally material.
The most relevant piece of news is the nine month performance to September 2026. Sales of €1,454.3 million and net income of €71.2 million both trail the prior year, which keeps the focus squarely on how TF1 balances funding TF1+ growth with maintaining group profitability and cash generation.
Basic EPS from continuing operations over the period came in at €0.34 versus €0.58 a year ago, which compresses the earnings base that needs to support investment, dividends and any buybacks. For catalysts around TF1+, SME ad solutions and micro payments to matter to you, it becomes more important that management contains further earnings pressure from the traditional TV side.
TF1's current analyst story points to revenue of €2.2 billion and earnings of €90.3 million by 2029, with earnings today at €125.2 million and revenue growth expectations described as fairly flat. This implies a decline of about €34.9 million in earnings over that period rather than an increase.
Discover how TF1's fair value indicates a 28% potential upside to its current price that may be short-lived.
Exploring Other Perspectives
One alternative view zooms in on earnings risk rather than TF1+ upside. The most cautious analysts were already pencilling in 2029 profit of about €86.9 million on roughly €2.1 billion of revenue before this latest TF1 quarter. That is well below consensus and shows how sharply opinions can differ. It is therefore worth comparing several narratives and seeing which assumptions fit your own read of these results.
Explore 6 other TF1 fair value estimates, including one that suggests it could be worth just €6.50.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your TF1 research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TF1. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TF1's overall financial health at a glance.
Looking For More Ideas Beyond TF1?
If TF1's latest update leaves you wanting a broader watchlist, casting the net wider with the Simply Wall St Screener can help you pressure test your thesis and spot alternatives with different risk and income profiles.
- If capital protection matters most to you, start with a curated pool of resilient businesses by running the 229 resilient stocks with low risk scores.
- If dependable income is your priority, scan for companies with stronger yield profiles and balance those against TF1's position using the 228 dividend fortresses.
- If you want to hunt for potential mispricing, look for businesses that pair quality fundamentals with more modest valuations through the 195 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com