
How Investors May Respond To Telefónica Stock Satellite Spectrum Bid
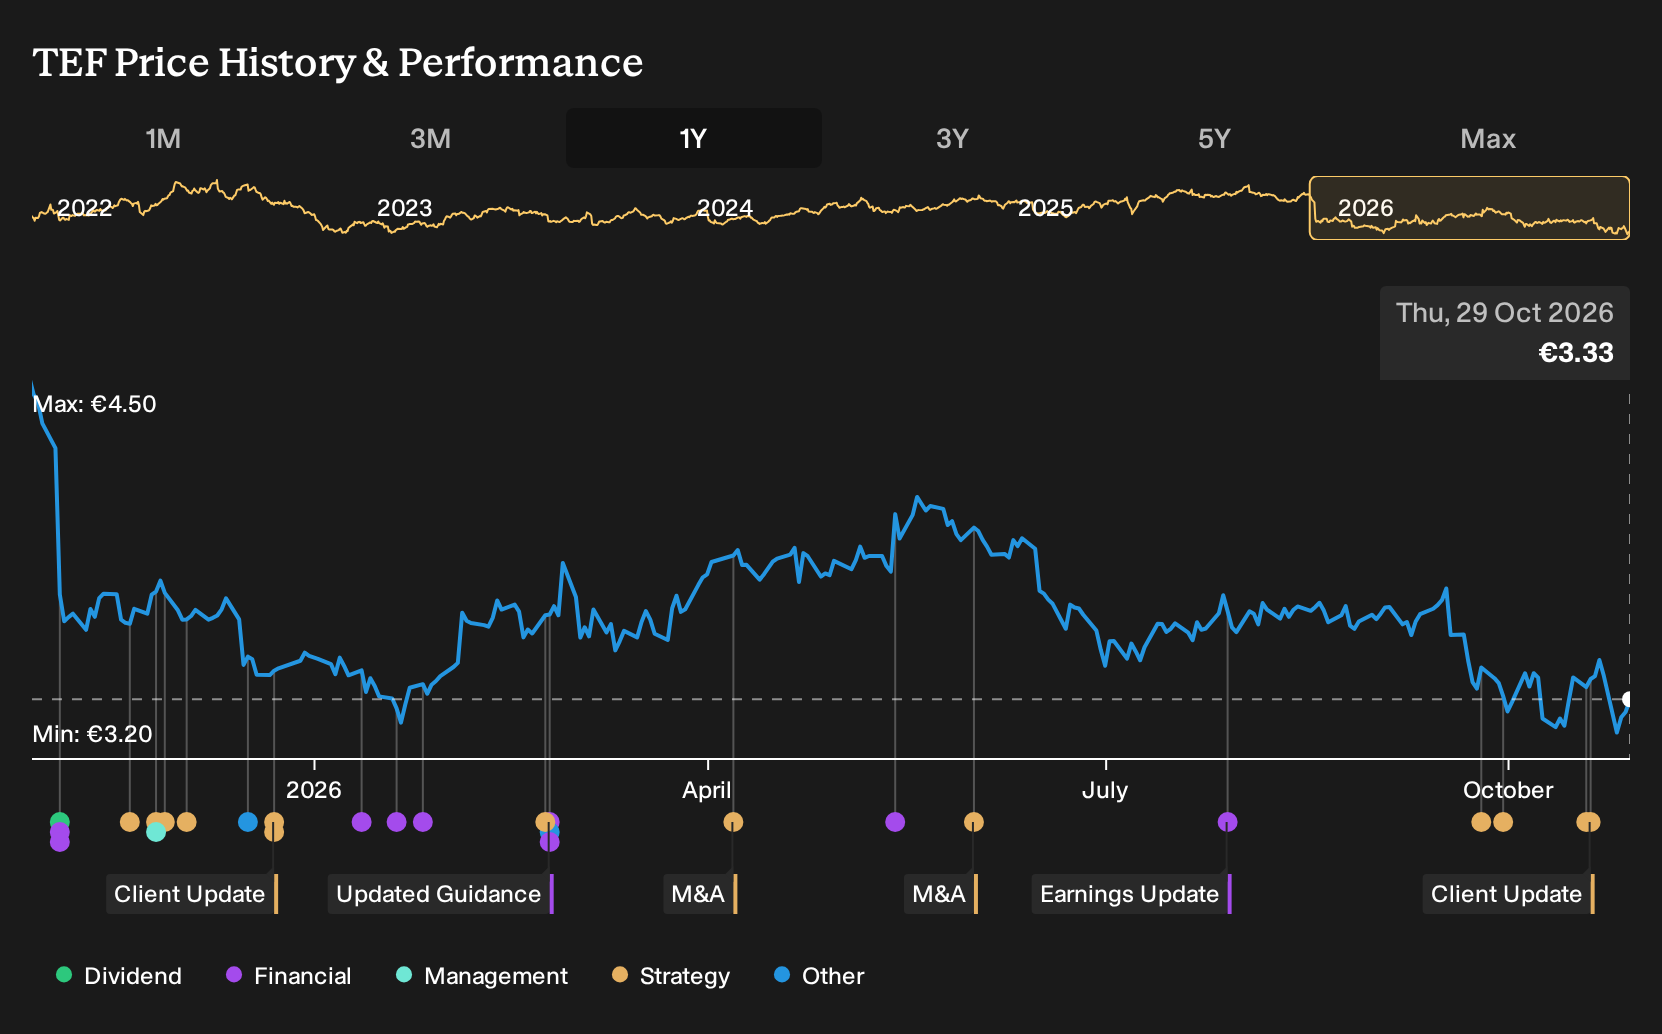
- In October 2026, AST SpaceMobile said that Deutsche Telekom, Orange, Telefónica and Vodafone signed a Letter of Intent to explore a joint bid for Mobile Satellite Services spectrum in Europe, while Hiya announced an agreement with Telefónica to deploy its Branded Call caller ID service for the operator’s 4G and LTE users in Spain.
- These moves highlight Telefónica’s efforts to extend coverage through satellite connectivity and to strengthen its position in fraud-resistant, branded mobile communications as part of its broader network modernisation and digital services agenda.
- This article now examines how Telefónica's investment narrative could be influenced by its MSS spectrum consortium and branded caller ID rollout.
Telefónica Investment Narrative Recap
To own Telefónica, you need to believe the telecom can turn heavy infrastructure and digital upgrades into steadier cash generation, despite muted revenue expectations and a complex footprint across Europe and Latin America. The most important short term catalyst is execution on network modernization and higher value B2B services. These could support margins even if the top line stays flat.
The biggest risk still sits on the balance sheet. High leverage and interest costs that are not well covered by earnings leave little room for missteps or aggressive pricing battles. The new satellite and caller ID announcements are helpful for the operating story but do not materially change that near term risk reward equation yet.
The Hiya Branded Call rollout is the clearest operational touchpoint for investors right now. Telefónica is addressing a fraud and trust problem that directly affects how businesses use mobile calling. It does this without asking customers to install apps or change behavior, which can speed up adoption and keep support costs lower if execution is tight.
This fits the broader catalyst around higher margin digital services layered on top of existing connectivity. If the service gains traction, it may reinforce Telefónica’s appeal to enterprise clients that are already buying cloud, cybersecurity and data products. The risk is that take up or pricing fails to offset pressure in core markets, leaving debt and dividend coverage concerns unchanged.
Telefónica's current loss of €2.5 billion is matched against analyst forecasts for earnings of €2.4 billion by 2029 and revenue of €34.4 billion in that same year. This implies a 1.7% yearly revenue decline and an earnings swing of about €4.9 billion from today's earnings to the consensus estimate.
Uncover how Telefónica's fair value indicates a 19% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One contrasting angle you might explore is how bullish analysts frame Telefónica’s debt risk. They already expected earnings of about €3.5 billion on €35.9 billion of revenue by 2029, versus about €2.7 billion at the low end, even before factoring in MSS spectrum or Branded Call. Those forecasts assume leverage becomes more manageable, so this fresh news could eventually shift the story in either direction.
Explore 3 other Telefónica fair value estimates, including one that suggests there may be as much as 73% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Telefónica research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Telefónica. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Telefónica's overall financial health at a glance.
Looking for more investment ideas beyond Telefónica?
If the Telefónica story has you thinking about where else to put fresh capital, it can help to scan for companies with very different risk and balance sheet profiles. The Simply Wall St Screener gives you a structured way to do that, so you are not just reacting to headlines.
- For investors who want potential upside without ignoring quality, consider a curated set of companies trading below estimated value using the 196 high quality undervalued stocks.
- If sleep-at-night resilience matters more to you than excitement, filter for businesses with steadier fundamentals through the 226 resilient stocks with low risk scores.
- Those hunting for opportunities that the broader market has not fully focused on yet can draw ideas from the 607 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com