
What Church & Dwight Doubters Missed
If Church & Dwight was on your watchlist rather than in your portfolio, the outcome may feel like a miss. Investors who held Church & Dwight over the past year are up 31.3%, including dividends. That result arrived alongside Q2 2026 numbers that showed both revenue and profit higher than a year earlier, plus firmer net margin. What early clue might have helped you treat e-commerce driven brand momentum as durable rather than temporary?
If the move has made Church & Dwight harder to judge, start where the gap is still open and scan 30 high quality undervalued stocks.
The Two Stories Investors Had To Weigh On Church & Dwight
The shares cost US$81.84 at the start of the period, and anyone looking at Church & Dwight then had to choose which story felt more realistic.
The bullish narrative pointed to a Fair Value of US$100, a rough guide to what the stock might be worth if e-commerce strength and health focused brands like THERABREATH and HERO kept supporting higher margins and earnings.
The cautious view used a Fair Value of US$73.5 and focused on reformulation costs and eco friendly packaging spend squeezing profitability as competition and retailer pressure limited pricing power.
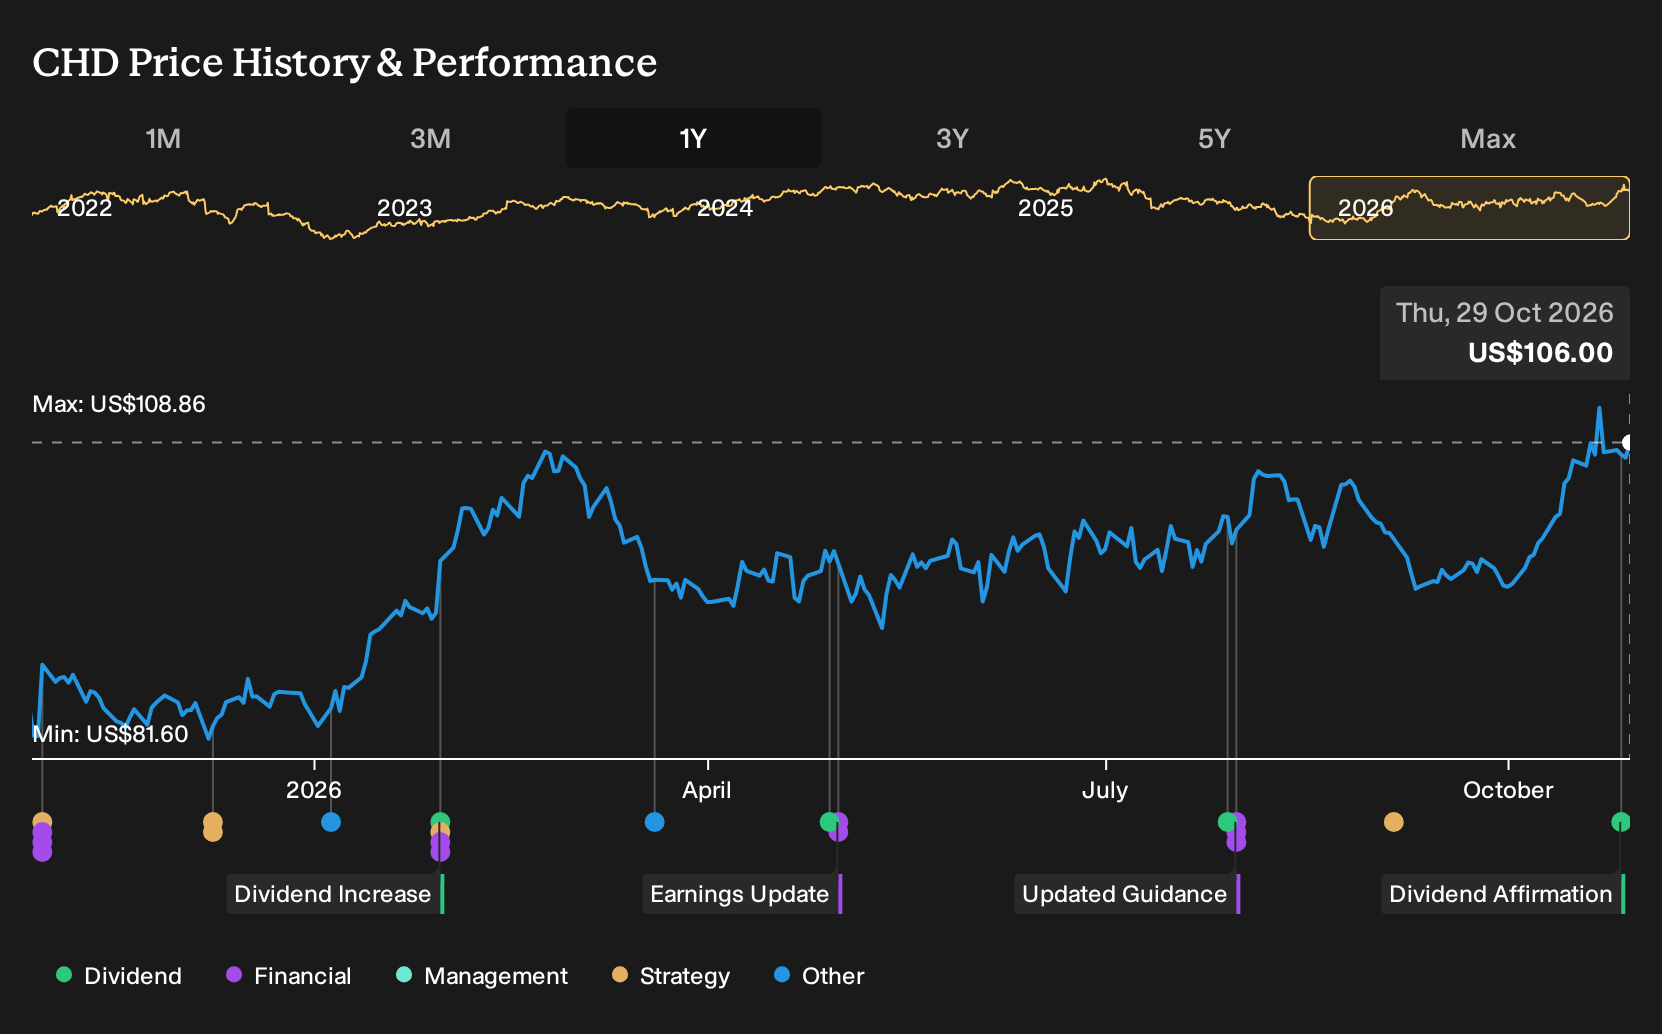
What The Results Changed For Church & Dwight
Q2 2026 put Church & Dwight’s e-commerce and brand story to the test. Revenue rose from US$1,506.3m to US$1,530m and net income grew from US$191m to US$202.8m, with net margin moving from 12.7% to 13.3%. Strong Q1 and Q2 organic sales growth tied to TheraBreath, Hero and online channels supported the optimistic case, although earlier commentary about slower category growth kept the cautious view alive. On balance, the evidence cut both ways.
The useful takeaway is simple. When a bullish pitch leans on premium brands and digital channels, track organic sales growth, margin trends and e-commerce mix in each report. Those three figures show whether brand momentum is turning into durable profitability or just masking category or cost pressure that may resurface later.
What Today's Church & Dwight Price Already Assumes
Church & Dwight now trades at US$106 after a 31.3% total return over the past year. The selected Narrative’s Fair Value estimate sits below that level, framing today’s quote as demanding rather than cheap.
The Narrative leans on strong brands and e-commerce reach, yet questions how resilient margins and cash generation really are. For today’s valuation to hold up, a buyer has to assume Church & Dwight keeps growing online driven power brands fast enough to offset cost pressure and slower categories without eroding profitability.
"Key Takeaways: Bearish analysts expect Church & Dwight to face ongoing margin pressure as inflation, tariffs and elevated promotional intensity in categories like laundry and cat litter keep costs high and limit full expense pass through to consumers. The main thing that has to go right is that Church & Dwight continues to turn its e-commerce scale up to about 25 to 25.5% of consumer sales, plus its portfolio of acquired power brands such as THERABREATH, HERO and Miss Mouth’s, into sustained volume growth that offsets slower legacy categories and higher brand investment."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
How Could You Get There Earlier?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 32% below our estimate - targets accelerating AI data center demand that stretches power and hardware planning capacity.
- Company 2 - 23% below our estimate - threads AI capabilities into cloud, workplace and developer tools to deepen recurring engagement.
- Company 3 - 43% below our estimate - converts a large backlog of complex construction projects into higher utilization across trade crews.
Three companies from the same screener. Open every one of the 23 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com