
Jacobs Solutions (J) Lands Two Big Infrastructure Wins As Fair Value Debate Builds
Jacobs Solutions (J) has just added two large infrastructure wins to its backlog: a US$1 billion wastewater upgrade in San Francisco and a five-year transmission delivery role with American Electric Power across seven Eastern states.
These contract wins arrive while Jacobs Solutions’ share price has been firming, with a 30 day share price return of 11.93% and a 90 day gain of 13.21%. However, the 1 year total shareholder return is slightly down at 2.42%, while longer term 3 and 5 year total shareholder returns of 41.67% and 35.97% indicate momentum that has been built over several years.
Scan how Jacobs Solutions compares with hand-picked infrastructure and engineering peers by reviewing the list of solid balance sheet and fundamentals (23 results) that could benefit from similar long-term project pipelines.
After contract news like this and a double digit 90 day share price gain, the real tension around Jacobs Solutions is simple. Do current cash flow assumptions still leave enough upside to compensate for execution risk?
Most Popular Narrative: 6% Undervalued
Jacobs Solutions closed at $152.76, while the most followed narrative pegs fair value around $162.53 using a discount rate of 7.81%. That gap is not huge, yet it matters when contract wins and a growing project pipeline are already in the price.
Record backlog of about US$29b with a trailing 12 month book to bill of 1.4x on gross revenue and 1.2x on net revenue points to multi year conversion of existing awards into revenue growth that many investors may not be fully pricing into Jacobs Solutions earnings power.
See why 20 investors see Jacobs Solutions as 6% undervalued.
Result: Fair Value of $162.53 (UNDERVALUED)
Still, shifts in government infrastructure budgets or a slowdown in AI data center awards could quickly challenge the Jacobs Solutions backlog-driven upside story.
Find out about the key risks to this Jacobs Solutions narrative.
Another View: Jacobs Solutions Looks Expensive On Earnings
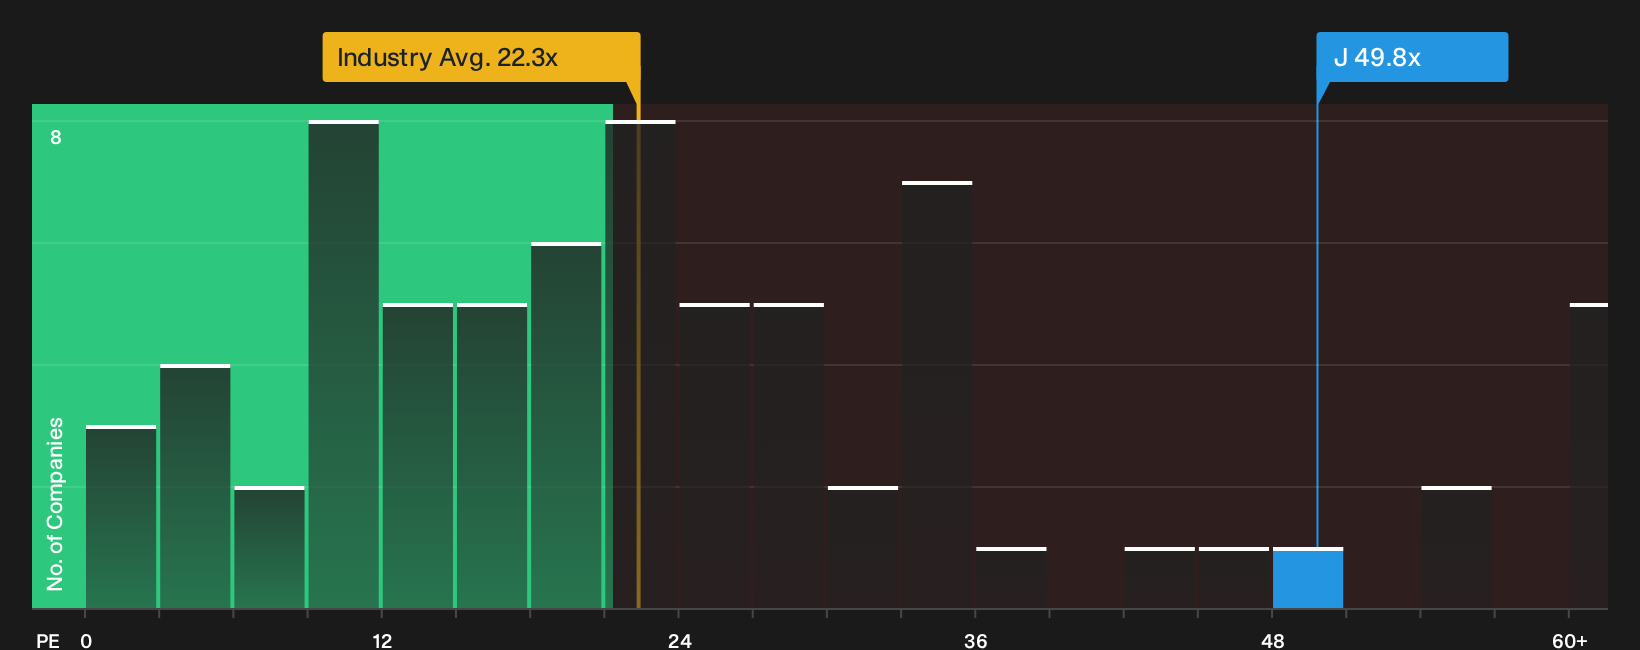
Jacobs Solutions screens as undervalued on fair value estimates, yet the current P/E of 49.8x tells a very different story. That multiple is more than double the US Professional Services average of 22.3x and well above the 33.4x fair ratio, which signals meaningful valuation risk if sentiment cools.
This kind of gap can close in more than one way, so it is worth stress testing how much P/E compression your thesis can handle before the investment case breaks. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Jacobs Solutions so far. If the combination of risks and upside potential has your attention, it is worth reviewing the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Jacobs Solutions?
If Jacobs Solutions has sharpened your focus on quality, do not stop here. Broaden your watchlist with a few targeted stock sets that match different risk and reward preferences.
- Target resilience by zeroing in on companies with strong finances and durable balance sheets through the list of solid balance sheet and fundamentals (23 results).
- Hunt for mispriced opportunities by scanning the 30 high quality undervalued stocks that combine robust fundamentals with room for a better entry point.
- Strengthen your income stream by reviewing the 7 dividend fortresses built around higher-yield payouts backed by solid profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com