
Learn Why The Bull Case For Nuvation Bio (NUVB) Could Change Following European Trial Expansion
- Nuvation Bio announced that its pivotal Phase 3 SIGMA trial of oral IDH1 inhibitor safusidenib has expanded to new sites across six European countries, adding to existing enrollment regions including the U.S., China, Japan, Australia and Canada for high risk IDH1 mutant astrocytoma and an exploratory oligodendroglioma cohort.
- The broader geographic footprint for SIGMA, alongside prior FDA Fast Track Designation and ongoing Phase 3 and Phase 2 work, highlights how Nuvation Bio is committing capital and operational focus to safusidenib as a potential second long term oncology revenue pillar.
- We will now look at how Nuvation Bio's investment narrative could shift as the SIGMA Phase 3 trial broadens into Europe.
Nuvation Bio Investment Narrative Recap
To own Nuvation Bio, you need to believe safusidenib can ultimately sit alongside IBTROZI as a second meaningful oncology revenue pillar and that current losses are buying real long term optionality. The SIGMA expansion into Europe may help de risk the operational side of that belief by broadening the pool of eligible patients and sites.
The biggest near term operational swing factor still sits with safusidenib Phase 3 execution, not the share price. Recruitment speed, data quality and clean safety will likely matter more than geography. The main risk remains timing. Any setback in enrollment, regulator feedback or competitive data could extend the window where IBTROZI carries most of the financial load.
The FDA Fast Track Designation for safusidenib in IDH1 mutant glioma, granted in August 2026, ties directly into this SIGMA expansion story. Fast Track can facilitate more frequent interactions with the FDA. That can matter when a pivotal program like SIGMA is recruiting globally and aiming for a clear maintenance therapy label in high risk astrocytoma.
Seen together, Fast Track and the enlarged SIGMA footprint put safusidenib more firmly at the center of Nuvation Bio's pipeline execution. They also raise the stakes on the risk that Phase 3 data are delayed or less compelling than hoped, which would keep the business more reliant on IBTROZI and leave the long discussed second revenue pillar further out on the horizon.
Nuvation Bio's current earnings sit at a loss of $149.8 million, while analysts on average project earnings of $10.6 million by 2029. This implies an earnings swing of roughly $160 million, alongside an assumed 40.3% yearly increase in revenue that is expected to support forecast 2029 revenue of $469.0 million.
Uncover why Nuvation Bio's fair value indicates a 175% potential upside to its current price that could narrow quickly.
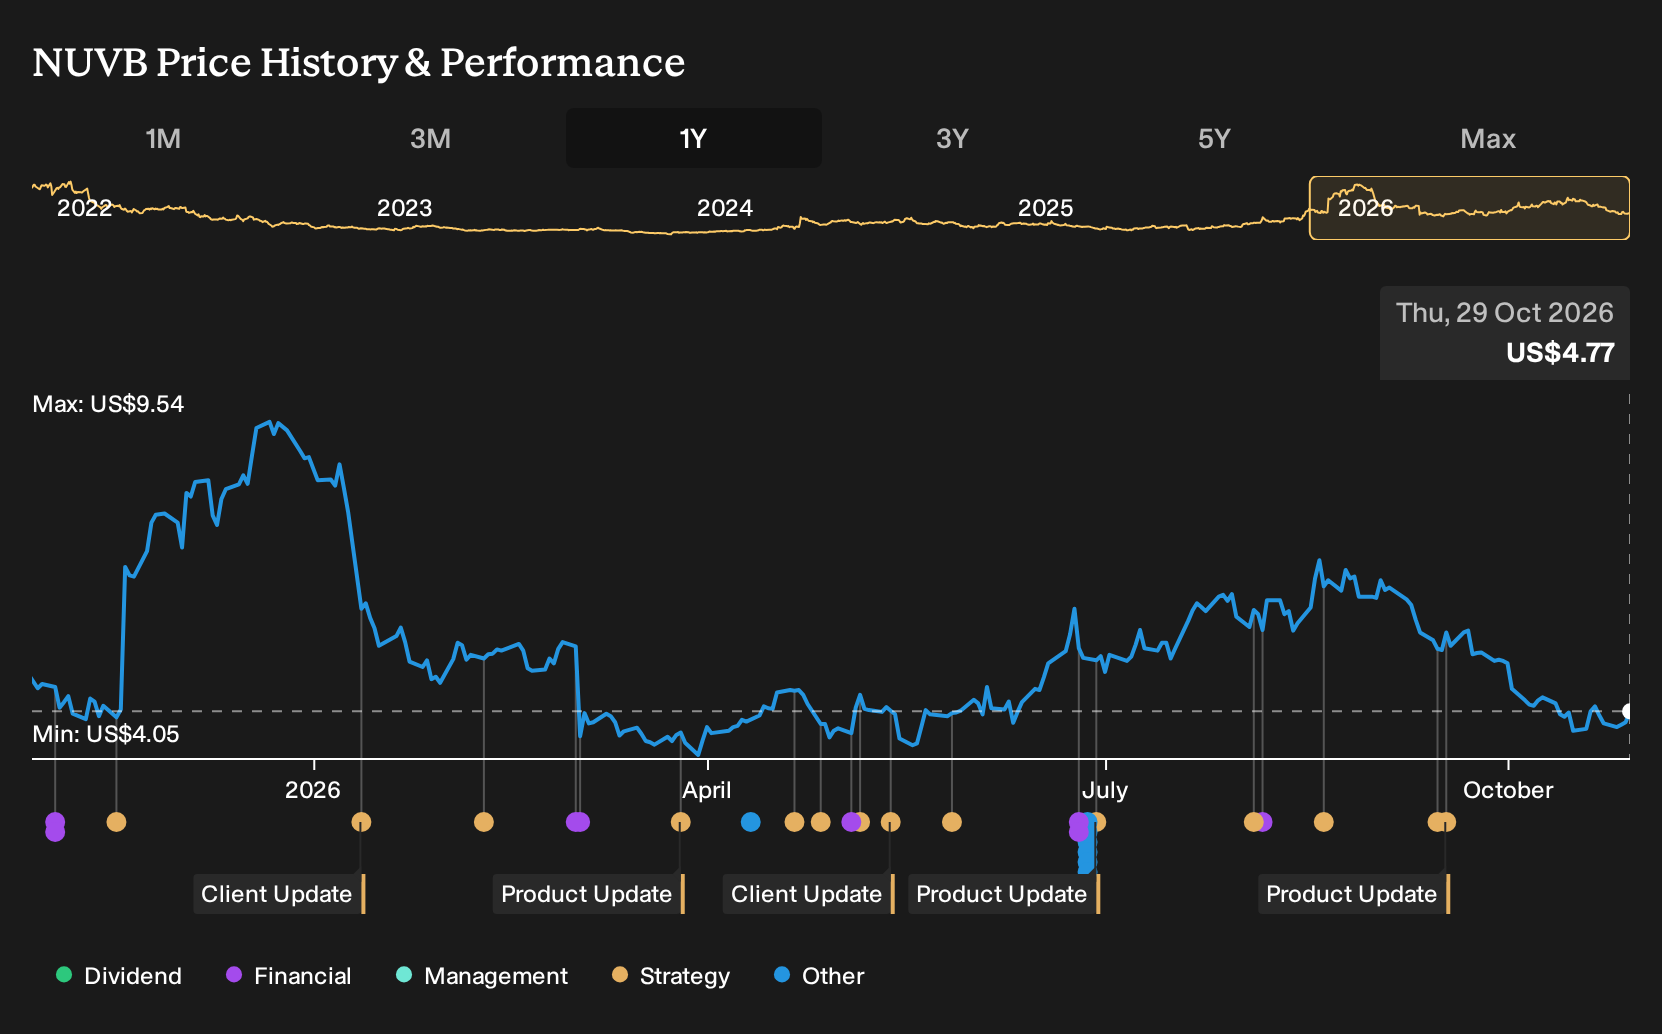
Exploring Other Perspectives
You might see this SIGMA trial expansion very differently if you lean on the most pessimistic analysts. They were previously modeling 31.3% annual revenue growth and about US$384.7 million of sales by 2029, with earnings of US$66.0 million, which is far below the more bullish projections. Use that spread as a prompt to explore multiple viewpoints that could shift as Nuvation Bio’s European trial footprint develops.
Explore 3 other Nuvation Bio fair value estimates, including one that suggests it could be worth just $13.00!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Nuvation Bio research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Nuvation Bio. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nuvation Bio's overall financial health at a glance.
Looking for more Nuvation Bio sized ideas?
If Nuvation Bio has sharpened your focus on where cancer drug development risk and reward intersect, casting a wider net can help you stress test your thesis and avoid anchoring on a single ticker.
- Prefer rock solid balance sheets with fewer financial surprises and a focus on resilience? Review our list of solid balance sheet and fundamentals (23 results) that fit those priorities.
- If you are hunting for underappreciated quality where current prices look restrained relative to fundamentals, check out a curated pool of 30 high quality undervalued stocks that might suit a value driven watchlist.
- For investors who want to keep volatility in check and focus on steadier profiles, scan through a hand picked set of 30 resilient stocks with low risk scores that could complement higher risk biotech exposure.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com