
Learn Why The Bull Case For Canadian Tire Stock Could Change Following AI Pricing Rollout
- Canadian Tire Corporation has rolled out AI driven pricing and customer analytics tools across its retail system, targeting more precise promotions, assortment decisions and earnings quality across its banners, real estate trust and financial services unit.
- The same AI toolkit that shapes discounts and shelf mix could indirectly influence how secure Canadian Tire Corporation’s dividend looks by shifting where cash is generated across retail, property income and the credit card bank.
- We will now look at how Canadian Tire Corporation’s AI pricing rollout could reshape its investment narrative around earnings quality.
Compare Canadian Tire Corporation’s AI pricing initiative with strategies at other retailers and payment companies using our hand picked 54 AI infrastructure stocks list as a starting universe.
Canadian Tire Corporation Investment Narrative Recap
To own Canadian Tire Corporation you need to be comfortable with a complex, three legged model that ties together retail banners, CT REIT and a credit card bank. The AI pricing rollout plugs straight into that thesis. The short term swing factor is whether these tools support gross margin without requiring much higher SG&A or capital spending.
The biggest near term risk still sits in costs and balance sheet pressure. Debt is not well covered by operating cash flow and CTFS expenses are planned to stay elevated. If AI driven assortment and promotion decisions misfire, they could add inventory and credit risk rather than smoothing earnings quality.
The current AI pricing and customer analytics rollout is the key announcement to watch. It reaches across Canadian Tire Corporation’s banners and the financial services arm, which means it touches both where sales are booked and how credit is extended and priced. For a dividend payer, that matters for how predictable cash flows look.
Execution risk is material. These tools aim to fine tune promotions, regular prices and category mix, but they also add complexity on top of True North integration, Triangle loyalty and store refresh programs. Investors will likely focus on whether gross margin, write offs and SG&A remain under control as this AI layer ramps across the system.
Canadian Tire Corporation AI Rollout Through the Analyst Lens
Canadian Tire Corporation's narrative projects CA$17.5b revenue and CA$797.2m earnings by 2029. This implies 2.0% yearly revenue growth and an earnings increase of about CA$118m from CA$679.2m today.
Uncover why Canadian Tire Corporation's fair value is effectively aligned with its current price.
Exploring Other Perspectives
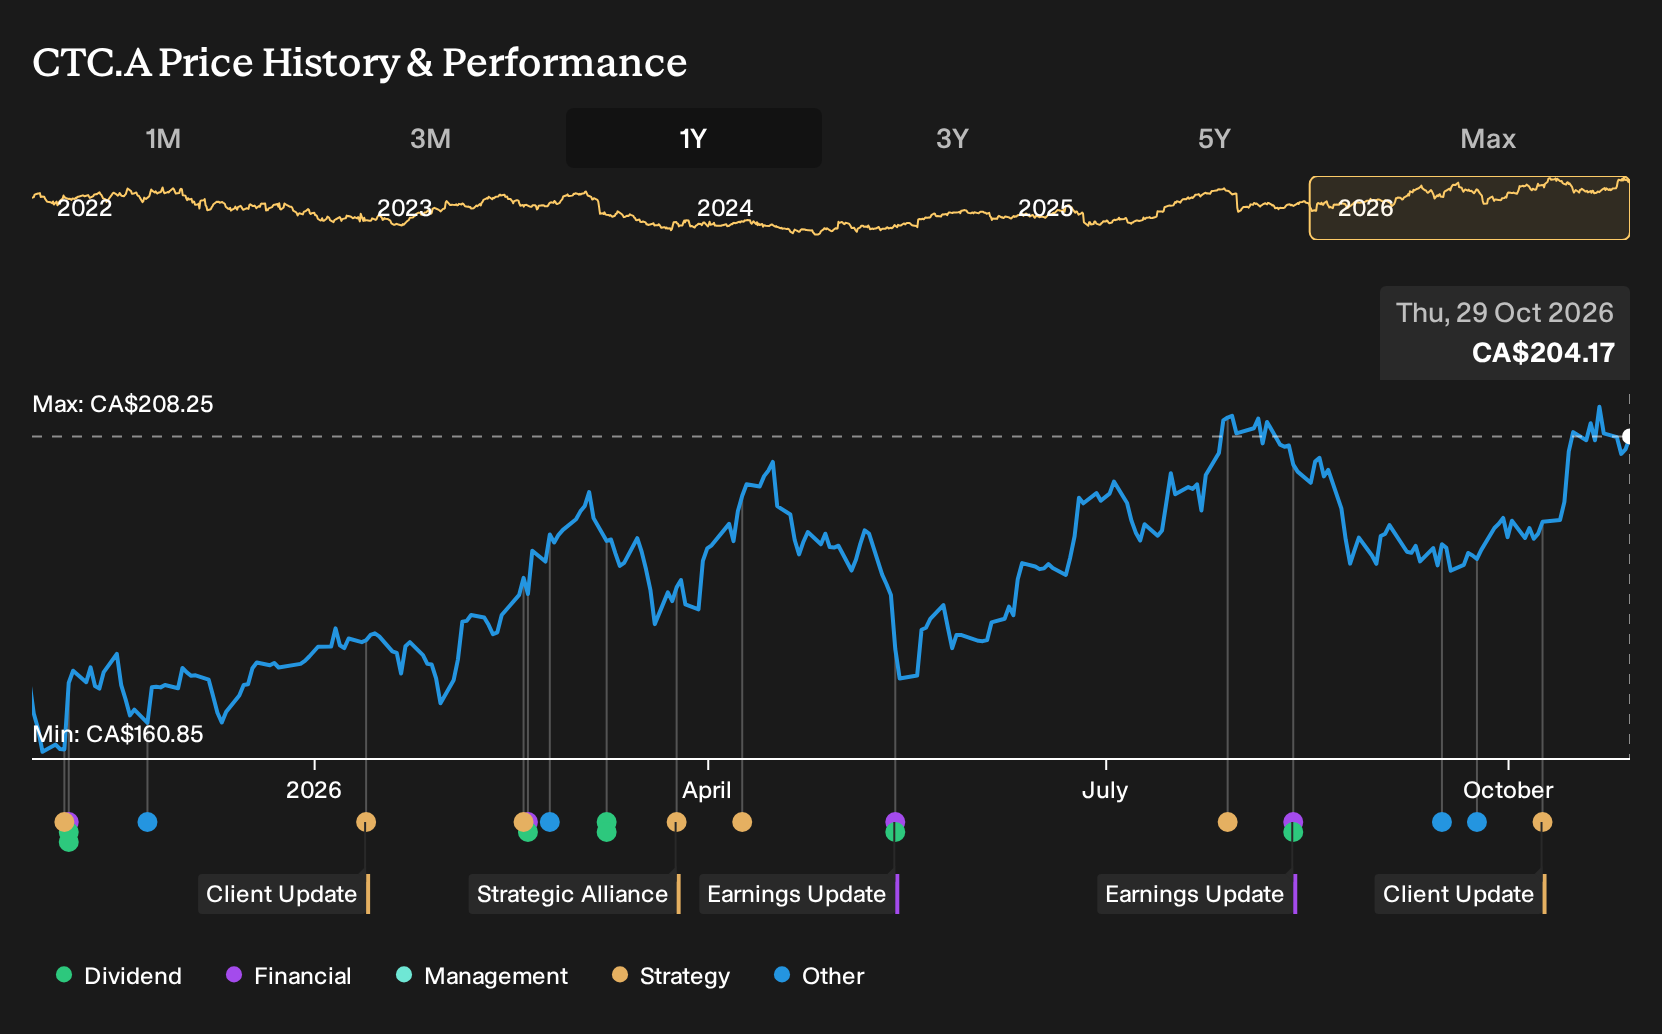
Three fair value estimates from the Simply Wall St Community cluster between about CA$153.68 and CA$206.60, which already shows how far private investors can stretch on Canadian Tire Corporation. Set that beside unresolved risks around the 2025 data breach and elevated CTFS expenses, and you get plenty of reason to compare multiple viewpoints before deciding where you stand.
Explore 2 other Canadian Tire Corporation fair value estimates, including one that suggests it could be worth as much as CA$206.60.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Canadian Tire Corporation research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Canadian Tire Corporation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Canadian Tire Corporation's overall financial health at a glance.
Looking for more investment ideas beyond Canadian Tire Corporation?
Once you have a view on Canadian Tire Corporation, it can help to widen the lens and compare it with other businesses that fit different risk and income profiles using the Simply Wall St Screener.
- For investors who care most about balance sheet strength and fundamental resilience, start with a list of solid balance sheet and fundamentals (6 results) to see which businesses might better match a capital preservation mindset.
- If you want to prioritise income, look at potential yield opportunities through a curated set of 3 dividend fortresses and see which payers line up with your risk tolerance.
- When you are searching for potential outliers that the wider market may not be focused on yet, scan through a hand picked pool of 8 high quality undiscovered gems that pair quality metrics with more limited coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com