
Does Netflix (NFLX) Sit Below Fair Value After A 45% Fall?
Netflix has seen its share price fall sharply over the past year, and the question now is whether the current market value still lines up with the cash the business is expected to generate. With sentiment swinging around password policies, content bets and advertising plans, the stock has become a live test of how much investors are willing to pay for those future cash flows.
- Over the past 12 months, Netflix has declined 44.5%, which puts a spotlight on whether that drop now reflects its underlying cash generation or if the market is still adjusting expectations.
- Recent commentary from Netflix on membership gains, pricing power and the buildout of its advertising tier points to specific levers that can influence future cash inflows and the timing of when those flows show up for shareholders.
- What if you looked at Netflix through its earnings instead? See what Netflix's 17.3x P/E says about the price.
The stock's next move may depend on whether the price you see today is well supported by the cash flows implied by its intrinsic value estimate.
If you are reassessing Netflix after a 44.5% share price decline and a year of headline pressure on engagement and advertising, a focused stock screen is another starting point for research through 30 high quality undervalued stocks.
Does Netflix Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here looks at the cash Netflix is expected to generate for shareholders and discounts it back to today. On the latest figures, the business produced trailing twelve month free cash flow of about $11.6b, and the projections used in this DCF assume that those annual cash flows keep growing rather than shrinking over the coming decade.
Based on that set of assumptions, the DCF output suggests Netflix's implied intrinsic worth is meaningfully above the current share price of $62.05. Recent concerns around weaker engagement and a softer outlook for the advertising business help explain why the market price has fallen to a level that this cash flow model does not fully support. Find out what Netflix could be worth using our Discounted Cash Flow (DCF) estimate.
The Netflix Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where that valuation question leaves off for Netflix. Each narrative spells out the specific assumptions on growth, profitability and earnings power that would need to hold for Netflix's share price to end up materially higher or lower than today. Instead of a single multiple or model result, it lays out the moving parts behind that fair value view so you can later compare those expectations with the numbers Netflix actually reports.
Community views on Netflix split between those who see solid cash generation already well reflected in the price and others who think the market is still overpaying for a slower next chapter.
Bull case: 24% undervalued
"The bull case increasingly leans on pricing, advertising, margin expansion and buybacks rather than pure subscriber momentum..."
Discover why this Narrative puts Netflix at 24% undervalued.
Bear case: 7% overvalued
"Advertising supplies the other admission, and the more careful framing... 'we are currently a bit behind our aggressive target for the year,' Peters says..."
Explore why this Narrative puts Netflix at 7% overvalued.
One more Netflix signal the valuation work does not answer
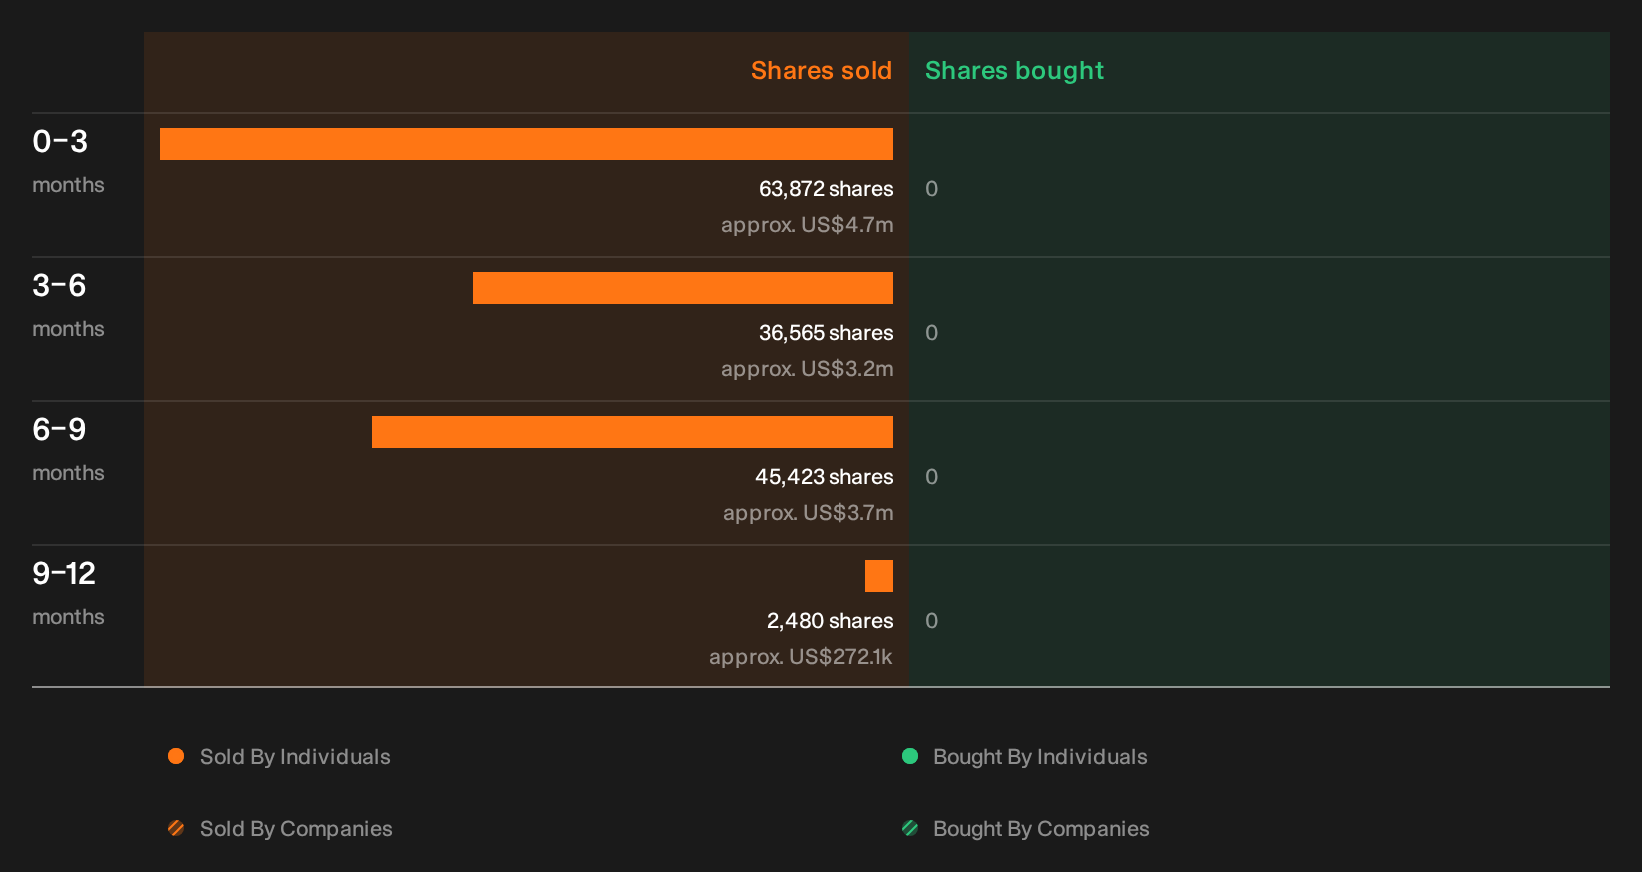
There is one loose thread that matters for anyone weighing Netflix today. It is the cluster of recent insider sales our checks have picked up and what those trades might really signal once you inspect the details. See the recent insider selling flagged for Netflix.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com