
Here's Why We're Watching Spire Global's (NYSE:SPIR) Cash Burn Situation
We can readily understand why investors are attracted to unprofitable companies. For example, although software-as-a-service business Salesforce.com lost money for years while it grew recurring revenue, if you held shares since 2005, you'd have done very well indeed. But the harsh reality is that very many loss making companies burn through all their cash and go bankrupt.
So, the natural question for Spire Global (NYSE:SPIR) shareholders is whether they should be concerned by its rate of cash burn. For the purpose of this article, we'll define cash burn as the amount of cash the company is spending each year to fund its growth (also called its negative free cash flow). First, we'll determine its cash runway by comparing its cash burn with its cash reserves.
Does Spire Global Have A Long Cash Runway?
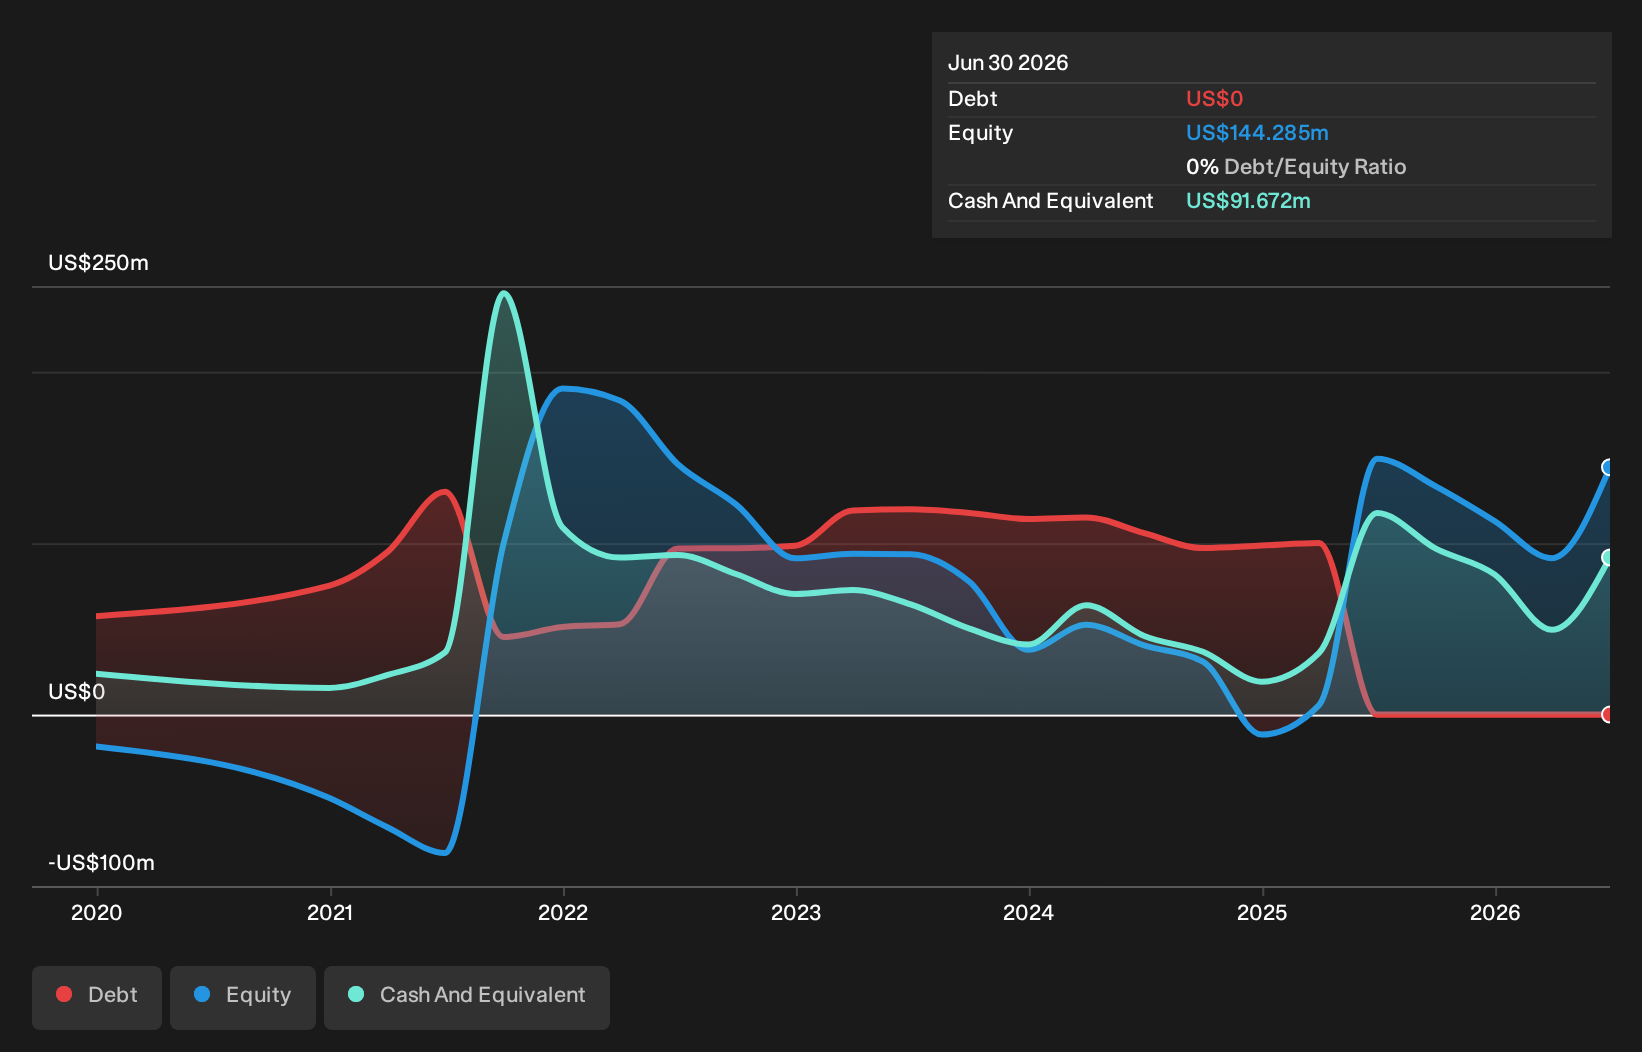
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. In June 2026, Spire Global had US$92m in cash, and was debt-free. In the last year, its cash burn was US$100m. So it had a cash runway of approximately 11 months from June 2026. To be frank, this kind of short runway puts us on edge, as it indicates the company must reduce its cash burn significantly, or else raise cash imminently. We should note, however, that if we extrapolate recent trends in its cash burn, then its cash runway would get a lot longer. You can see how its cash balance has changed over time in the image below.
View our latest analysis for Spire Global
How Well Is Spire Global Growing?
At first glance it's a bit worrying to see that Spire Global actually boosted its cash burn by 32%, year on year. And we must say we find it concerning that operating revenue dropped 33% over the same period. Taken together, we think these growth metrics are a little worrying. While the past is always worth studying, it is the future that matters most of all. For that reason, it makes a lot of sense to take a look at our analyst forecasts for the company.
How Hard Would It Be For Spire Global To Raise More Cash For Growth?
Since Spire Global can't yet boast improving growth metrics, the market will likely be considering how it can raise more cash if need be. Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. Many companies end up issuing new shares to fund future growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
Since it has a market capitalisation of US$379m, Spire Global's US$100m in cash burn equates to about 26% of its market value. That's not insignificant, and if the company had to sell enough shares to fund another year's growth at the current share price, you'd likely witness fairly costly dilution.
How Risky Is Spire Global's Cash Burn Situation?
Spire Global is not in a great position when it comes to its cash burn situation. While its cash runway wasn't too bad, its falling revenue does leave us rather nervous. Looking at the factors mentioned in this short report, we do think that its cash burn is a bit risky, and it does make us slightly nervous about the stock. Its important for readers to be cognizant of the risks that can affect the company's operations, and we've picked out 4 warning signs for Spire Global that investors should know when investing in the stock.
Of course, you might find a fantastic investment by looking elsewhere. So take a peek at this free list of companies with significant insider holdings, and this list of stocks growth stocks (according to analyst forecasts)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.